
Fastenal (FAST) Stock Still Looks Rich On Strong Q3 Profit Growth
Fastenal has delivered a powerful share run in recent years, and the latest earnings strength keeps attention firmly on what investors are paying for each dollar of profit. With the stock around US$51.91, the key question is whether that price still lines up with the company’s earnings power.
- Over the past 5 years, Fastenal has returned 104.1%, which puts pressure on the valuation case to be backed by equally convincing earnings.
- Recent profit growth and stronger margins suggest the business can support a richer earnings profile, which may directly influence how investors judge its P/E and related earnings multiples.
- There is a second opinion on Fastenal worth weighing. See what analysts think Fastenal's shares could be worth.
The stock’s next move may depend on whether Fastenal’s current earnings justify today’s share price when compared with the Fair Ratio benchmark.
If you want to see how other industrial-focused companies measure up on similar earnings questions, compare Fastenal with solid balance sheet and fundamentals stocks screener (24 results).
Is Fastenal Getting Expensive on Earnings?
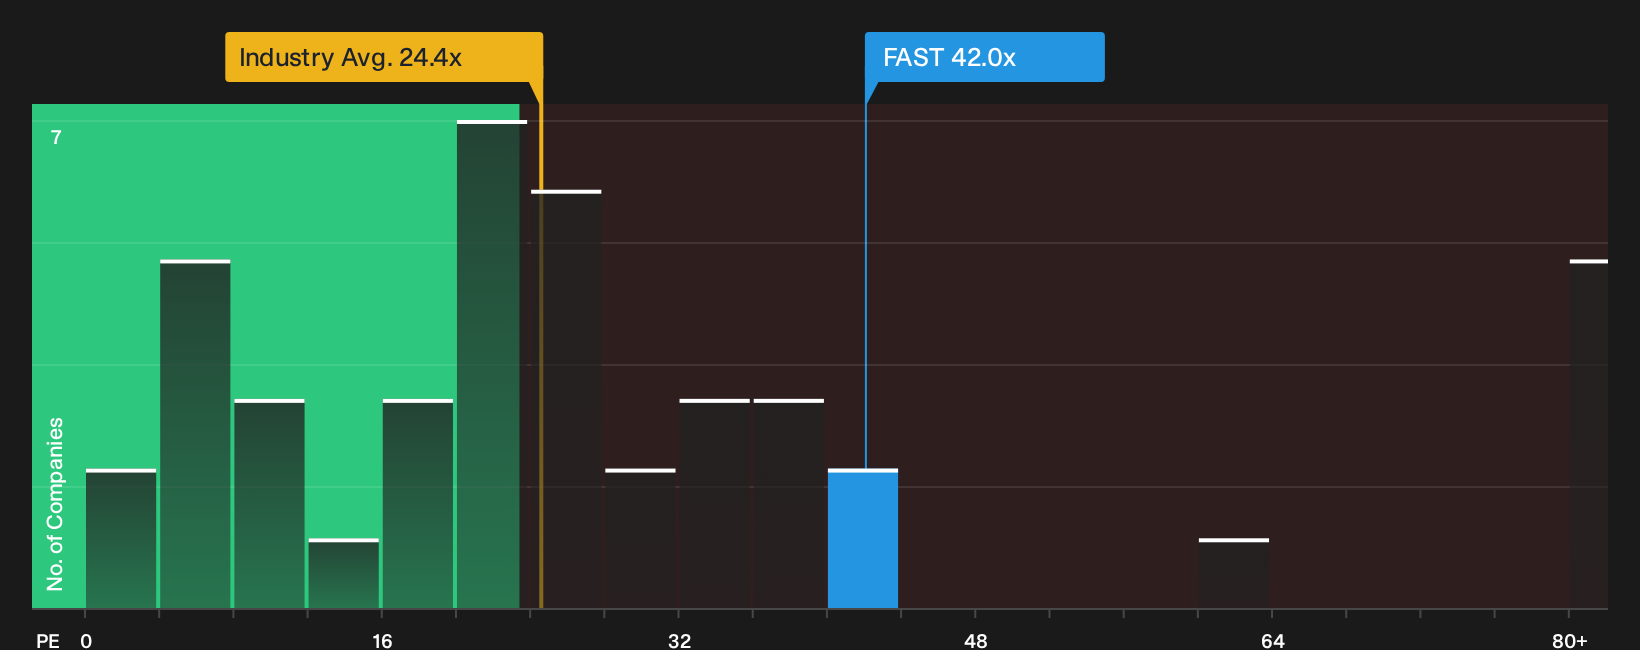
P/E fits Fastenal because earnings remain the clearest anchor for what investors are paying for this mature distributor. On that yardstick, the stock trades on roughly 42.0x earnings, which is far above the Trade Distributors sector on about 24.4x and its peer group around 25.8x. That gap means every dollar of Fastenal profit currently carries a materially higher price tag than the typical industrial supplier.
The Fair Ratio, which blends Fastenal’s growth record, profitability, size and risk into a tailored benchmark, points to the shares screening overvalued on earnings. Because the latest Q3 2026 report showed strong profit expansion and margin strength, the rich 42.0x P/E looks closely tied to confidence that this level of performance can be sustained. For anyone weighing an entry or adding to a position, the key question is whether Fastenal’s operational quality and competitive position justify paying such a premium multiple relative to sector norms and that Fair Ratio anchor. Explore the numbers behind Fastenal's P/E valuation.
The Fastenal Narrative: What Would Justify Today's Price?
Fastenal’s rich P/E sets up a clear puzzle, and Simply Wall St Narratives aim to spell out which earnings paths would need to play out for the stock to look materially stronger or weaker than today’s price. Each narrative ties its number to a concrete view of where Fastenal’s growth, margins and risks go next. This gives you a reference point you can revisit as new information emerges on the Community page.
Fastenal brings out a split in the community, with one group seeing more upside in the current setup than the other side does.
Bull case: 12% undervalued
"Fastenal is using its shift toward large onsite and high spend customer sites, which now account for just over half of sales and grew revenue more than 26% year over year, to deepen embedded supply chain roles inside key accounts…"
Discover why this Narrative puts Fastenal at 12% undervalued.
Bear case: roughly fairly valued
"The current valuation, together with this narrative’s view that Fastenal is fairly valued and bullish, implies that the share price already reflects meaningful confidence in its high ROIC, elevated CapEx plans and expansion of digital and on site service revenue…"
Explore why this Narrative puts Fastenal at roughly fairly valued.
Fastenal’s price is only half the story
Shares can look expensive or cheap, yet your outcome still leans heavily on who is steering Fastenal and how their rewards line up with your interests. See who runs Fastenal and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com