
Will Capital Deployment Shift Change Berkshire Hathaway (BRK.A) Narrative
- Berkshire Hathaway, under new CEO Greg Abel, has been putting its large cash pile to work by buying businesses, investing in technology, and stepping up share repurchases, while still relying on diversified operations and disciplined insurance underwriting.
- The potential move into funding Meta’s AI projects would shift Berkshire Hathaway closer to core infrastructure for artificial intelligence rather than only traditional sectors, raising fresh questions about how Abel prioritizes large-scale capital deployment across utilities, insurance, and equity stakes.
- We will look at how Berkshire Hathaway’s investment narrative is shaped by Greg Abel’s more active capital deployment and AI focused investments.
Scan how Berkshire Hathaway’s evolving AI and infrastructure story compares with other hand picked 55 AI infrastructure stocks riding similar long term data center and compute demand themes.
Berkshire Hathaway Investment Narrative Recap
Berkshire Hathaway asks you to believe in a diversified, cash rich operation that can keep recycling earnings from insurance, rail, utilities, housing and large equity positions into new opportunities. The short term swing factor is how Greg Abel puts that liquidity to work while keeping underwriting discipline and infrastructure projects on track.
The biggest near term risk is leadership transition perception and any misstep in big capital projects like data center driven power investments, especially if communities resist or returns look thin. The recent share price high and AI related headlines do not fundamentally change that core equation for now.
The potential early equity funding for Meta’s AI buildout is the most relevant update. It sits directly on top of two live themes for Berkshire Hathaway: rising AI related electricity demand that could feed its utilities, and the shift in equity exposure toward core compute infrastructure rather than only traditional holdings.
If such a deal appears in future filings, investors will likely weigh it against existing catalysts such as housing exposure from Taylor Morrison, insurance expansion and long dated stakes in Alphabet and Japanese trading houses. The question then becomes execution, concentration risk and how comfortably the group can absorb another large scale commitment.
What The Current Berkshire Hathaway Forecasts Actually Assume
Berkshire Hathaway's latest analyst models sketch out a future that leans heavily on moderate revenue expansion and slimmer profitability, while Greg Abel reallocates capital toward areas like AI linked infrastructure.
Consensus figures point to revenue rising at 5.3% a year over the next three years, paired with profit margins moving from 22.3% today to 11.8% by 2029. Earnings are projected at US$53.1b in that year compared with earnings today of US$85.8b, which implies an earnings decline of about US$32.7b even as the top line grows and share count is expected to edge down by 0.77% annually.
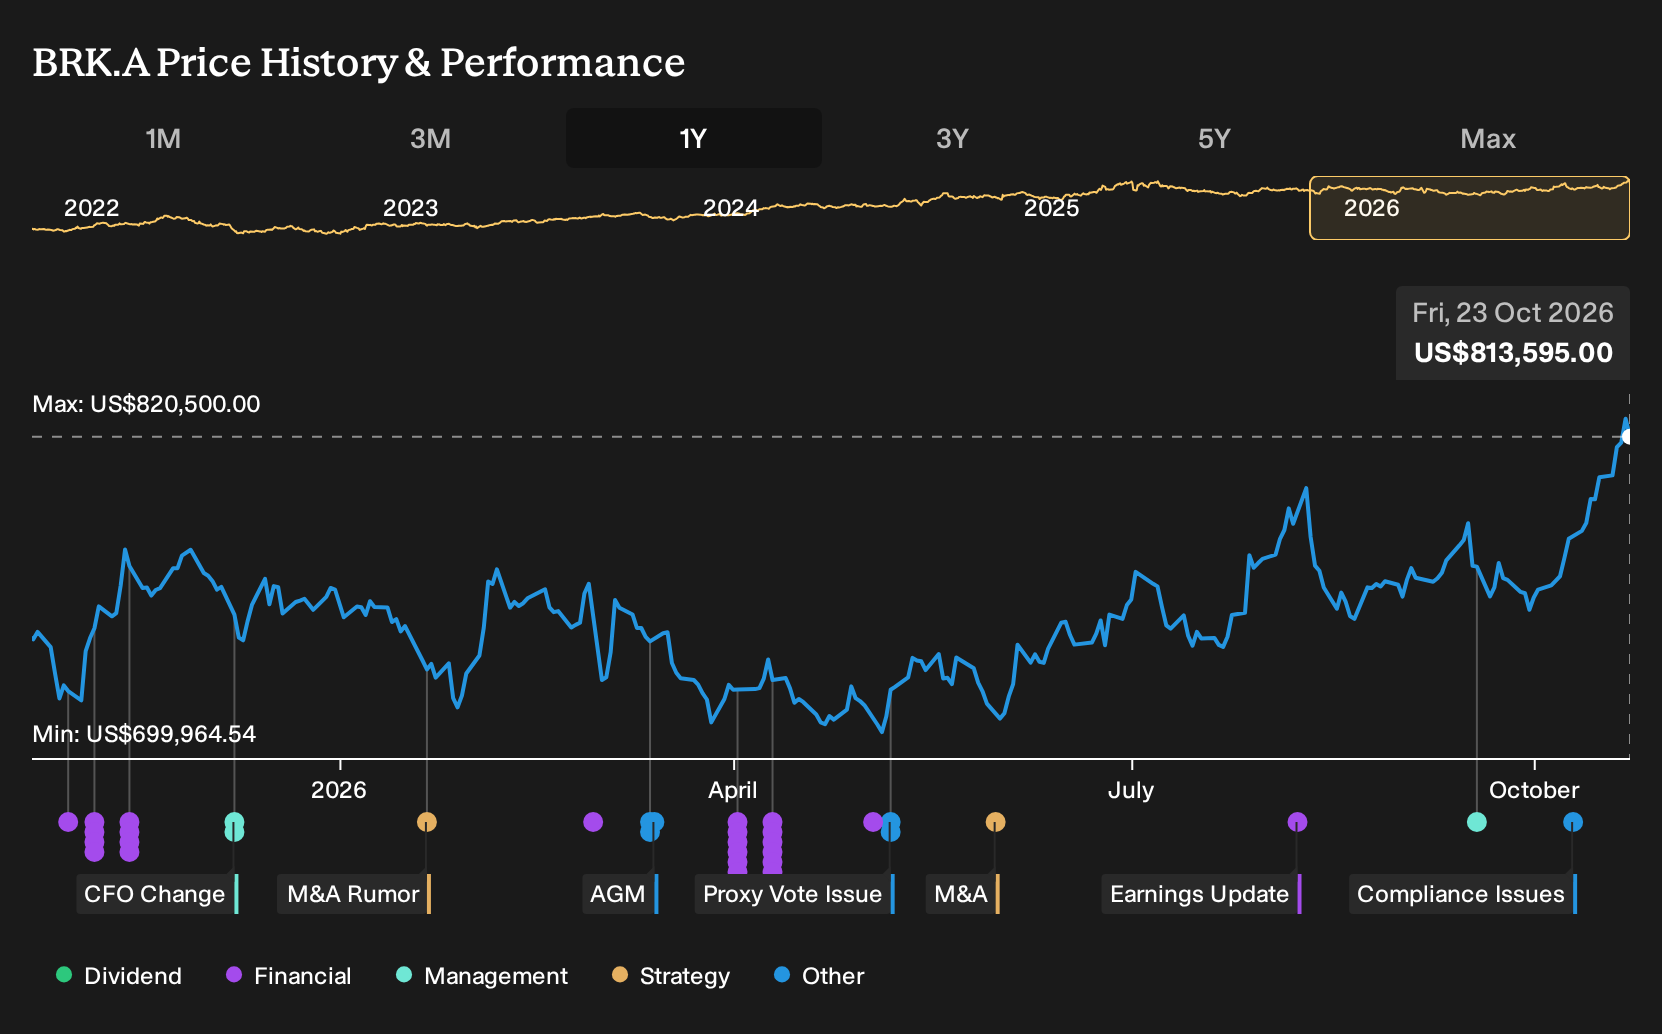
On these numbers, Berkshire Hathaway would be generating US$448.5b of revenue and US$53.1b of earnings in 2029, with the stock trading on a P/E multiple of 26.1x versus 12.7x today and above the US diversified financials sector at 17.2x. The analyst framework applies a discount rate close to 7.5% and produces a consensus price target of US$799,502.75, only about 4.5% above the current share price of US$763,600.01. This indicates that many observers see the shares as roughly aligned with their fair value estimates rather than clearly mispriced.
Under the hood, that leaves you weighing a few moving parts: a long runway of reinvestment into utilities and data center related power projects; a potential shift toward AI infrastructure exposure through Meta and other large tech platforms; and a leadership transition that keeps the cultural playbook intact while possibly changing the pace and style of very large deals.
Berkshire Hathaway's narrative projects US$448.5b revenue and US$53.1b earnings by 2029. This assumes 5.3% yearly revenue growth and an earnings decrease of about US$32.7b from earnings today of US$85.8b.
Uncover why Berkshire Hathaway's fair value is essentially aligned with its current price.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community cluster between about US$799,503 and US$1,190,270, which leaves plenty of room for disagreement on where Berkshire Hathaway should trade. You are weighing that spread against leadership transition risks, AI related power projects and housing exposure, so it makes sense to review multiple community viewpoints.
Explore 3 other Berkshire Hathaway fair value estimates, including one that suggests as much as 46% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Berkshire Hathaway research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Berkshire Hathaway. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Berkshire Hathaway's overall financial health at a glance.
Looking for more Berkshire Hathaway style investment ideas?
If the Berkshire Hathaway story has you thinking about portfolio balance, cash generation and resilience, it can help to scan a wider field of companies that share some of those qualities in different ways.
- If you want a broader hunting ground for potential value opportunities with strong fundamentals, start with a focused set of 29 high quality undervalued stocks that already clear basic quality checks.
- For investors who care most about stability and capital preservation, filter for 1 resilient stocks with low risk scores that score well on balance sheet strength and volatility measures.
- To broaden your watchlist with businesses that combine financial resilience and solid operations, work through a curated list of solid balance sheet and fundamentals (24 results) that can anchor long term research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com