
Did Falling Egg Sales Just Shift Cal Maine Foods Stock Investment Narrative?
- Cal-Maine Foods has reported about a 5% annual decline in sales over the past three years, alongside a large 54.9% annual drop in earnings per share and weaker free cash flow margins as capital intensity has risen.
- The combination of falling earnings power and more capital-hungry operations suggests the egg producer’s vertically integrated model is under pressure from both consumer demand and cost trends.
- We will now look at how Cal-Maine Foods' shrinking earnings and cash generation may reshape the longer-term investment narrative.
Cal-Maine Foods Investment Narrative Recap
For a shareholder in Cal-Maine Foods, the core belief is simple. You need to think this vertically integrated egg producer can arrest the 5% annual sales decline and rebuild earnings power after a very sharp 54.9% annual drop in EPS. The near term swing factor is whether pricing and mix in specialty and prepared eggs can offset weaker volumes and higher operating costs.
The biggest risk is that rising capital intensity and softer free cash flow margins become the new normal rather than a temporary reset. If returns on that extra investment do not show up in steadier margins or cleaner cash conversion, the current operating squeeze could linger. If that happens, the long term narrative around Cal-Maine Foods as a low cost, resilient producer looks more fragile.
Recent commentary around Cal-Maine Foods has focused on the forward P/S multiple of 1.2x. That valuation sits against a business where reported profits have come under pressure and the current net margin of 2.3% is far below last year’s 28.9%. For you as an investor, the relevant link is between that compression in profitability and whether any improvement in mix or biosecurity spending can stabilise returns.
Analysts model earnings expansion over the next few years and see revenue growing at 4.5% annually. That view assumes the company can convert investments in specialty eggs, prepared foods and automation into higher margin sales without major disruption from avian influenza or industry oversupply. The recent weak EPS trend and heavier capex raise the execution bar on those catalysts.
Cal-Maine Foods' current analyst script points to revenue of US$2.8b and earnings of US$124.8m by 2029. That path is built on 3.5% yearly revenue growth and an earnings increase of about US$66.1m from US$58.7m today.
Discover how Cal-Maine Foods' fair value indicates a 9% potential upside to its current price that may not last much longer.
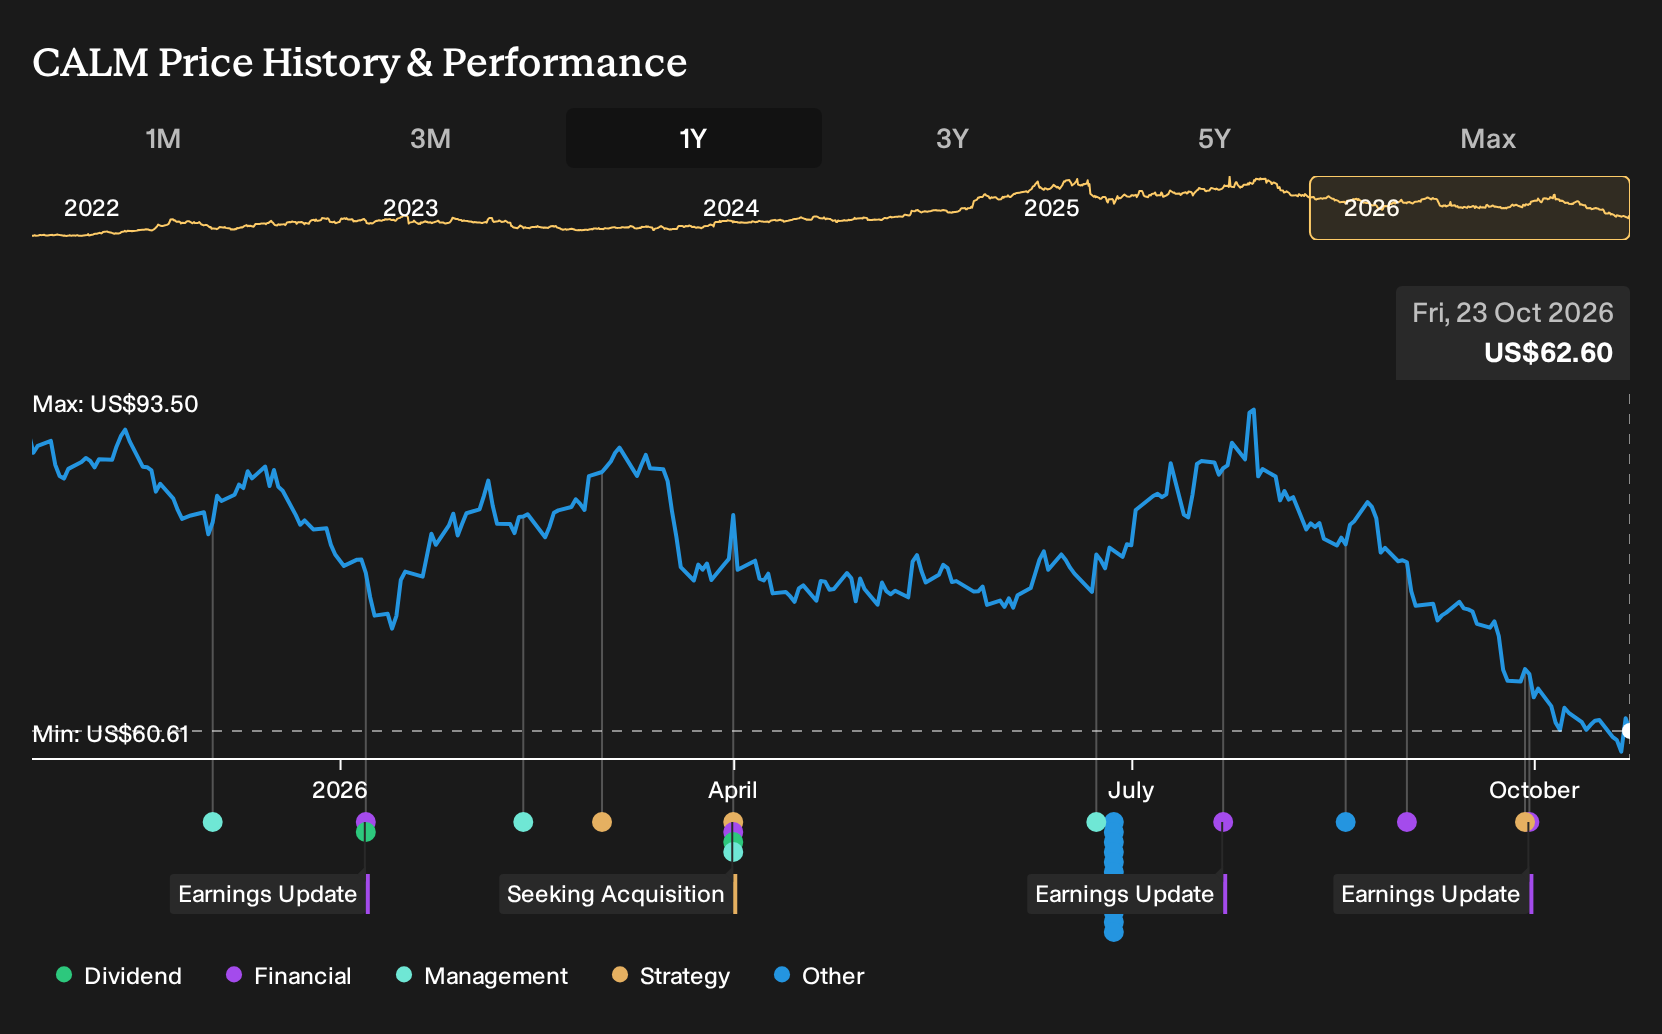
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span a wide band, from US$16.32 at the low end to US$68.33 at the high end, which shows how far apart opinions on Cal-Maine Foods can be. When you factor in ongoing avian influenza risk and mix shifts into specialty eggs, there is plenty of room for alternative views worth exploring.
Explore 3 other Cal-Maine Foods fair value estimates, including one that suggests as much as 74% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cal-Maine Foods research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cal-Maine Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cal-Maine Foods' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cal-Maine Foods?
If the Cal-Maine Foods story has you reassessing where risk and reward feel acceptable, it can help to scan a wider field of potential holdings using the Simply Wall St Screener and compare business quality side by side.
- For investors who want potential mispricings backed by solid fundamentals, review our 21 high quality undiscovered gems that may sit off the usual radar.
- If income is a priority, focus on cash returns with our 5 dividend fortresses that target higher yielding payers.
- When capital protection comes first, narrow your watchlist to companies with stronger finances using our list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com