
SITC International Holdings (SEHK:1308) Lifted Revenue And Declared A Special Dividend, Is It Still Below Fair Value?
SITC International Holdings event overview
SITC International Holdings (SEHK:1308) moved back into focus after management declared a HK$1.00 per share special dividend and reported higher nine month revenue, volumes and freight rates for 2026.
At a share price of HK$47.68, SITC International Holdings has had a strong run, with a 90 day share price return of 23.46% and a year to date share price gain of 69.44%. Total shareholder return over three years is very large at about 4x, suggesting recent momentum has built on already substantial long term gains as investors react to higher revenue, firmer freight rates, the stock split plan and the special dividend announcement.
Compare how SITC International Holdings stacks up against other shipping and logistics plays that show strong recent momentum and healthy balance sheets by reviewing the curated list of solid balance sheet and fundamentals (205 results) in the same session.
SITC International Holdings now pairs a sizeable logistics platform with a share price that has already moved hard on good news. The real test is whether that business strength is fairly reflected in today’s valuation.
Price-to-Earnings of 13x: Is it justified?
SITC International Holdings now trades on a P/E of 13x, which looks full when set against both peer valuations and the recent share price strength from HK$47.68.
The P/E multiple compares the HK$47.68 share price with the company’s earnings per share. It therefore reflects how much investors are willing to pay for each dollar of profit. For a shipping and logistics group with earnings that declined 3.1% per year over the past five years and fell over the last twelve months, this is not a low bar.
Relative to the Asian Shipping industry average P/E of 11.2x and a peer group on 10.4x, the 13x ratio looks demanding. It also sits above an estimated fair P/E of 9.2x, which indicates the valuation could move toward a lower level if sentiment around earnings softens.
Explore the SWS fair ratio for SITC International Holdings.
Result: Price-to-Earnings of 13x (OVERVALUED)
Still, SITC International Holdings faces clear risks if freight rates weaken further or if earnings, which have already declined annually, fall short of current expectations.
Find out about the key risks to this SITC International Holdings narrative.
Another view on SITC International Holdings’ value
The P/E of 13x makes SITC International Holdings look expensive on earnings, yet the SWS DCF model points the other way. At HK$47.68, the stock trades about 31.1% below an estimated fair value of HK$69.23. That gap raises a simple question: Which metric deserves more weight for you?
Look into how the SWS DCF model arrives at its fair value.
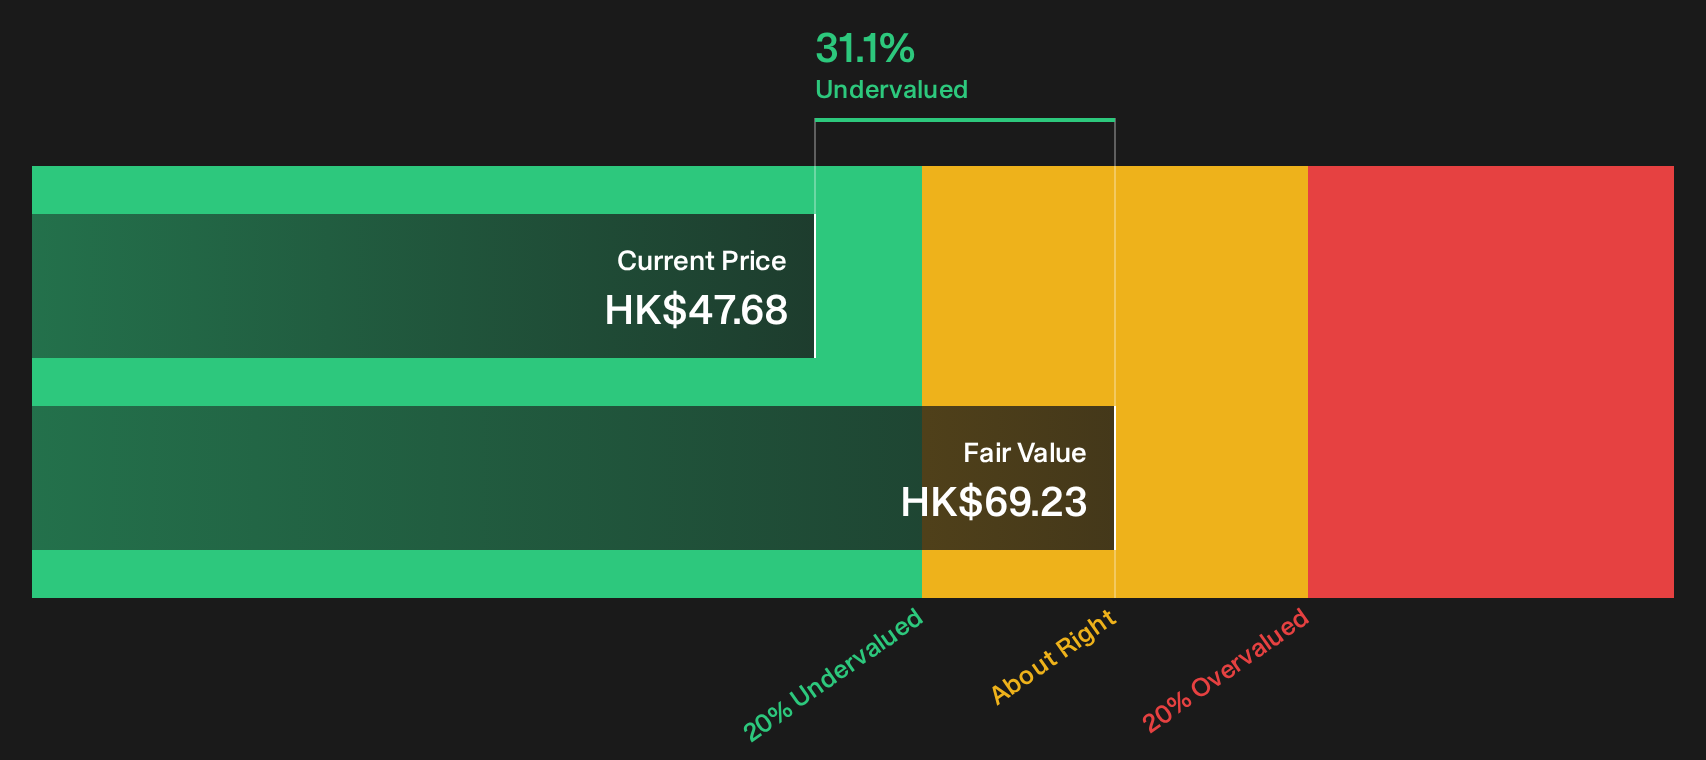
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SITC International Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does SITC International Holdings feel expensive or just misunderstood at this price, given both flagged risks and clear potential rewards? Take a closer look at the underlying data and form your own stance by reviewing the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond SITC International Holdings?
Do not stop your research with SITC International Holdings. Broaden your watchlist with fresh ideas that match your risk tolerance and income goals using targeted screeners.
- Target higher income potential by reviewing 225 dividend fortresses that may suit investors who want meaningful yield backed by stronger balance sheets.
- Hunt for mispriced quality by scanning 193 high quality undervalued stocks that combine robust fundamentals with prices that look out of step with underlying performance.
- Focus on resilience first by filtering for 221 resilient stocks with low risk scores that score well on financial strength so short term shocks are less likely to dominate the story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com