
Is KBC Group (ENXTBR:KBC) Fairly Valued After Its Crypto Push?
KBC Group (ENXTBR:KBC) is drawing investor attention after lifting its exposure to Strategy shares and preparing Bitcoin and Ether trading for retail clients through its Bolero platform under the EU’s MiCAR framework.
For context, KBC Group’s share price has slipped over the past month, with a 30 day share price return of down 14.05% and a 7 day move of down 6.07%. However, the 1 year total shareholder return of 16.38% and very large 3 year total shareholder return suggest that longer term momentum has been far stronger than recent trading implies.
Scan for other banks leaning into digital assets with a similar mix of crypto exposure and traditional earnings power by filtering through the 18 cryptocurrency and blockchain stocks.
The pullback in KBC Group after a strong multi year run leaves a simple tension: has most of the upside already played out, or do the current valuation markers still suggest room on the table?
Most Popular Narrative: 3% Undervalued
The latest widely followed valuation narrative pegs KBC Group’s fair value at €116.94, slightly above the recent €113.75 close. This puts recent share weakness in context and highlights a modest implied upside from here.
The central finding of this analysis is a stark disagreement between valuation lenses.
The Dividend Lens (DDM): At €126.41, the DDM suggests KBC is slightly undervalued relative to its market price of €120.10. This outcome is driven by high proposed cash payouts (€5.10 per share for FY2025).
The Book Value Lens (RIM): At €83.18, the RIM indicates substantial overvaluation. This reflects long-term normalization of Returns on Equity (ROE) toward historical capital costs.
No Confluence Zone: Across the entirety of both sensitivity grids, the DDM envelope (€90.27 to €220.03) and RIM envelope (€76.83 to €89.98) do not meet anywhere. This demonstrates how dependent bank valuations are on the choice of analytical perspective.
See why 2 investors see KBC Group as 3% undervalued.
Result: Fair Value of €116.94 (UNDERVALUED)
Still, two pressure points could upend the KBC Group story: a higher required return on equity and any shift away from the current dividend policy.
Find out about the key risks to this KBC Group narrative.
Another View: KBC Group Through The Earnings Lens
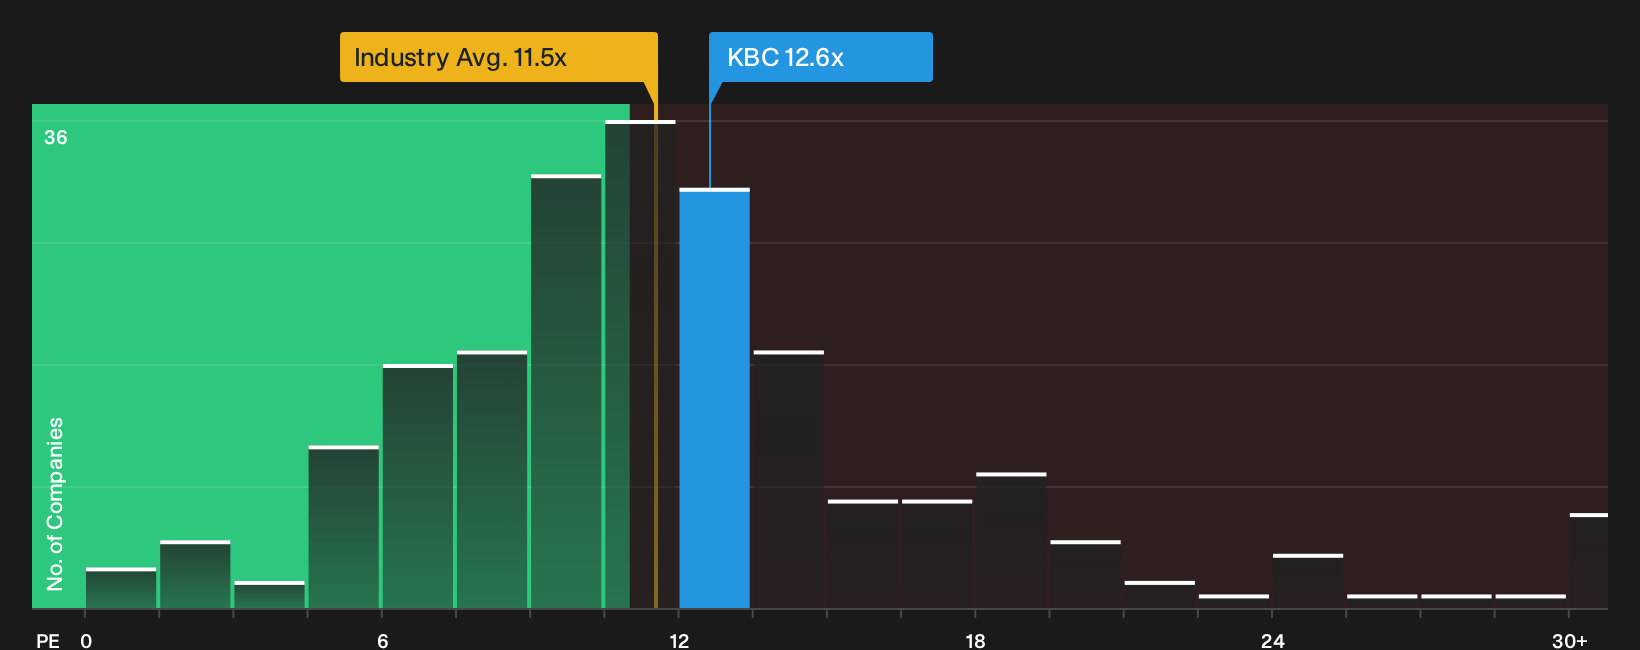
Look past the narrative fair value and KBC Group appears less relaxed on simple earnings metrics. The shares trade on a P/E of 12.6x, compared with 9x for peers and a fair ratio of 18.7x that the market could move toward over time.
This mix of richer pricing than direct comparables but a discount to the fair ratio leaves investors with a real question. Is the premium a sign of quality that eventually closes the gap, or does it cap future upside if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on KBC Group so far, or a clear signal hiding in plain sight. Consider your options while sentiment is still shifting and weigh both sides of the ledger by checking the 3 key rewards and 2 important warning signs.
Looking for more KBC Group style investment ideas?
Do not stop with KBC Group. Broaden your watchlist now by using focused screeners that surface stocks with clear financial traits you can compare side by side.
- Target potential mispricings by scanning a curated 193 high quality undervalued stocks that pairs solid fundamentals with prices that may not fully reflect underlying strength.
- Strengthen your income playbook by reviewing a hand picked 225 dividend fortresses that concentrates on higher yielding businesses with robust payout profiles.
- Prioritise resilience by working through a 221 resilient stocks with low risk scores that highlights companies with sturdier risk scores when markets feel less forgiving.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com