
Best British Dividend Stocks In October 2026
Higher interest rates have made cash savings more tempting, yet UK dividend shares offering more than a 3% yield with solid coverage and steady growth can still provide a powerful blend of income and potential capital upside. With the government planning more than £1b for social and affordable housing, investors are again eyeing dependable local payers. This article highlights three high-quality British dividend payers from that shortlist.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividends that look well covered and relatively steady. However, if you want the pick of this theme, these 5 dividend aristocrats stocks are the best of the best.
Rathbones Group (LSE:RAT)
Rathbones Group is a long-established wealth and asset manager whose steady fee income is closely tied to the Dividend Powerhouses theme through recurring cash flows that help support a 3%+ payout.
Rathbones Group Plc runs a predominantly UK-focused wealth operation, earning £875.5 million from Wealth Management and £86.2 million from Asset Management, and carries a market value of about £1.7b.
For income investors, the interest in Rathbones Group is simple. Reliable fees from discretionary wealth management and financial planning can create the kind of recurring cash generation that helps keep a higher dividend stream on track.
"The completion of the Investec Wealth & Investment (IW&I) integration unlocks significant scale advantages and operational synergies, providing a tangible opportunity to improve operating margins. Management expects these efficiencies to result in a 28% margin by Q4 2026 (from 25.4%), with full synergy benefit (~£60m annualized) set to be realized by the end of 2025."
What really matters now is how one less visible pressure shapes the gap between headline profitability and the cash available to support that income profile.
That tension is where the real story starts, and the full narrative for Rathbones Group shows how those cash pressures, integration gains and dividend ambitions could be quietly decoupling.

Man Group (LSE:EMG)
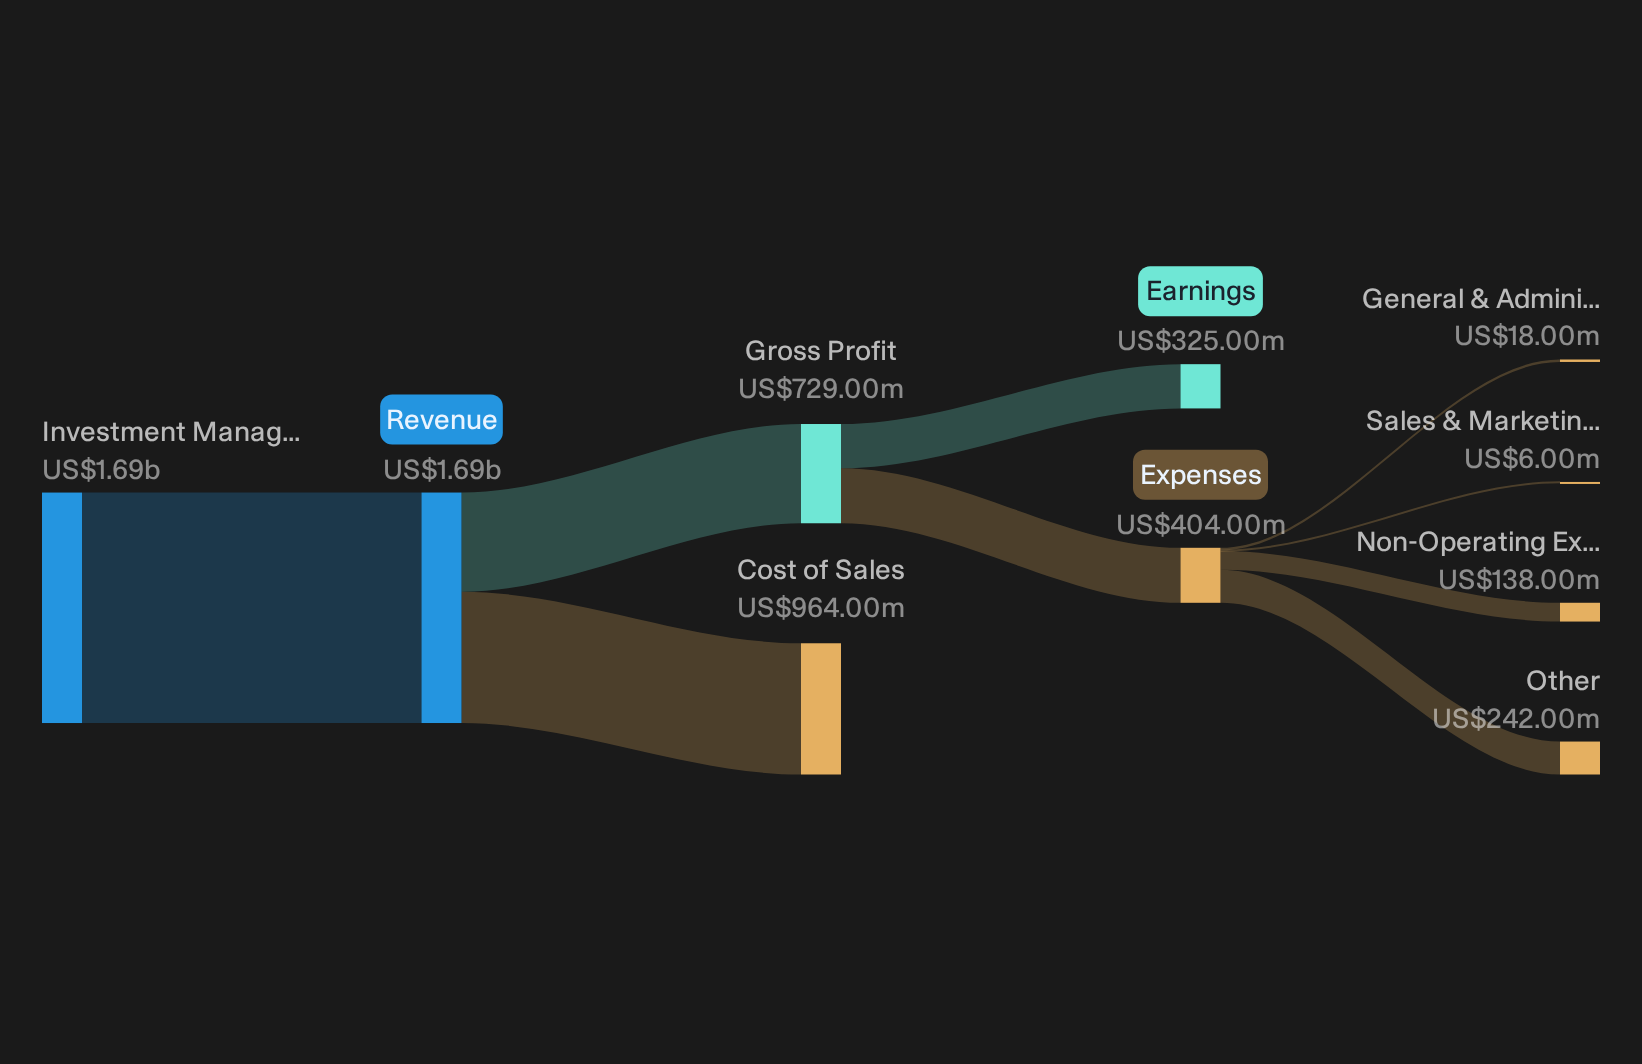
Man Group taps a single engine for the Dividend Powerhouses theme: regular cash dividends backed by fee income on the $1.7b it earns from its Investment Management Business and a market value of roughly £3.5b.
For income seekers, Man Group brings something different to the list: a fee-driven dividend policy anchored on long-only and alternative funds, where recurring charges on a growing pool of client assets can help keep a 3%+ yield on solid footing even as markets move around it.
"Although Man Group reports very strong AUM growth, the shift in mix that took the run rate net management fee margin from 63 bps at the end of 2024 to 52 bps at the end of 2025 points to future periods in which additional inflows into lower-fee long-only mandates dilute revenue yield and limit management fee growth relative to headline AUM."
The real question now is how one quiet shift in where those fees are earned ends up shaping the cash pool behind that dividend.
That quiet shift in fee mix is only part of the story, and the full narrative for Man Group shows whether it is masking resilient income strength or brewing payout pressure.
HICL Infrastructure (LSE:HICL)
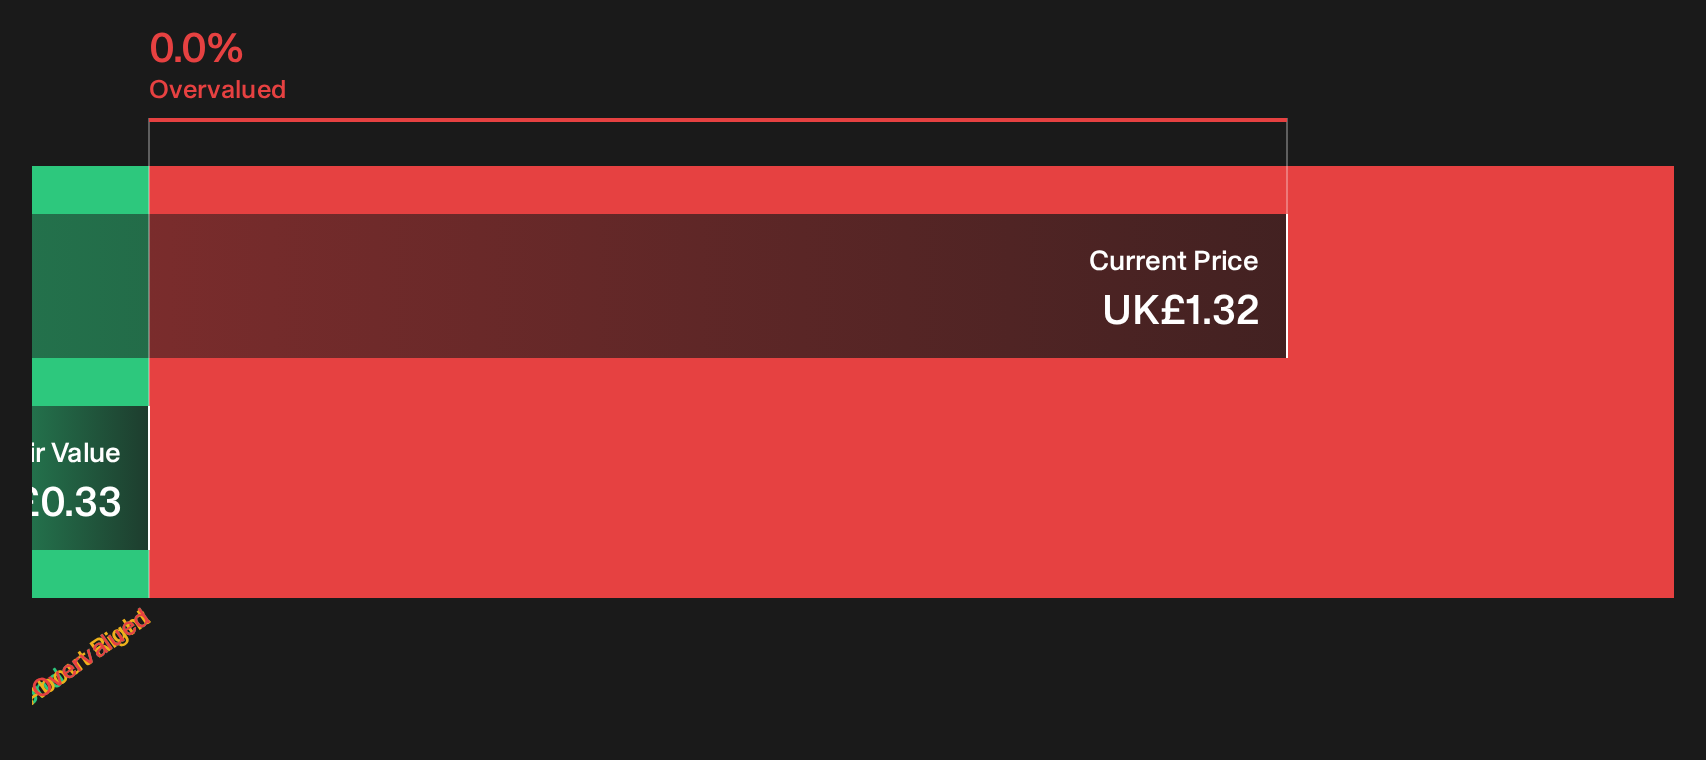
HICL Infrastructure is a £2.5b investment trust that owns income-generating infrastructure concessions, with all £277.5 million of revenue coming from its Investment in Infrastructure portfolio. This is used to support a covered, 3%+ style dividend profile.
HICL Infrastructure pairs a high 6.31% yield with long-term, contract-backed cash flows from essential assets, which fits neatly with a search for stable income. The catch is that free cash flow coverage and a debt-heavy funding mix need to keep pace, depending on how one unseen pressure plays out.
That unseen pressure on funding is the real swing factor. The HICL Infrastructure financial health report shows whether HICL Infrastructure’s payout is quietly stretching or still on firm footing.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities rarely stay quiet for long. When momentum builds, prices move and entry points often shift higher. Review these curated stock ideas that may be under the radar for now.
- Target reliable income streams and resilient balance sheets by reviewing the 5 dividend fortresses while yields remain attractive and sentiment has not fully caught up.
- Search for potential long-term compounders early by scanning the 5 high quality undiscovered gems before stronger momentum brings them into wider focus.
- Explore companies connected to the electric grid upgrade cycle by filtering through the 42 power grid technology and infrastructure stocks while infrastructure spending themes may still be developing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com