
Celanese (CE) Stock May Be Undervalued As LCP Prices Rise
Celanese has seen its share price climb 13.3% over the past year, but that move sits against a much longer slide that has left the stock down 68.3% over five years. With that kind of reset in investor expectations, the key issue now is whether the current market value is still in line with what the company actually generates in sales.
- The share price decline of 68.3% over five years puts the focus squarely on whether the business's revenue base can support today's valuation after such a long reset.
- The recent decision to raise global prices for liquid crystal polymer products may support future sales and margin resilience if demand holds up at higher price points.
- Your read on Celanese is one view; the desks covering it have another. See what analysts think Celanese's shares could be worth.
The stock's next move may depend on whether Celanese's current share price is appropriately anchored to the level and quality of its sales.
If you are weighing Celanese on its sales and pricing power, it can help to compare it with a wider set of companies screened on similar fundamentals through 29 high quality undervalued stocks.
Is Celanese a Bargain on Sales?
P/S fits Celanese because the core question for this stock right now is how much investors are paying for each dollar of sales in a cyclical chemicals business.
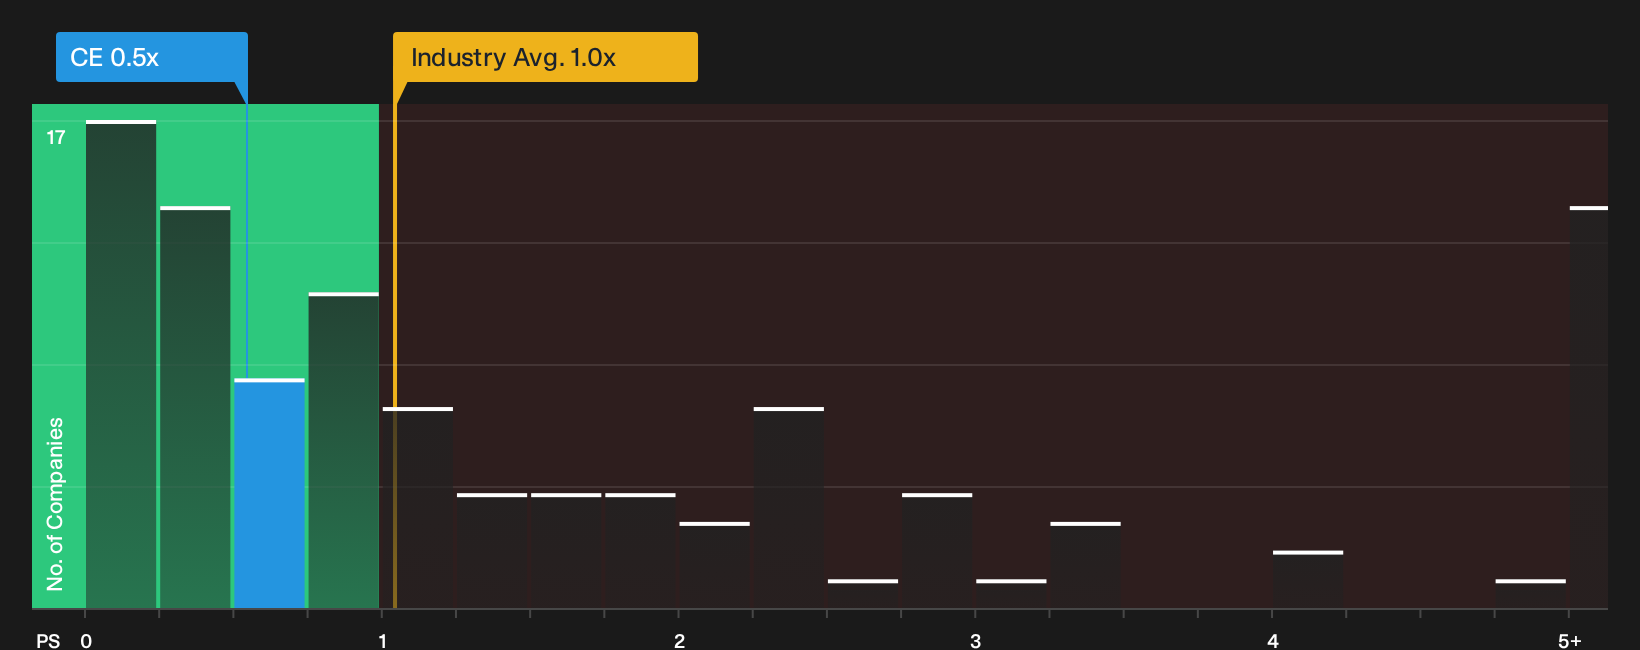
On this lens, Celanese trades on a P/S of about 0.5x, which is below both the Chemicals industry average of roughly 1.0x and a broader peer group closer to 2.7x. The Fair Ratio model, which adjusts for factors such as margins, growth profile, size and risk, points to a higher P/S than where the shares trade today, so the current tag screens as undervalued on this framework.
Because Celanese has just pushed through global price increases for its liquid crystal polymer products, the gap implied by the low P/S matters more for anyone who thinks that pricing power can be sustained. If those higher tags on LCP volumes hold, a sub-1x sales multiple leaves room for investors to debate whether the stock is pricing in too cautious a view of the revenue base. Explore the numbers behind Celanese's P/S valuation.
The Celanese Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Celanese valuation question leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the shares to be worth materially more or less than today. Each scenario links a fair value estimate to a clear story about Celanese's possible catalysts and pressure points, so you can track over time which version of events seems closest to reality on the Community page.
The Celanese crowd is split between those who see cash conversion upside and those who think current earnings quality already bakes in the good news.
Bull case: 42% undervalued
"Expansion of downstream acetyl derivatives such as vinyl acetate monomer, vinyl emulsions and redispersible powders, which management points to as the main source of profit uplift into 2026…"
Discover why this Narrative puts Celanese at 42% undervalued.
Bear case: 6% overvalued
"Even though management presents US$700 million to US$800 million of free cash flow as a baseline sustainable level, this profile is supported by ongoing restructuring, including footprint closures such as Lanaken and Ulsan…"
Explore why this Narrative puts Celanese at 6% overvalued.
Celanese price is only one side of the investment story
Valuation sets the entry point, but the next question is how the profit and revenue profile that analysts are modeling a few years out lines up with where Celanese trades today. Explore where analysts expect Celanese to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com