
What BP (LSE:BP.)'s Louisiana Spill Settlement Means For Shareholders
- BP updated its third quarter 2026 production guidance in the past, outlining upstream volumes of 2,190 to 2,240 mboe/d. It separately detailed oil output of 1,415 to 1,445 mboe/d and gas and low carbon energy of 775 to 795 mboe/d, while also agreeing to pay Louisiana about $350 million to settle remaining Deepwater Horizon claims.
- The one off Louisiana settlement removes a long running legal overhang and gives investors clearer visibility on BP’s future cash obligations and balance sheet planning.
- We will now look at how BP’s cleared Louisiana spill liabilities could reshape its investment narrative around cash flow and risk.
Scan how BP’s settlement and fresh production guidance stack up against peers by comparing it with 8 high quality undervalued stocks that also combine cash generation with balance sheet support.
BP Investment Narrative Recap
To own BP today, you need to believe the group can keep turning a very complex energy portfolio into steady cash, while tightening execution on costs and safety. The updated third quarter 2026 production guidance reinforces that the operating engine is running at scale, with both oil and gas plus low carbon units expected to contribute meaningful volumes.
The near term swing factor is still project delivery and margin improvement as BP pushes its cost reduction program and high grading of assets. The biggest watchpoint remains further write downs in lower returning transition projects and any fresh operational or labour setbacks that push up expenses or disrupt output.
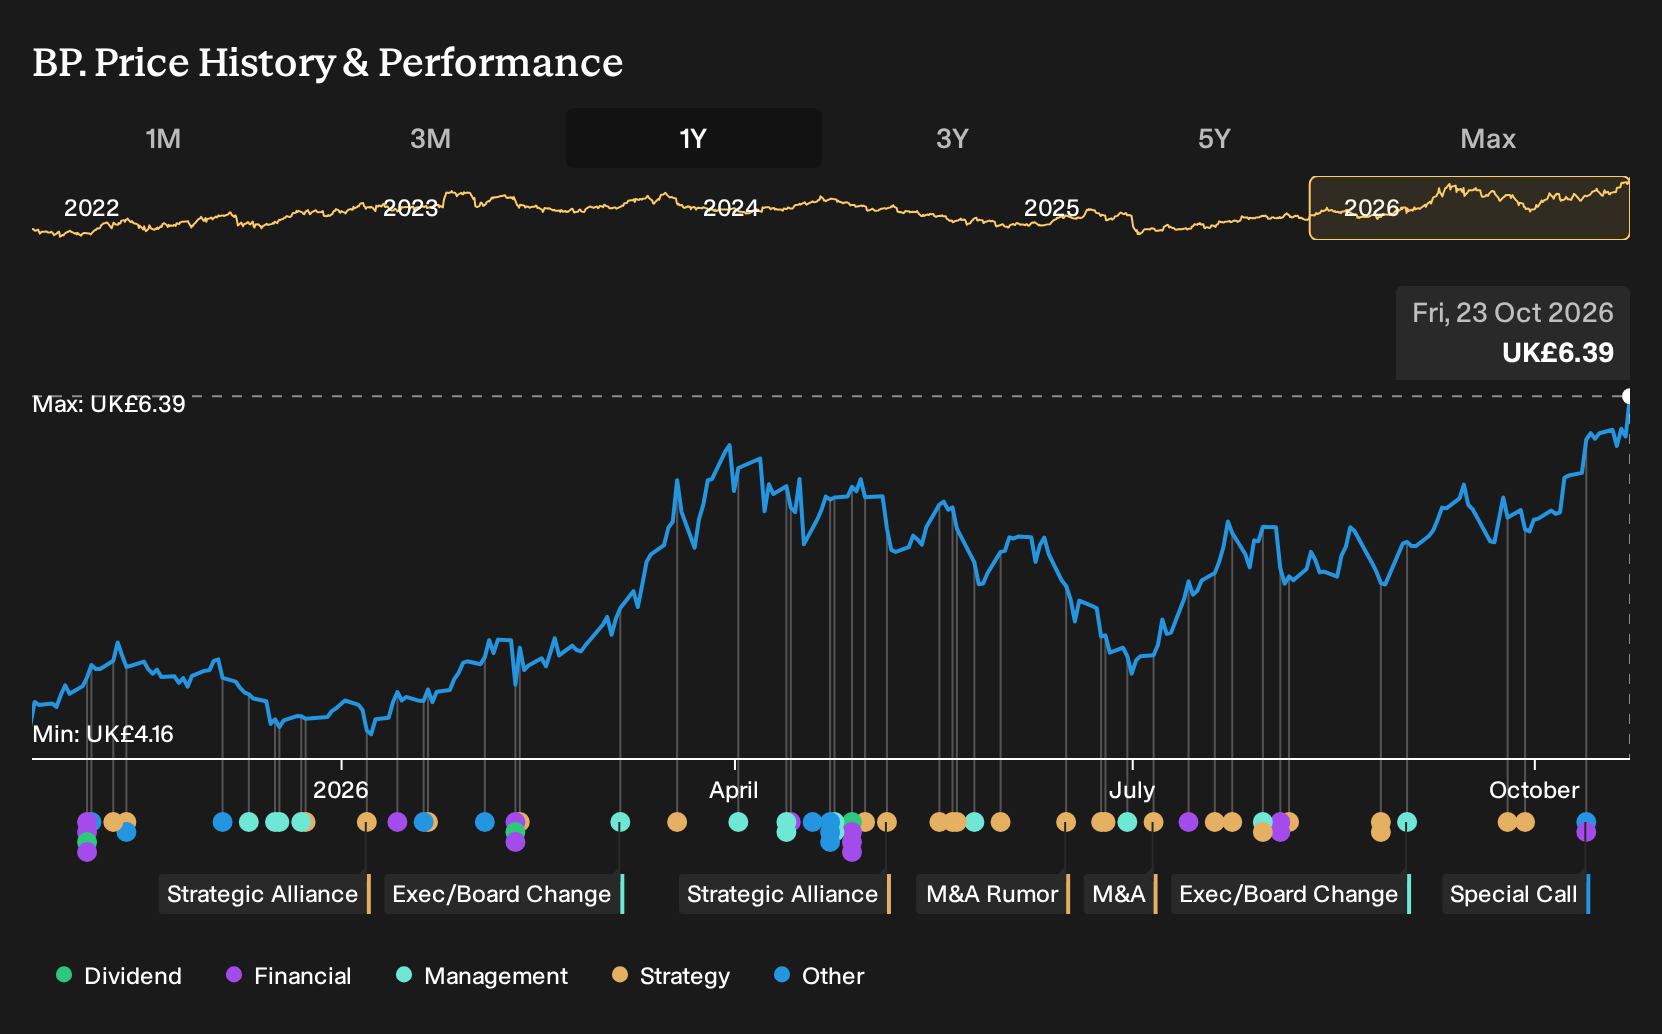
The Louisiana settlement is the announcement that matters most in this context. A single roughly $350 million payment clears remaining Deepwater Horizon claims with that state and gives BP a clearer line of sight on future cash obligations tied to the 2010 spill. That makes it easier for you to focus on operations rather than legacy liabilities.
With that legal overhang reduced, execution risks shift back toward the core catalysts. These include bringing upstream discoveries into production, meeting the targeted cost savings by 2027, and keeping process safety and labour relations stable. Options pricing currently signals room for sharp share price moves, so any miss or beat on these operational drivers could be reflected quickly.
Based on current analyst work, BP's narrative projects US$197.6b revenue and US$10.3b earnings by 2029. That path reflects a 2.8% yearly revenue decline and an earnings increase of roughly US$4.9b from US$5.4b today.
Uncover why BP's fair value points to a valuation that is roughly in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts framed BP’s heavy upstream tilt as a key upside catalyst, expecting revenue to reach about US$237.5b and earnings of US$12.3b by 2029, compared with the US$197.6b and US$10.3b in the baseline view. Those projections were set before this guidance and settlement, so you may want to compare several narratives and decide which assumptions feel realistic.
Explore 4 other BP fair value estimates, including one that suggests as much as 58% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your BP research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BP's overall financial health at a glance.
Looking for more BP investment ideas and peers?
If you want to stress test your BP view against other opportunities, the Simply Wall St Screener lets you quickly filter for companies that fit the kind of balance sheet strength, cash generation, or income profile you care about.
- If capital protection is your priority, you can focus on sturdier business models by scanning a 4 resilient stocks with low risk scores that scores well on resilience.
- Income driven investors can look for reliable payouts by reviewing a curated 5 dividend fortresses that may complement or contrast with BP’s profile.
- For those hunting for overlooked opportunities with solid fundamentals, you can broaden your watchlist using a targeted 5 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com