
Is Q3 Earnings Preview Altering The Investment Case For MGM Resorts (MGM)?
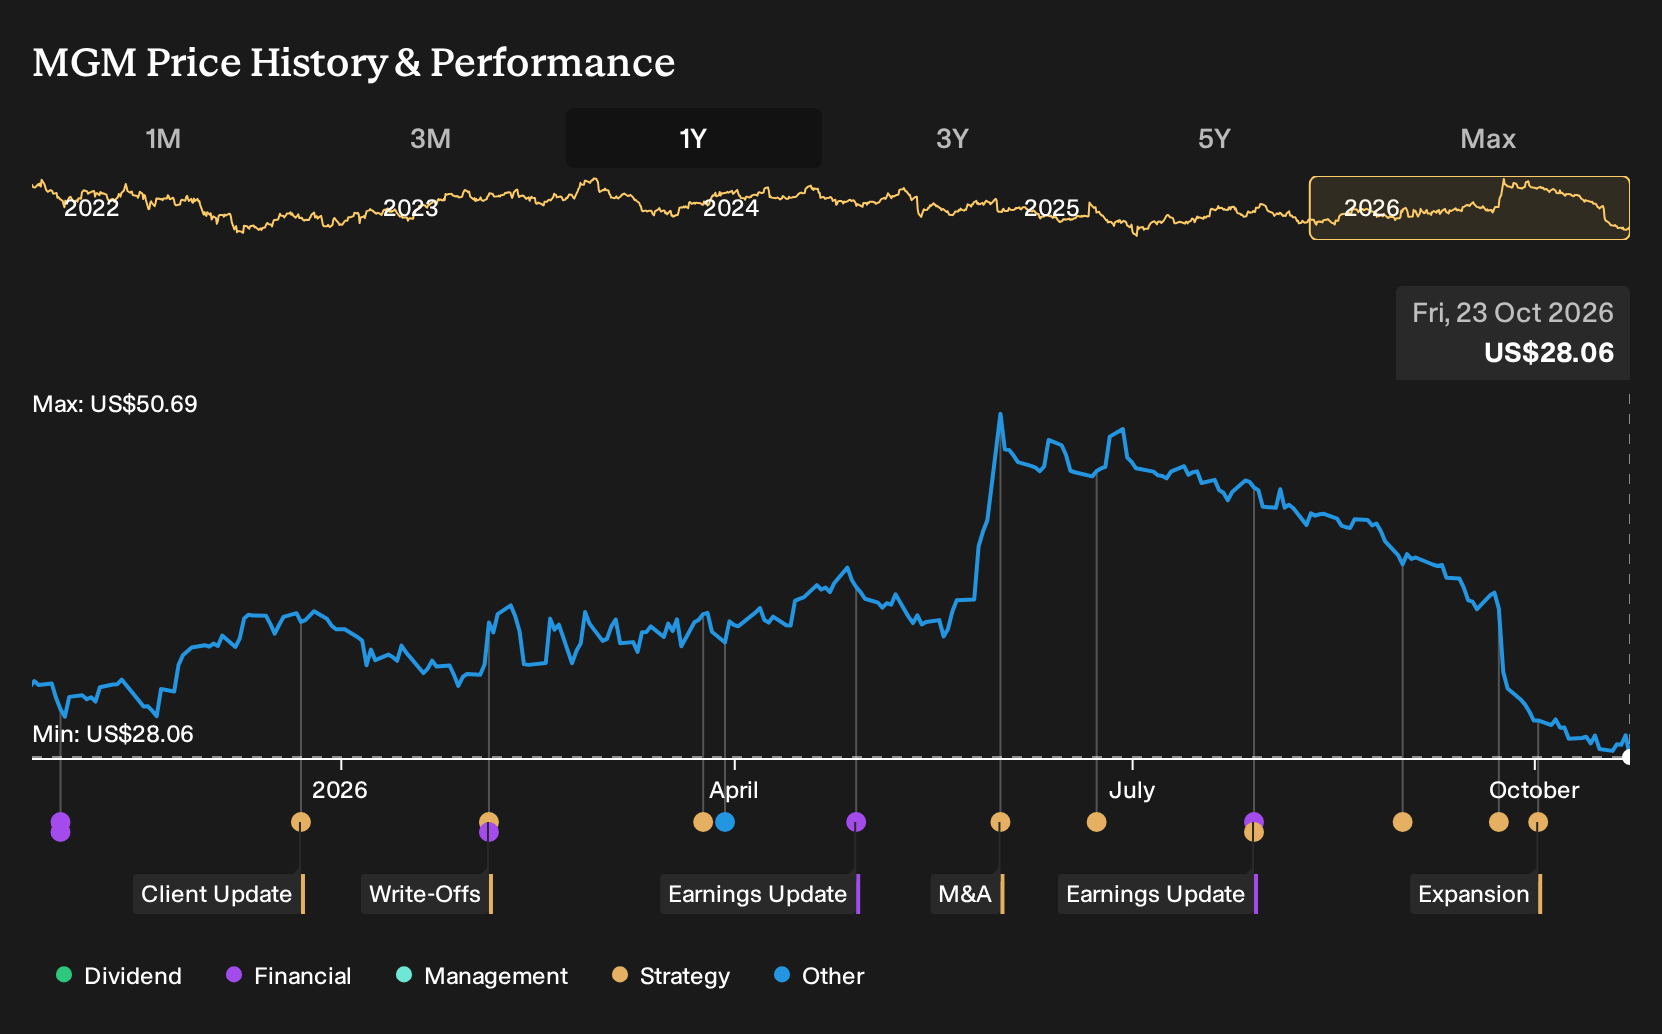
- MGM Resorts International is preparing to report Q3 2026 results after the close on October 28, with analysts expecting sharply lower adjusted earnings per share and slightly softer revenue versus last year as weaker Las Vegas visitor trends and broader macro pressures weigh on operations.
- The upcoming earnings release puts management’s commentary under the microscope, as investors look for clues on how MGM plans to balance Las Vegas softness, legal disputes such as the Springfield host community conflict, and capital intensive international projects within its existing balance sheet.
- We will now look at how MGM Resorts International's investment narrative lines up with Q3 earnings expectations and Las Vegas operational headwinds.
Scan how MGM Resorts International compares with other casino and leisure operators by running the hand picked 29 high quality undervalued stocks that pair cash flow strength with more resilient balance sheets.
MGM Resorts International Investment Narrative Recap
To own MGM Resorts International today, you need to believe the shift toward integrated resorts, digital gaming and international projects like Osaka eventually offsets softer Las Vegas trends and higher self insurance costs. The immediate swing factor is how much Las Vegas Strip and regional EBITDAR pressure shows up in Q3 and any near term operational comments.
The biggest near risk sits around high leverage and rising legal, insurance and arbitration related costs. The Springfield host community dispute and wider litigation can add noise but does not alter the core investment case unless it escalates into meaningfully higher cash outflows or restricts funding for Macau, Osaka or MGM Digital.
The Springfield arbitration fight is the clearest operational flashpoint tied to the latest headlines. Management is trying to move the host city dispute over delayed renovations and agreement compliance into private arbitration, while also pursuing a proposed sale of MGM Springfield to a Canadian private equity buyer, all under court oversight.
For you, the Springfield situation matters mainly as a test of execution, legal risk management and capital recycling. Any sale proceeds or capital relief only really help the thesis if MGM Resorts International keeps priority on funding Osaka, Macau upgrades and BetMGM, while preventing legal settlements, self insurance charges and higher interest costs from eating into already thin 2.4% net margins.
MGM Resorts International Forecasts Versus Today’s Earnings Power
MGM Resorts International's current consensus blueprint points to revenue of US$18.9b and earnings of US$436.5m by 2029. Analysts are working off an annual revenue growth assumption of 2.2%, with earnings expected to rise by about US$12.9m from US$423.6m today.
Uncover why MGM Resorts International's fair value indicates a 64% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts self insurance and legal costs at the center of the MGM Resorts International story rather than Osaka or digital growth. The most cautious analysts were building in flat revenue near US$17.9b and earnings of about US$541.5m by 2029 before this Springfield news. That more pessimistic setup shows how far opinions can spread, so it makes sense to compare several narratives yourself and watch how Q3 commentary and the arbitration process reshape these forecasts.
Explore 6 other MGM Resorts International fair value estimates, including one that suggests it could be worth just $27.97.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MGM Resorts International research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MGM Resorts International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MGM Resorts International's overall financial health at a glance.
Looking for more investment ideas beyond MGM Resorts International?
Once you have a view on MGM Resorts International, it helps to widen the lens and compare it with other listed businesses that match your preferred mix of quality, risk and income.
- For investors who want value and resilience to go hand in hand, start with a curated set of companies that combine stronger cash generation with sturdier finances through the 29 high quality undervalued stocks.
- If steady income is high on your checklist, target potential income payers offering higher yields and more robust dividend profiles via the 5 dividend fortresses.
- When capital preservation matters just as much as upside, focus on companies screened for sturdier balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com