
China International Capital (SEHK:3908), Why Is It Drawing Fresh Attention Today?
Renewed attention on China International Capital (SEHK:3908) has been triggered by its relatively low P/E ratio compared with capital markets peers. This has prompted investors to reassess whether current earnings fully support today’s discounted share price.
Recent trading has been choppy, with the share price at HK$18.23 after a 1-day share price gain of 1.67%. The 30-day share price return is down 9.21%, while the 3-year total shareholder return of 43.92% indicates longer term momentum that contrasts with the softer 1-year total shareholder return, which is down 18.11%.
Scan other low P/E opportunities that share China International Capital's value angle by reviewing our curated list of 194 high quality undervalued stocks.
The recent pullback, set against China International Capital’s three year gain of 43.92%, leaves you weighing business fundamentals against a mood shift in the market. Does the current P/E gap reflect value, or does it suggest doubt around those earnings?
Price-to-Earnings of 5.8x: Is it justified?
On the valuation side, China International Capital is trading on a P/E of 5.8x, which screens as inexpensive relative to both peers and the broader Hong Kong Capital Markets industry based on the data provided.
The P/E multiple links the current share price to the firm’s earnings per share. For a diversified financial group like China International Capital, which reports across investment banking, equities, FICC, asset management, private equity and wealth management, this ratio gives a quick sense of how much investors are willing to pay for each unit of profit.
With earnings described as high quality and forecast to grow 10.57% per year, a 5.8x P/E suggests the market is assigning a cautious price tag to those profits. The ratio is well below the Hong Kong Capital Markets industry average of 8.8x and also sits under the peer average of 9.2x, which points to a clear discount. The estimated fair P/E of 10.9x is materially higher than the current level, which highlights a gap that could close if sentiment shifts toward the fair ratio over time.
Explore the SWS fair ratio for China International Capital.
Result: Price-to-Earnings of 5.8x (UNDERVALUED)
Still, the weakness in the 1-year total shareholder return and the 30-day slide increases the risk that sentiment will remain cautious if earnings momentum softens or deal activity slows.
Find out about the key risks to this China International Capital narrative.
Another View: Cash Flows Paint An Even Cheaper Picture
The low P/E story for China International Capital is only one angle. Our DCF model, which prices the HK$18.23 share price against an estimated future cash flow value of HK$48.77, also flags the stock as undervalued. That is a wide gap. Could the market be mispricing the duration or resilience of those cash flows?
Look into how the SWS DCF model arrives at its fair value.
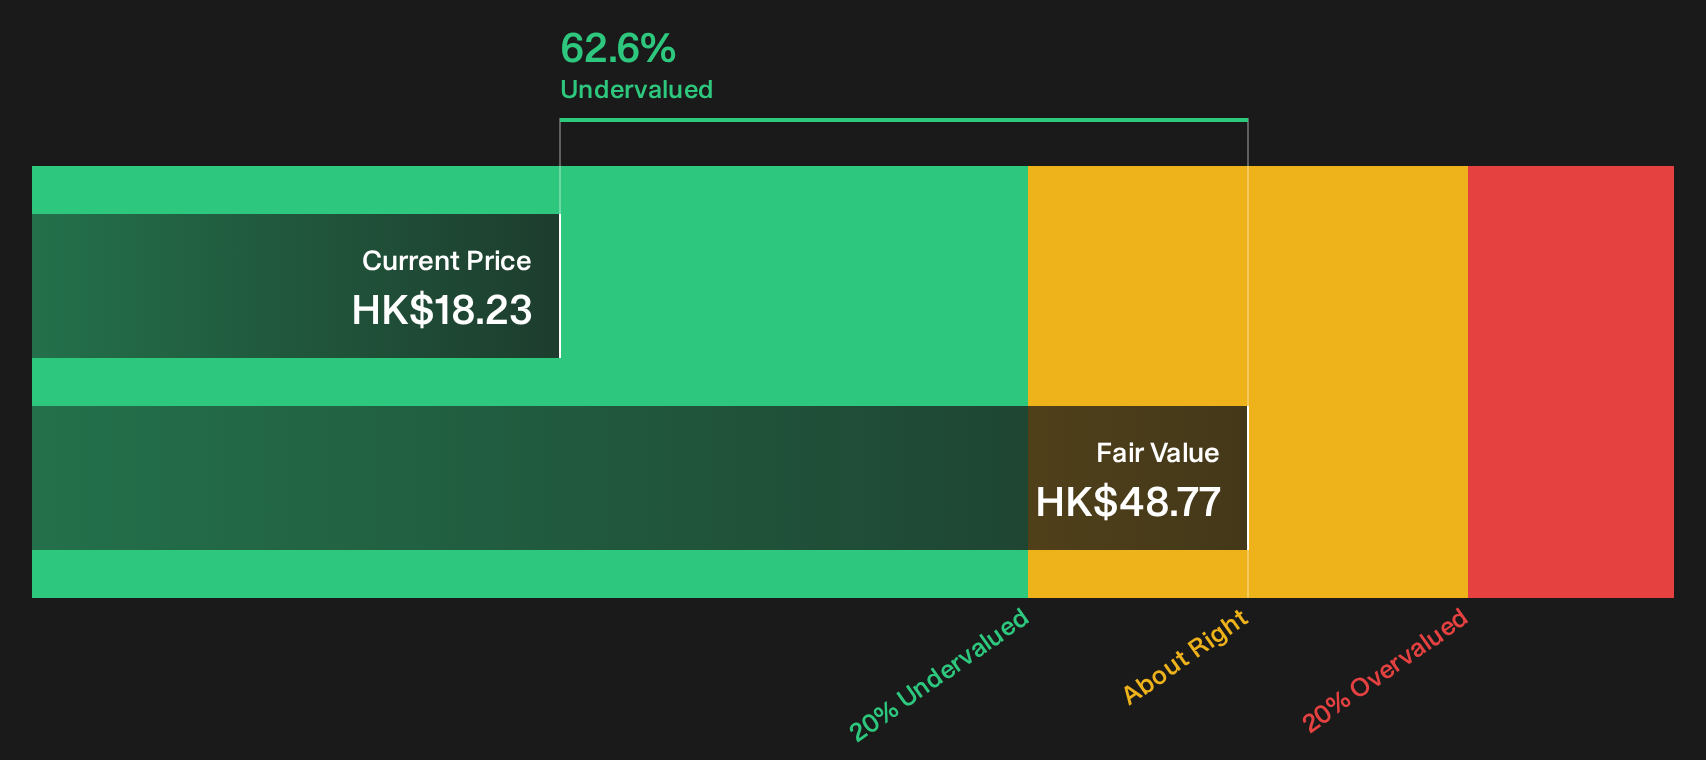
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China International Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the cautious tone around China International Capital matches your own reading of the numbers? Move quickly, stress test the assumptions, then weigh the 4 key rewards
Looking for more investment ideas beyond China International Capital?
If China International Capital has sharpened your focus on valuation, do not stop here. The next opportunity could already be on the radar of a targeted screener.
- Target potential mispriced opportunities early by scanning the 613 high quality undiscovered gems before they attract wider attention.
- Stack your portfolio with sturdier foundations by filtering for companies through our list of solid balance sheet and fundamentals (205 results) that can better handle pressure.
- Dial back portfolio stress and look for steadier performers by focusing on the 221 resilient stocks with low risk scores that fit your comfort zone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com