
Will AI Risk Platform Launch Change Brown & Brown (BRO) Stock Narrative
- Brown & Brown recently launched COMPASS, a connected intelligence platform that brings together its proprietary data, analytics, specialized knowledge and AI tools to help customers assess risk and make insurance decisions across Property & Casualty, Employee Benefits and Personal Lines.
- The firm is tying COMPASS to concrete use cases, from Health Plan Intelligence cost trend data to large corporate risk portfolio restructuring, which gives investors a clearer view of how Brown & Brown is trying to turn its AI and data investments into real operating benefits for clients.
- We will now look at how Brown & Brown's investment narrative could be influenced by the COMPASS AI driven risk intelligence rollout.
Brown & Brown Investment Narrative Recap
To own Brown & Brown, you need to believe its mix of acquisitions, program underwriting and AI led tools like COMPASS can keep operations resilient even if industry growth is modest. The near term swing factor sits with execution on Accession integration and AI deployment, set against pressure from softer CAT property pricing and producer churn.
The biggest current risk is that weaker CAT related premiums and any further producer losses offset efficiency gains from COMPASS and other automation. The latest dividend increase signals confidence but does not materially change the operating story, which is still largely about steady integration, cash generation and cost discipline.
The COMPASS rollout is the announcement that most directly connects to Brown & Brown’s current catalysts. Management is already pointing to concrete customer outcomes in Employee Benefits and Property & Casualty, alongside plans to extend AI powered tools to thousands of teammates by the end of 2026 and broaden customer solutions in 2027.
For you, the question is how effectively Brown & Brown embeds COMPASS into day to day workflows to support organic growth and margin resilience while dealing with softer CAT pricing and producer turnover. Execution risk is real, but the product launch sits squarely on the operational levers analysts already focus on, including automation, underwriting programs and capital deployment.
How COMPASS Sits Inside The Current Brown & Brown Forecasts
Brown & Brown's current analyst narrative already bakes in moderate expectations, with revenue modeled to rise by 5.7% a year over the next 3 years while profit margins ease from 17.9% today to 16.4% by 2029. Earnings are projected to move from US$1.2b today to US$1.3b by 2029, an increase of about US$0.1b. This anchors consensus earnings per share estimates of US$4.01 and a P/E multiple of 22.5x on those future results. On the top line, the same view assumes Brown & Brown can reach about US$7.9b of revenue by 2029. Analysts are tying that level to the current price target range and to the idea that COMPASS, Accession and underwriting programs together can support that outcome.
Brown & Brown's narrative projects revenues of about US$7.9b and earnings of roughly US$1.3b by 2029. This rests on 5.7% yearly revenue growth and an earnings increase of about US$0.1b from US$1.2b today.
Uncover why Brown & Brown's fair value aligns with its current price.
Exploring Other Perspectives
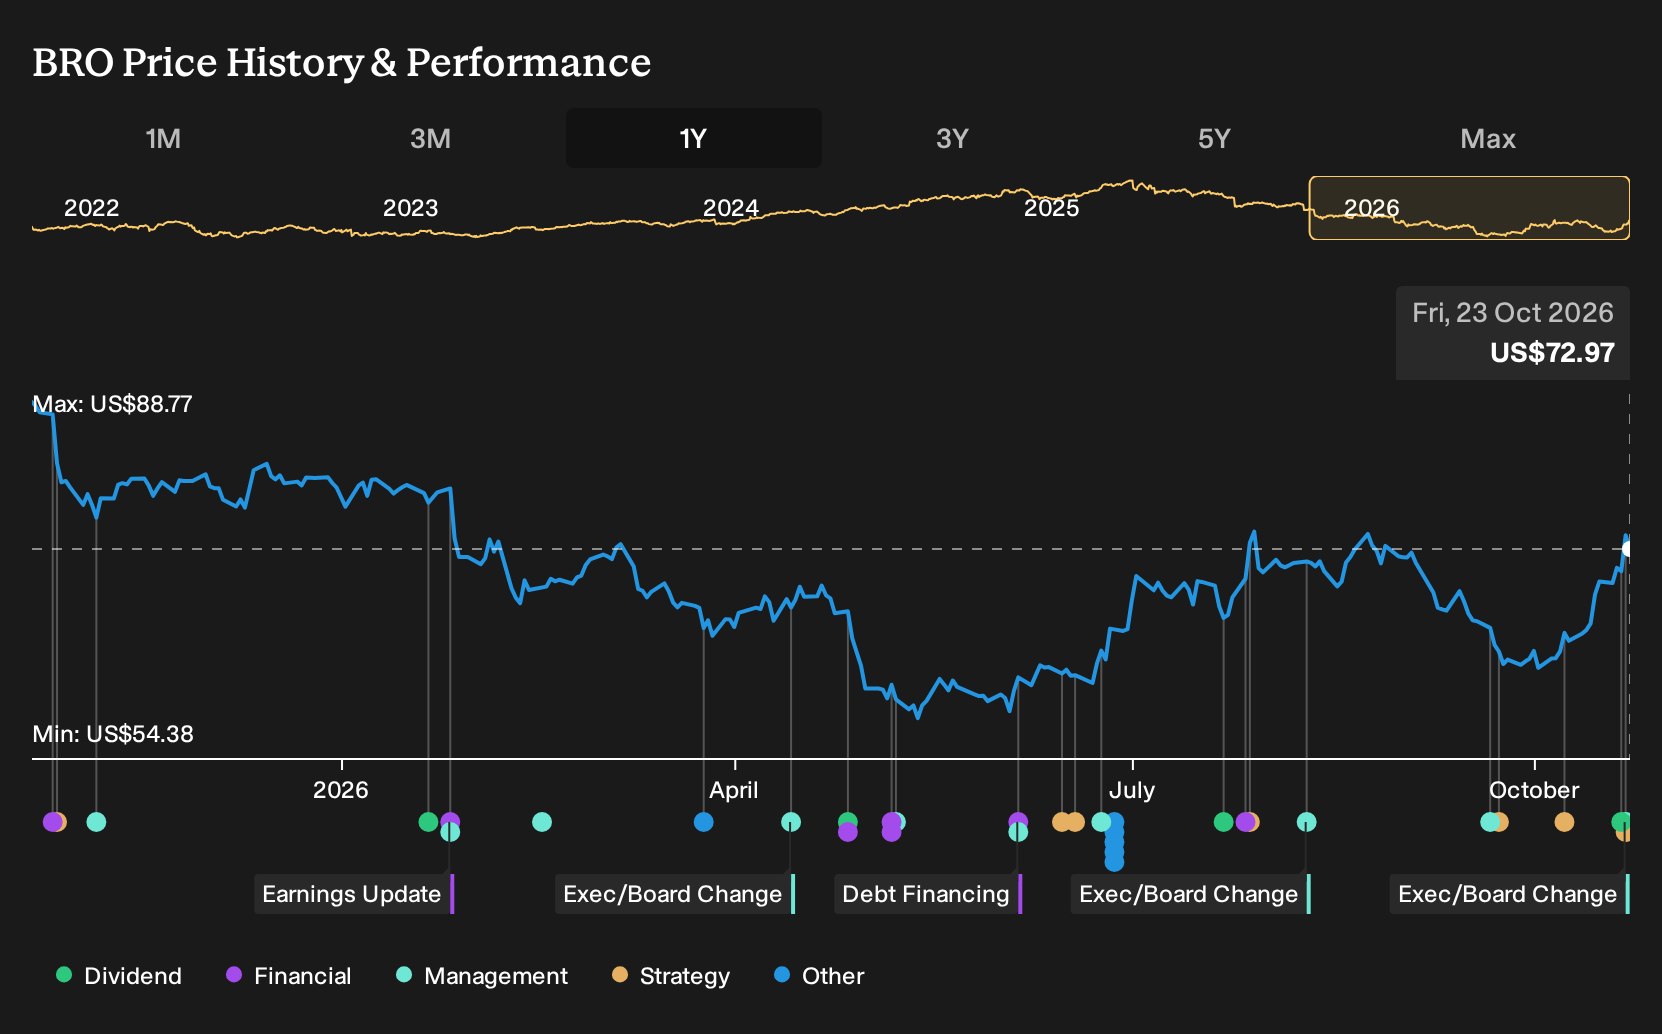
You are looking at only 2 fair value estimates from the Simply Wall St Community, with views spanning roughly US$74.75 to about US$96.33 per share. That small sample still shows wide disagreement. When you layer on COMPASS, producer turnover and softer CAT related pricing, Brown & Brown’s future feels open to multiple readings.
Explore another Brown & Brown fair value estimate, including one that suggests as much as 32% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Brown & Brown research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Brown & Brown. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brown & Brown's overall financial health at a glance.
Looking for more Brown & Brown style ideas?
If the Brown & Brown story has you thinking about how to balance risk, income and quality, it can help to scan a wider field of companies built on similar foundations of cash flow, balance sheet strength and disciplined underwriting.
- For investors who want quality and value in the same package, consider starting with a curated list of companies trading at appealing valuations through 29 high quality undervalued stocks.
- If portfolio resilience matters most to you, focus on businesses with robust finances and low risk scores by scanning the 30 resilient stocks with low risk scores.
- Those hunting for income ideas can zero in on higher yielding, more resilient payers by reviewing the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com