
Tesla Stock Buzz Puts Satellite Connectivity Shares In Focus
Speculation around a possible Tesla and SpaceX tie-up by 2027, huge revenue projections for SpaceX, and talk of a new “fifth hyperscaler” are pulling satellite connectivity into the spotlight again. If capital starts to re-rate anything linked to AI compute, orbital networks, or defense communications, you will not want to be catching up from behind. This article breaks down 3 stocks exposed to this story and how the news may matter for each one.
The three stocks covered below are just a sample, and the full screen surfaced 62 more listed satellite connectivity and defense-linked communications providers with equally compelling stories that are not discussed here. If you want to identify and analyze the highest conviction prospects in this space, head straight to the Public Satellite Connectivity and Defense-Linked Communications Providers screener.
WNC (TWSE:6285)
Overview: WNC Corporation designs and manufactures satellite, mobile, and portable communication hardware that underpins global satcom, broadband, automotive, and smart home connectivity.
Operations: WNC generates NT$122,987.705 million from wireless communications equipment, with revenue concentrated across America, Asia, and Europe in varying scales.
Market Cap: NT$111.24b
Satellite communication gear, antennas, and network access products put WNC in the path of any ramp in orbital connectivity and Starlink-to-vehicle demand. The stock is tied to hardware that could benefit if a Tesla and SpaceX style push makes satellite links standard in cars, homes, and routers, although much depends on how one unseen pressure shapes future pricing power.
If that pressure on pricing power is what worries you most, start with the 5 key rewards and 3 important warning signs (1 is major!) to see how WNC’s upside and pressure points compare.

Electro Optic Systems Holdings (ASX:EOS)
Overview: Electro Optic Systems Holdings develops laser satellite tracking, space-domain awareness, and advanced defense systems that plug directly into orbital communications infrastructure.
Operations: Electro Optic Systems Holdings generates about A$241 million from Defence and A$12 million from Space, highlighting a defence-led revenue base.
Market Cap: A$1.88b
Electro Optic Systems Holdings matters for this theme because its sensors, lasers, and satellite tracking hardware help customers see and secure crowded orbital highways as satellite constellations scale.
"Market optimism may be pricing in a prolonged period of elevated defense spending and geopolitical tensions, anticipating sustained contract wins and revenue growth for EOS. If these trends reverse because of arms control or shifting government priorities, revenue expectations could be at risk."
The real swing factor for Electro Optic Systems Holdings is how a single shift in long-term defence space budgets reshapes future contract economics.
That contract swing is the hinge. Read the full narrative for Electro Optic Systems Holdings to see how Electro Optic Systems Holdings could gain if defence and space priorities keep accelerating.

Singapore Technologies Engineering (SGX:S63)
Overview: Singapore Technologies Engineering is a global defence, aerospace, and urban solutions group that builds communications, C4ISR, and satcom infrastructure linking secure networks with space-enabled systems.
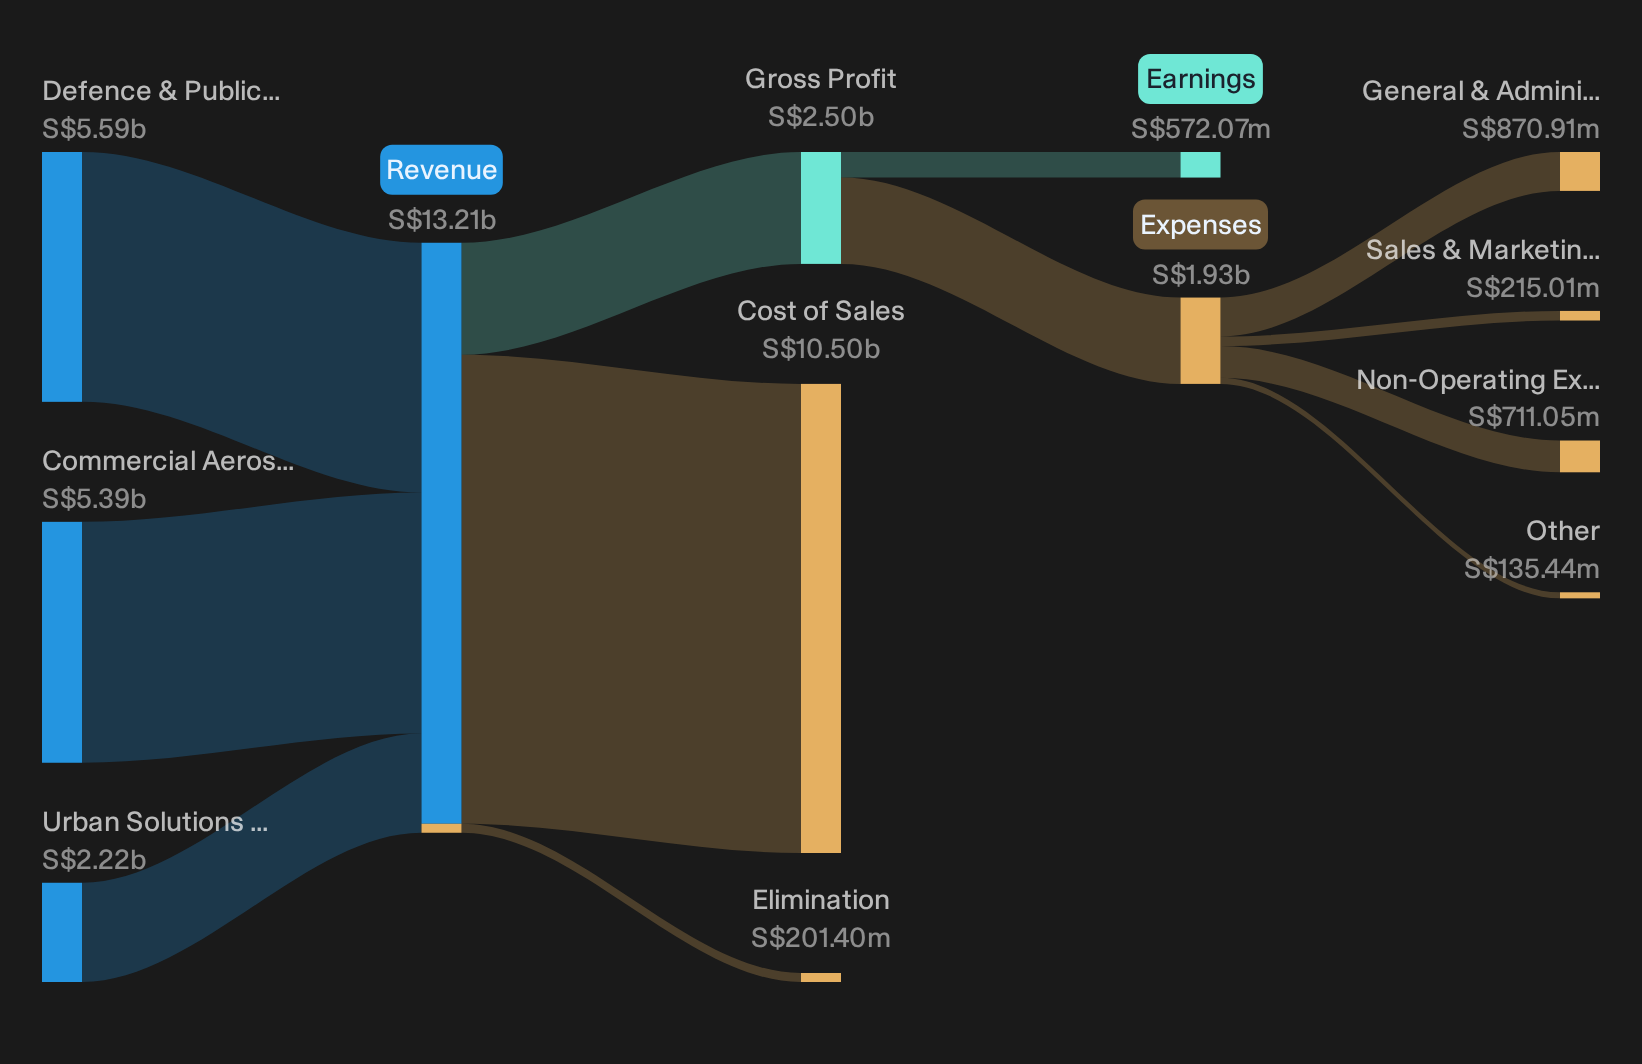
Operations: Singapore Technologies Engineering generates about S$5.6b from Defence & Public Security, S$5.4b from Commercial Aerospace, and S$2.2b from Urban Solutions & Satcom, primarily across Asia and the U.S.
Market Cap: S$31.82b
Singapore Technologies Engineering plugs directly into the screener theme because its C4ISR and satcom platforms form part of the communications backbone that future AI heavy constellations and defence networks may rely on.
"The company has a robust order book of $28.5 billion, providing revenue visibility with $8.8 billion expected for delivery in 2025."
The question for investors is how unresolved cost and leverage pressure ultimately shapes the profitability of that pipeline.
That pressure point is exactly where things get interesting, and the full narrative for Singapore Technologies Engineering shows how Singapore Technologies Engineering could convert that order book into potential long term value.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time momentum shows on every chart, the cleanest entries are already gone. Scan these curated lists while it still matters and aim to act early.
- Identify cash generative compounders by running the 194 high quality undervalued stocks before valuations are influenced by momentum-focused investors.
- Explore the infrastructure backbone of AI by scanning the 55 AI infrastructure stocks while many investors are still focused on headline chip stocks.
- Focus on resilient cash flow payers by checking the 226 dividend fortresses before yields change and entry yields decline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com