
Everforth (EFOR) Faces A 33% Premium As Fresh DCF Debate Returns
Why a fresh DCF is back in focus for Everforth
A renewed discounted cash flow review has pushed Everforth (EFOR) back into the spotlight, as investors weigh long term cash generation assumptions against a share price shaped by mixed expectations.
Recent trading has flipped the tone around Everforth. The 90 day share price return of 102.18% and 30 day gain of 31.61% point to strong short term momentum, even though the year to date share price return is down 6.58% and the 5 year total shareholder return is down 63.57%. This keeps the fresh DCF work front and centre for anyone asking whether the current US$43.59 quote lines up with the cash the business is expected to produce.
Scan how Everforth’s renewed DCF debate compares with other potential cash flow opportunities by reviewing the hand picked 29 high quality undervalued stocks in similar sectors.
Everforth has already doubled over 90 days, yet its DCF work still points to a gap between price and implied cash flows. Is most of the rerating done, or is there more runway left?
Most Popular Narrative: 33% Overvalued
Everforth closed at $43.59, while the most followed narrative pegs fair value closer to $32.67 using a 12.42% discount rate, so the current quote assumes a lot is already going right.
The main thing that has to go right is that Everforth turns its heavier consulting mix, partner led go to market and structural cost programs into sustained revenue growth and higher margins rather than one off quarterly beats.
The current valuation implies Everforth’s share price already reflects successful delivery on its AI and consulting led transformation and margin targets, so the stock leaves limited room for disappointment and this narrative views it as overvalued and bearish.
See why 3 investors see Everforth as 33% overvalued.
Result: Fair Value of $32.67 (OVERVALUED)
Still, if Everforth’s federal backlog converts into steadier awards and commercial consulting bookings stay firm, that could challenge a bearish DCF-driven view.
Find out about the key risks to this Everforth narrative.
Another View: Everforth Through The P/E Lens
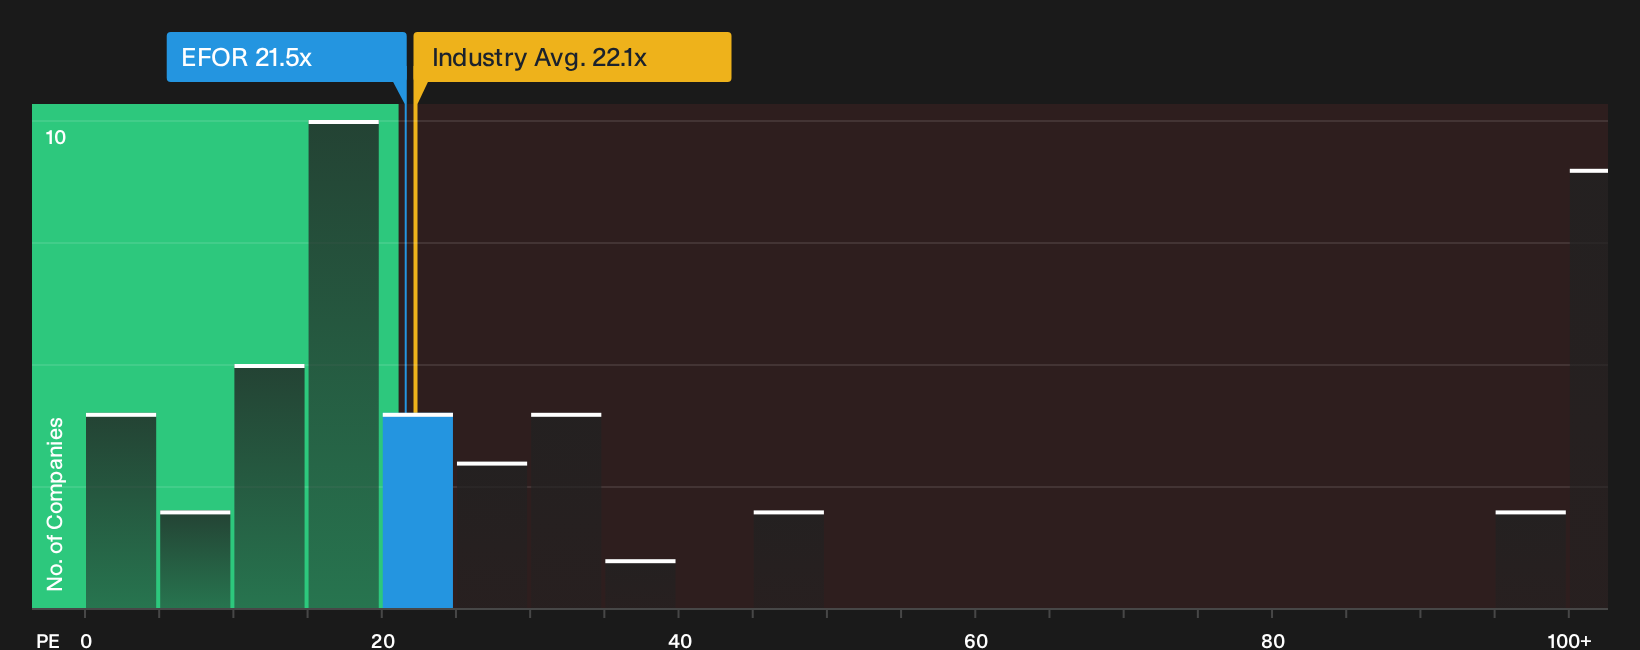
The DCF work presents Everforth as undervalued, yet the earnings multiple suggests a more measured signal. The stock trades on a P/E of 21.5x, which is slightly below both the US IT industry at 22.7x and the peer average at 22.3x, while the fair ratio is estimated at 37.2x. That gap may indicate either a margin of safety or a market that is unconvinced earnings quality and growth will align. Which interpretation do you think is closer to reality?
To pressure test that P/E view against the detailed earnings and cash flow assumptions, it helps to see how the numbers are built from the ground up through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment runs through every part of the Everforth story. Move fast, review the full data for yourself, and weigh both sides with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Everforth?
If Everforth has sharpened your thinking, do not stop here. Broader context often comes from comparing it with other businesses that share some financial traits.
- Target potential mispricings by reviewing the 29 high quality undervalued stocks that combine solid financials with prices that may not fully reflect their fundamentals.
- Prioritize resilience by scanning a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses with stronger financial footing.
- Hunt for fresh opportunities by checking a 21 high quality undiscovered gems that most investors are not watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com