
Is Softcat (LSE:SCT) Undervalued Following Strong Full Year Earnings?
Softcat’s latest earnings spark fresh interest
Softcat (LSE:SCT) moved back into focus after full year results to July 31, 2026, with sales of £1,975.1m and net income of £150.3m, followed by a dedicated earnings call.
Softcat’s share price has eased in recent months, with a 30-day share price return of down 7.04% and a 90-day move of down 13.83%, even as the latest full year update and October earnings call kept the story in front of investors. At £16.63, the stock still carries a 21.03% year to date share price return and a 46.65% total shareholder return over three years. This points to longer term momentum that contrasts with the more cautious short term reaction to recent news.
Extend that Softcat thesis by scanning a hand picked group of resilient IT and software players with strong fundamentals through our list of solid balance sheet and fundamentals (9 results).
Softcat now trades at a discount to analyst price targets, even as the valuation sits slightly above one estimate of fair value. Is the recent pullback a sign to be cautious, or could it represent an opening for patient buyers?
Most Popular Narrative: 23% Undervalued
Softcat’s most followed valuation story pegs fair value at £21.51, comfortably above the latest £16.63 close. This puts the recent share pullback into clearer context for anyone weighing upside against risk.
The analysts have a consensus price target of £21.51 for Softcat based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of £25.0, and the most bearish reporting a price target of just £17.0.
See why 16 investors see Softcat as 23% undervalued.
Result: Fair Value of £21.51 (UNDERVALUED)
Still, the biggest watchpoints are GDT’s concentrated customer base and the sizeable system implementation spend. Either of these factors could blunt the bullish Softcat narrative.
Find out about the key risks to this Softcat narrative.
Another View: Softcat through the earnings lens
A second yardstick does not rely on analyst targets at all. The SWS DCF model puts Softcat’s value at about £16.06 per share, slightly below the current £16.63 price. That points to a stock trading a little above its cash flow value. So which story earns your trust?
For readers who want to see how this cash flow view is built line by line, the full workings of the SWS DCF model are available through Look into how the SWS DCF model arrives at its fair value..
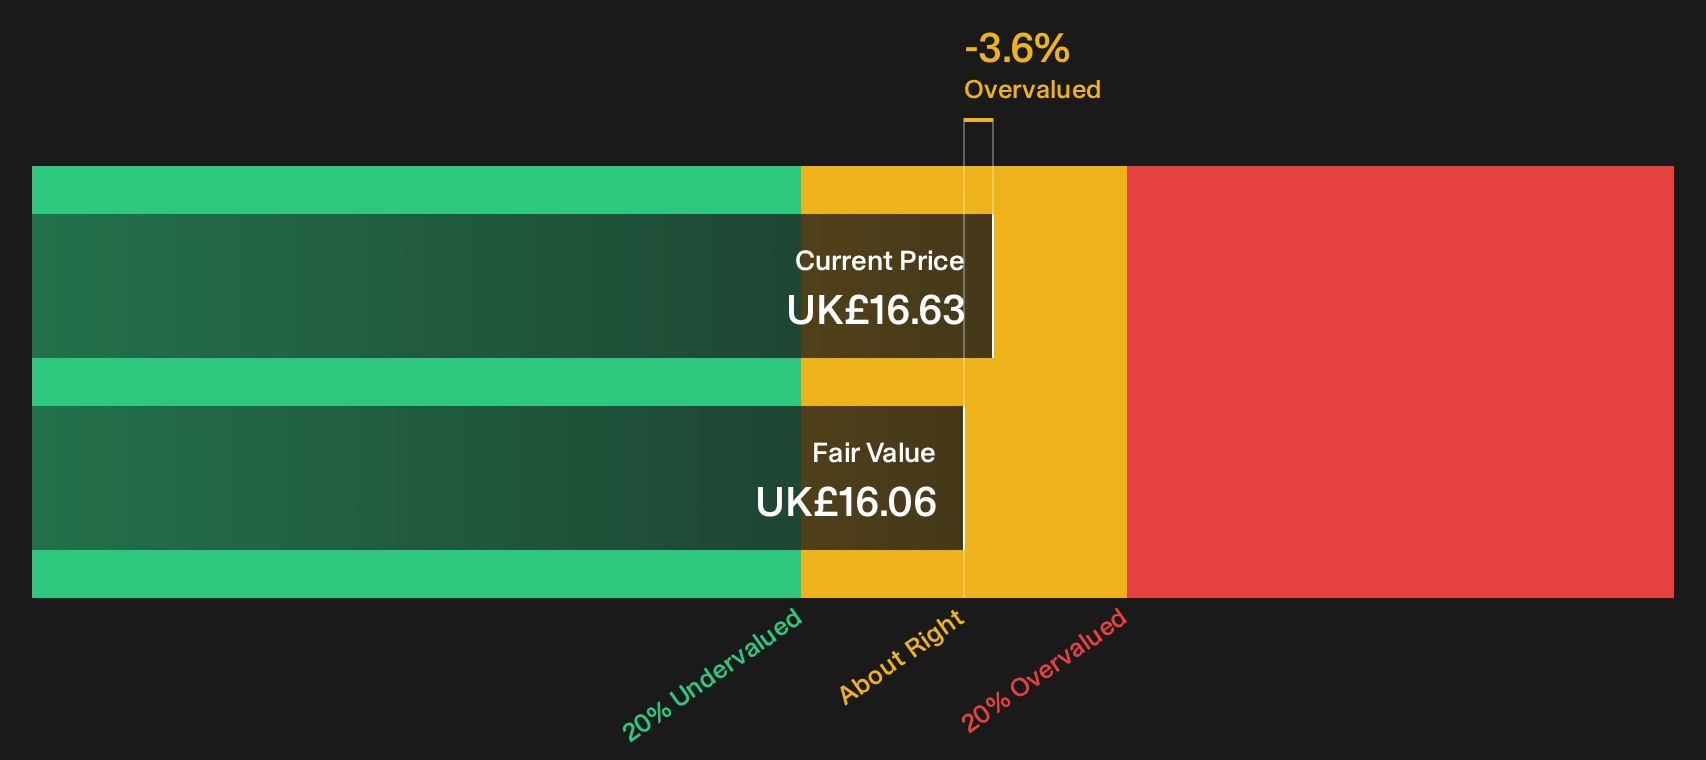
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Softcat for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Softcat’s value story make this a moment to look at the data first and the headlines second. Then move quickly to weigh the upside and the risks for yourself using the 4 key rewards.
Looking for more investment ideas beyond Softcat?
If Softcat has sharpened your thinking, do not stop here. Broaden your watchlist with other clear opportunities that your future self may be glad you checked.
- Target higher potential by scanning for quality companies trading below their assessed worth through the 8 high quality undervalued stocks.
- Lock in potential income streams by reviewing businesses that appear capable of supporting strong payouts using the 5 dividend fortresses.
- Dial down portfolio stress by filtering for sturdier balance sheets and cleaner fundamentals via the 4 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com