
Is Perimeter Solutions (PRM) A Bargain After Raised Earnings Forecasts?
Perimeter Solutions (PRM) is back on investor radar after analysts lifted earnings projections ahead of the next report, tying those expectations to expanded long-term fire management frameworks and broader international demand for its fire safety products.
Perimeter Solutions shares trade at US$27.80 after a 2.39% 1 day share price gain and a 4.75% 7 day share price return. However, the stock is still down 4.50% over 30 days and 16.57% over 90 days. Its total shareholder return of 26.08% over one year and a very large 3 year gain of almost 8x point to long term momentum that contrasts with the recent pullback as investors reassess both growth potential and risk around the upgraded earnings outlook.
Capitalize on the renewed focus on Perimeter Solutions by lining up the next potential movers with a curated list of 29 high quality undervalued stocks.Perimeter Solutions now sits at the intersection of a momentum story built on long term frameworks and a sharp recent pullback that exposes execution risk. Do the current numbers lean more toward the bull case or the bear argument on valuation?
Most Popular Narrative: 33% Undervalued
Perimeter Solutions last closed at $27.80, while the most followed narrative anchors fair value at $41.50. The current pullback sits against a valuation framework that leans on long dated contracts, margin repair and disciplined capital allocation.
Expansion of long-term fire management frameworks, such as the U.S. Wildland Fire Service and aggressive initial attack policies, supports more consistent use of aerial retardant and services, which can help stabilize Fire Safety revenue and EBITDA over time.
See why 3 investors see Perimeter Solutions as 33% undervalued.
Result: Fair Value of $41.50 (UNDERVALUED)
Still, the Perimeter Solutions narrative depends heavily on long term fire management contracts and on the successful integration of deals like MMT and IMS, where setbacks could quickly challenge today’s valuation story.
Find out about the key risks to this Perimeter Solutions narrative.
Another View: What Multiples Say About Perimeter Solutions
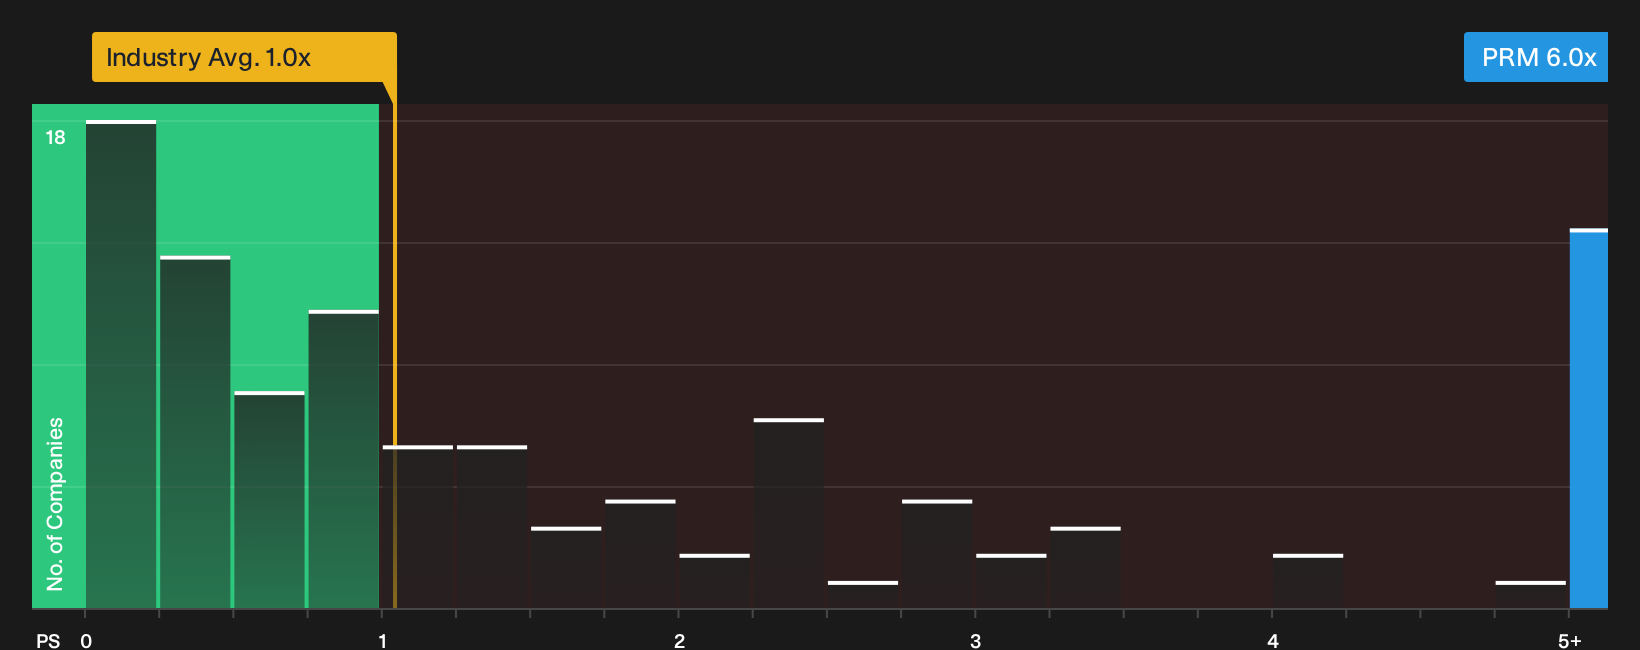
Perimeter Solutions screens as undervalued on analyst targets and fair value estimates, yet its current P/S ratio of 6x sits far above the US Chemicals industry at 1x and a fair ratio of 4.1x. That gap points to meaningful valuation risk if sentiment or growth expectations cool from here.
For a closer look at how this pricing stacks up against peers and the fair ratio the market could drift toward over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the Perimeter Solutions story so far feels split between opportunity and valuation risk, this may be a moment to evaluate the numbers yourself and consider your next steps before sentiment shifts again. To see what has investors optimistic, review the 3 key rewards.
Looking for more investment ideas beyond Perimeter Solutions?
Use this pullback window to widen your watchlist with fresh opportunities that fit your style, before other investors start paying attention to the same setups.
- Target quality at a discount by reviewing the 29 high quality undervalued stocks that line up stronger fundamentals with appealing entry prices.
- Strengthen portfolio resilience by scanning the list of solid balance sheet and fundamentals (24 results) and focus on companies with healthier financial foundations.
- Hunt for underfollowed potential by checking the 21 high quality undiscovered gems before they attract broader market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com