
3 UK AI Stocks Backed By Government Cybersecurity Spending
AI security is moving from concept to concrete spending plans, with the UK government putting hundreds of millions of pounds into labs, testing institutes and cyber defence projects. That shift could reshape demand for everything from cloud infrastructure to specialised cybersecurity services. This article picks out 3 UK stocks exposed to that wave of funding and policy focus, and explains why each might deserve a closer look now.
The three stocks in this article are just a starter set, and the full screen surfaced 11 more UK AI and cybersecurity infrastructure providers with equally compelling stories that are not covered here. To size up that broader field and quickly identify which ones deserve a place on your watchlist, head straight to the UK AI and Cybersecurity Infrastructure Providers screener
Cerillion (AIM:CER)
Cerillion plugs into the UK AI and cybersecurity infrastructure story through its telecom billing and CRM software, which underpins how network operators package and charge for advanced digital and AI driven services that governments and enterprises increasingly rely on.
Cerillion generates £22.6 million from Software, £17.8 million from Services and £2 million from Other activity, with a market value of about £207 million.
Cerillion provides exposure to that trend through the plumbing of telecom and digital services, where long contracts and sticky systems can matter as much as raw AI capabilities.
"The record new orders of around £40 million for the half year and a back order of £82 million indicate strong demand for Cerillion’s product-centric model. This can support future revenue visibility and earnings as this work is delivered and recognized."
What happens to Cerillion’s payout and reinvestment capacity depends on how one relatively quiet pressure around earnings quality ultimately plays out.
To see how that pressure could accelerate or stall the story, read the full narrative for Cerillion for a full breakdown of earnings quality, contract depth and reinvestment levers.

Vodafone Group (LSE:VOD)
Vodafone Group underpins much of the secure connectivity that UK AI, cloud and cyber defence projects rely on. Its push into IoT, cloud, edge and security services sits on top of a large telecom footprint that policymakers and enterprises already use at scale.
Vodafone Group runs mobile, fixed, IoT, cloud and digital payments services across Europe, Africa and Turkey, generating about €12.1b from Germany, €9.2b from the UK, €8.4b from Africa, €5.7b from other European operations and €3.4b from Turkey, with a market value near £27.2b.
"The integration of VodafoneThree in the U.K., with increased annual cost and CapEx synergy ambitions of £800 million by FY2030 and a path to £1b by FY2032, is expected to improve net margins and free cash flow as duplicate network and operating costs are removed."
What happens if one pressure on Vodafone Group’s ability to keep funding secure, high capacity networks shifts even slightly in the wrong direction?
If that pressure matters to your thesis, the full narrative for Vodafone Group shows how Vodafone Group’s merger economics, balance sheet and capital demands might be separating beneath the headline synergies.

TT Electronics (LSE:TTG)
TT Electronics builds specialised power, sensor and microelectronics hardware that sits close to the front line of secure aerospace and defence systems, making it a practical way to tap into the UK government’s push on resilient AI and cyber infrastructure.
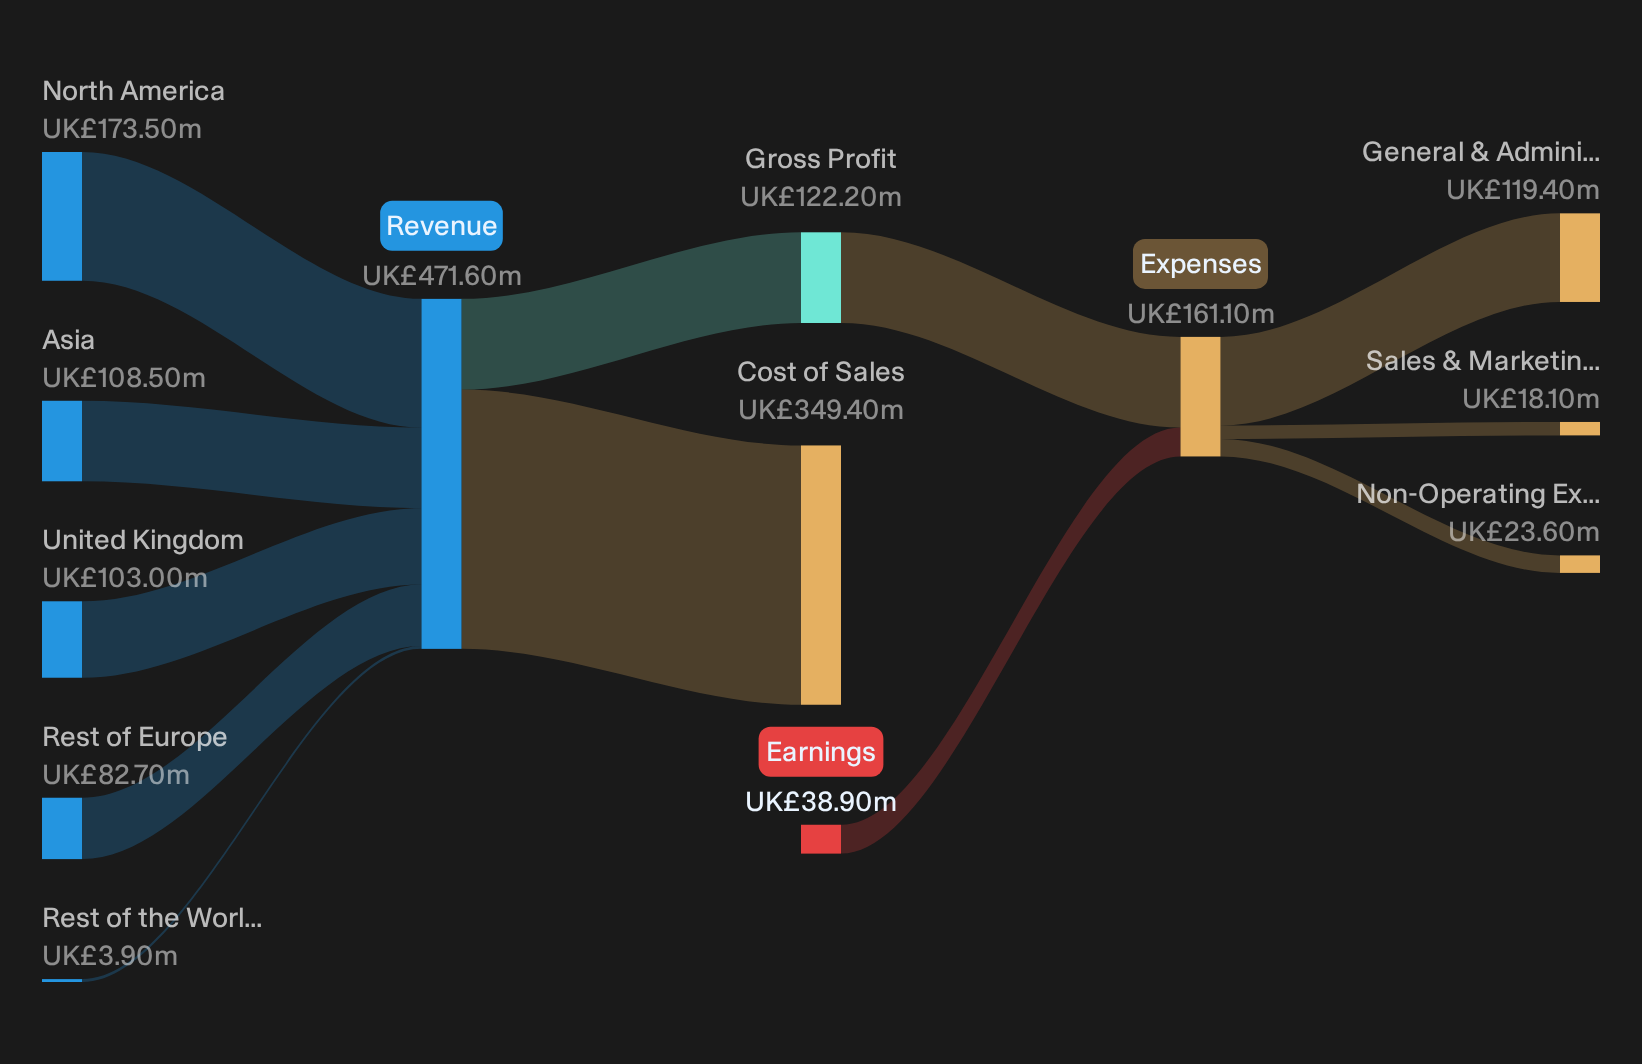
TT Electronics designs advanced electronics for healthcare, aerospace, defence and industrial uses, with segment revenue of £471.6 million and a market value of about £331 million.
"Rising global defense and civil aviation spending, supported by multi year program awards such as the recent contract with Kongsberg, is expected to sustain high value, long duration orders and support continued revenue growth and operating margin expansion."
What happens to TT Electronics’ margin trajectory depends on how one quiet constraint on its ability to convert that pipeline into steady earnings ultimately resolves.
To see how that constraint could still turn into an advantage for TT Electronics, read the full narrative for TT Electronics and identify where execution risk and earnings momentum may be decoupling.
Seeking Alternatives Before The Crowd?
Fresh opportunities can move quickly. By the time many investors notice a breakout, the early momentum may have already passed. Scan these focused shortlists while it matters and consider acting early.
- Target sturdier income streams by reviewing companies in the 5 dividend fortresses before yields compress and more investors pursue the same payouts.
- Look for potential long-term compounding by scanning the curated 8 high quality undervalued stocks while possible mispricings may still be less widely followed and expectations remain limited.
- Explore the next wave of automation by checking the focused 95 robotics and automation stocks before changes in adoption are fully reflected in these businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com