
Raised Guidance Just Shift UnitedHealth Group Stock Narrative?
- UnitedHealth Group reported third quarter 2026 revenue of US$112,694 million with net income of US$4,110 million and diluted EPS of US$4.56, then raised full year 2026 net earnings guidance to more than US$17,650 million and at least US$19.50 in diluted EPS.
- The company has also completed a long running buyback program totaling 736,529,794 shares for US$83,638.51 million, which materially reduced the share count and increases the importance of execution on earnings quality and cash generation for existing investors.
- We will now look at how UnitedHealth Group's higher 2026 earnings guidance could reshape the investment narrative that was built before this update.
Compare how UnitedHealth Group's massive buyback and higher earnings guidance stack up against other potential opportunities by scanning a curated set of 29 high quality undervalued stocks.
UnitedHealth Group Investment Narrative Recap
To own UnitedHealth Group, you need to believe it can manage medical cost pressure while steadily improving earnings quality across Medicare, Medicaid and commercial benefits, and keep Optum on track. The raised 2026 net earnings guidance above US$17,650 million and at least US$19.50 in diluted EPS indicates management confidence in that execution.
The short term catalyst remains margin recovery as higher acuity Medicare members are moved into clinical and value based programs and AI driven cost initiatives scale. The biggest risk still sits with elevated medical trends, Medicaid margin pressure and legal or regulatory outcomes, and this latest update does not remove those threats.
The most relevant update for you is the higher 2026 earnings outlook, coming on top of Q3 net income of US$4,110 million and diluted EPS of US$4.56 from continuing operations. That guidance frames how UnitedHealth Group expects its operations and cost controls to hold up against medical inflation and reimbursement dynamics.
Stronger year to date profitability and the guidance lift put more weight on execution in OptumHealth value based care programs and the AI program that targets general and administrative savings. Any stumble on medical cost trend, Medicaid reimbursement adequacy or ongoing shareholder lawsuits could weaken that earnings path and soften the catalyst investors are focused on.
UnitedHealth Group's narrative projects US$502.0b revenue and US$23.5b earnings by 2029. This assumes 3.7% yearly revenue growth and a US$9.4b earnings increase from US$14.1b today.
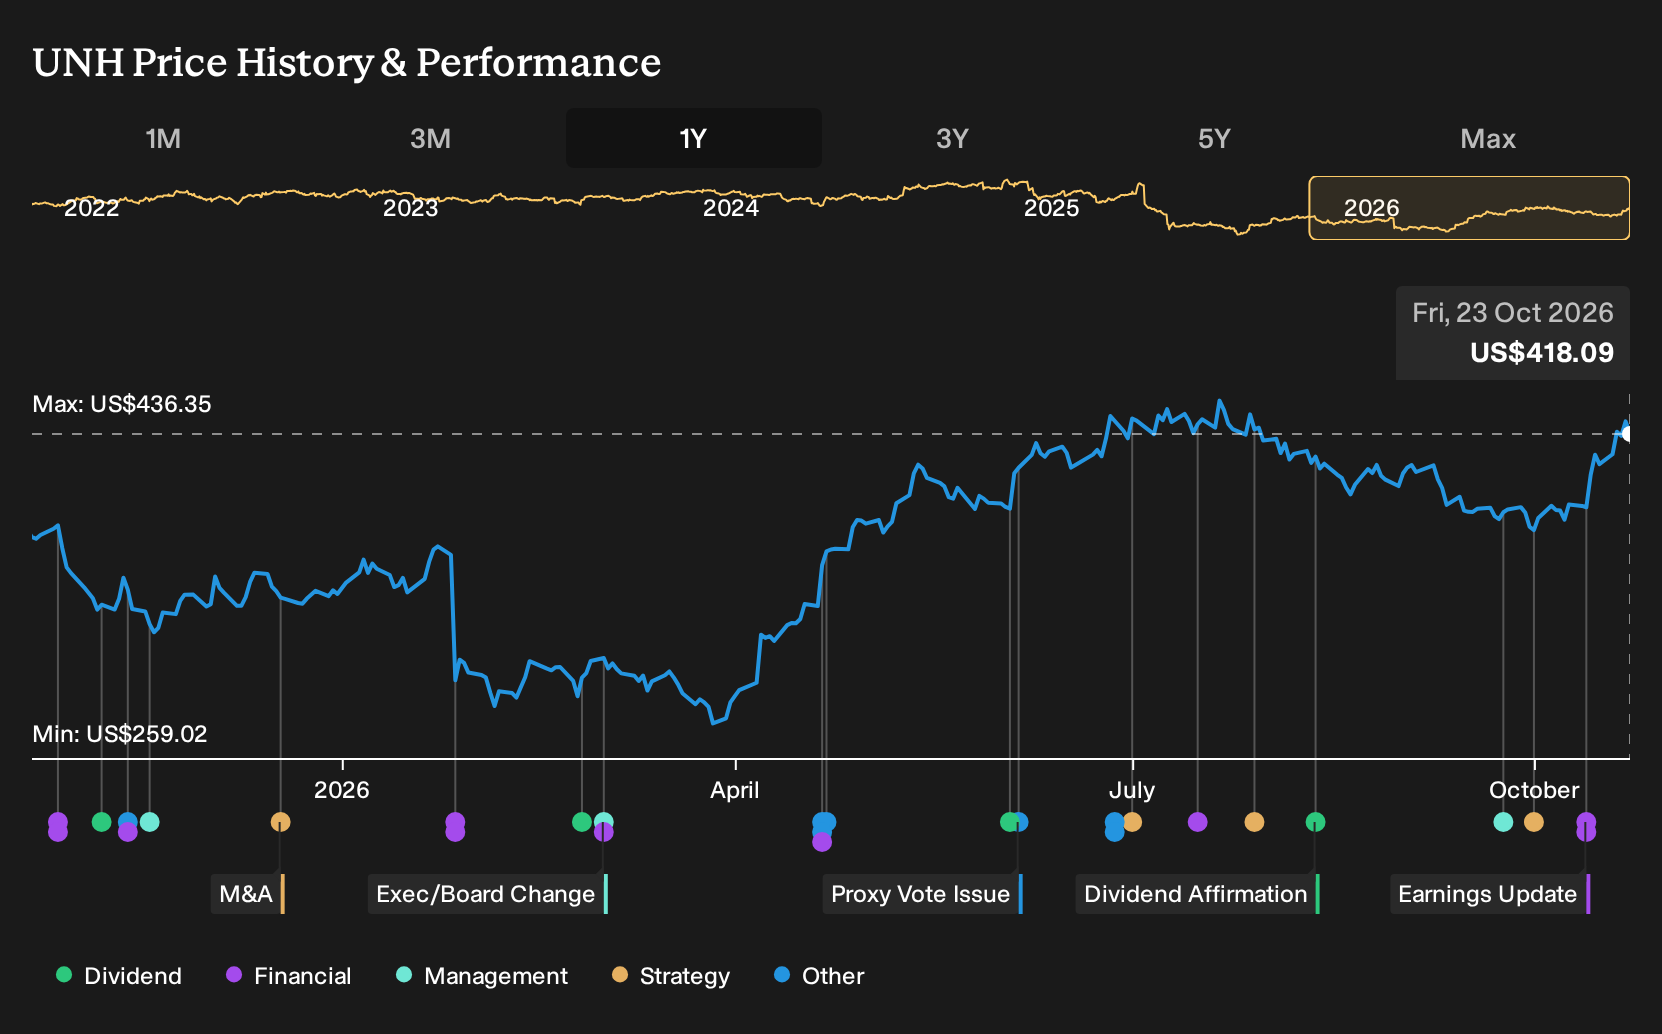
Uncover why UnitedHealth Group's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on tax risk at UnitedHealth Group rather than medical cost trends. The most cautious analysts were working off revenue of about US$491.5b and earnings of US$23.7b by 2029, yet still applied a lower 18.6x P/E. That is a more restrained story, and the new buyback and guidance could shift it.
Explore 10 other UnitedHealth Group fair value estimates, including one that suggests up to 6% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your UnitedHealth Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UnitedHealth Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UnitedHealth Group's overall financial health at a glance.
Looking for more investment ideas beyond UnitedHealth Group?
Once you have a view on UnitedHealth Group, it can help to compare it with a wider watchlist so you can see how the risk, balance sheet strength and return profile stack up against other listed businesses.
- If capital preservation sits near the top of your priorities, start by scanning a focused set of 30 resilient stocks with low risk scores that score well on resilience and downside control.
- For investors who care most about balance sheet strength and clean fundamentals, filter the market using a curated list of solid balance sheet and fundamentals (24 results) to see which companies clear your quality bar.
- When you want to broaden your opportunity set beyond well known large caps, use a targeted group of 21 high quality undiscovered gems to surface lesser known businesses with stronger underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com