
Can SSAB (OM:SSAB A) Justify Its Valuation As It Starts Its SEK 3.3b Quenching Line?
SSAB (OM:SSAB A) is back in focus after breaking ground on a new quenching line in Oxelösund, a SEK 3.3b project aimed at expanding high-strength wear and protection steel capacity.
Recent trading has been choppy for SSAB, with the share price down 5.1% over the past week and 6.0% over the past month, even though the year to date share price return is 32.6% and the 1 year total shareholder return is 65.4%.
Scan other premium steel and materials players that could benefit from similar capacity shifts by checking the hand picked list of solid balance sheet and fundamentals (207 results) in the same sector sweet spot.
The share price has already moved significantly over the past year while SSAB commits SEK 3.3b to premium capacity. Do these expectations still leave enough upside to justify fresh risk, or has most of the payoff been pulled forward?
Most Popular Narrative: 24% Overvalued
On the most followed narrative, SSAB is valued at a fair value of SEK80 per share compared with the last close at SEK97.86, which points to a meaningful gap between narrative assumptions and where the market currently prices the stock.
Sweden's traditional steel mill, SSAB is in an enviable position relative to its peers, for three reasons.
1) Its plants are strategically well placed on both sides of the Atlantic; thus, it will not be caught between millstones when the US and the EU get entangled in a trade war centred on steel and aluminium. Indeed, the company is set to downright profit from it, when its markets both in the US and the EU will get protection from Chinese and Korean competition.
See why 64 investors see SSAB as 24% overvalued.
That valuation, according to PittTheYounger, uses a 9% discount rate and reflects both the perceived benefits from EU protection on Chinese steel and the potential drag from macro shocks such as higher energy costs, yet still comes out about SEK18 below where SSAB trades today.
Result: Fair Value of SEK80 (OVERVALUED)
Still, SSAB’s thesis runs into trouble if energy prices stay elevated for longer or if EU protection on Chinese steel softens faster than investors expect.
Find out about the key risks to this SSAB narrative.
Another View: SSAB on Earnings Ratios
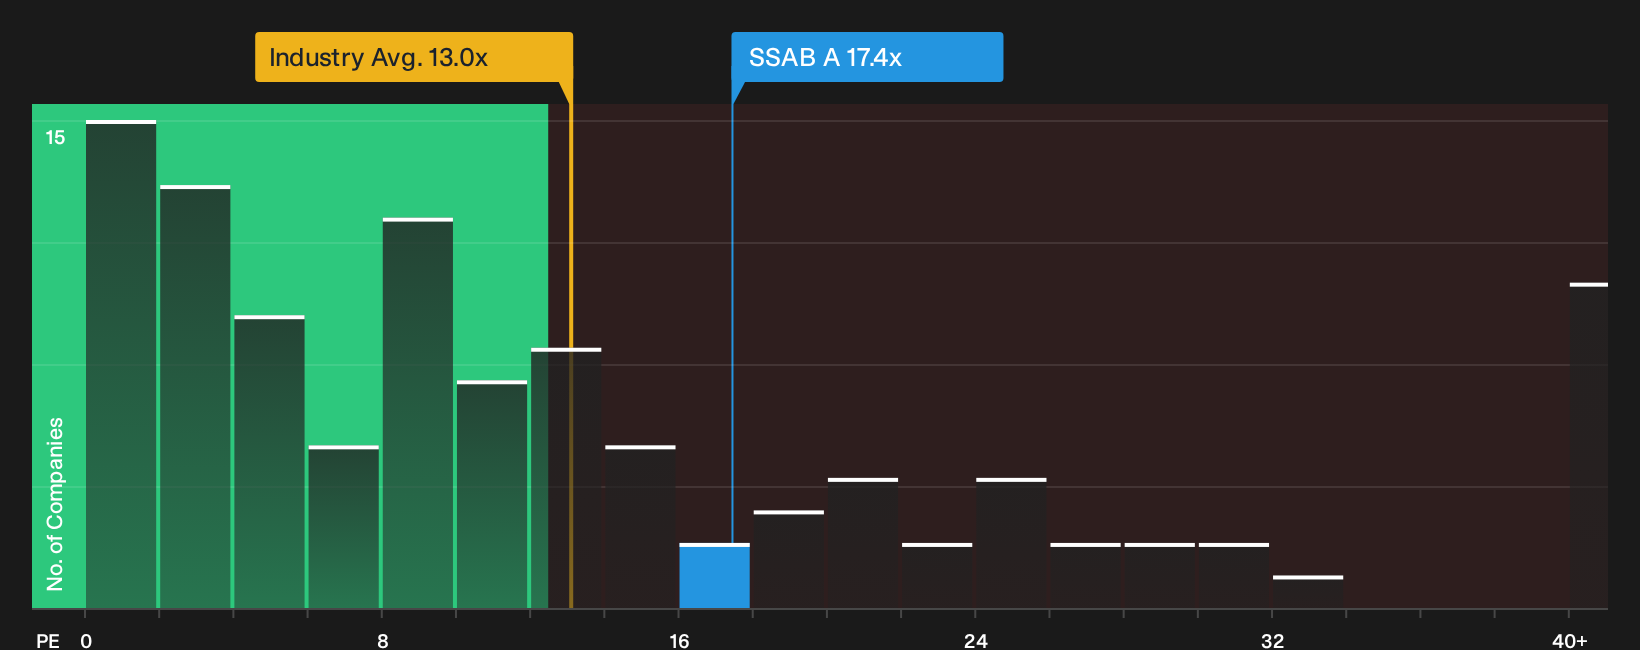
A second lens on SSAB uses its P/E. The stock trades on 17.4x earnings, below the Swedish market at 18.7x and well under a peer average of 27.7x, while the fair ratio sits higher at 25.6x. That mix points to valuation risk running both ways. Which signal do you trust?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the SSAB story today. If you want to move fast and judge the balance of risk and reward for yourself, start with the 2 key rewards and 1 important warning sign.
Looking for more SSAB investment ideas?
If you want to stay ahead of the next move instead of reacting late, use the Simply Wall Street Screener to surface fresh, data driven opportunities now.
- Target value with quality at the core by scanning our curated 194 high quality undervalued stocks that line up solid fundamentals with potentially attractive pricing.
- Lock in potential income streams by reviewing the 229 dividend fortresses that combine higher yields with balance sheets you can actually assess.
- Protect your downside first by focusing on our 221 resilient stocks with low risk scores that screen for resilient financial profiles before upside stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com