
SLM Stock What Changed After Earnings Guidance Cut
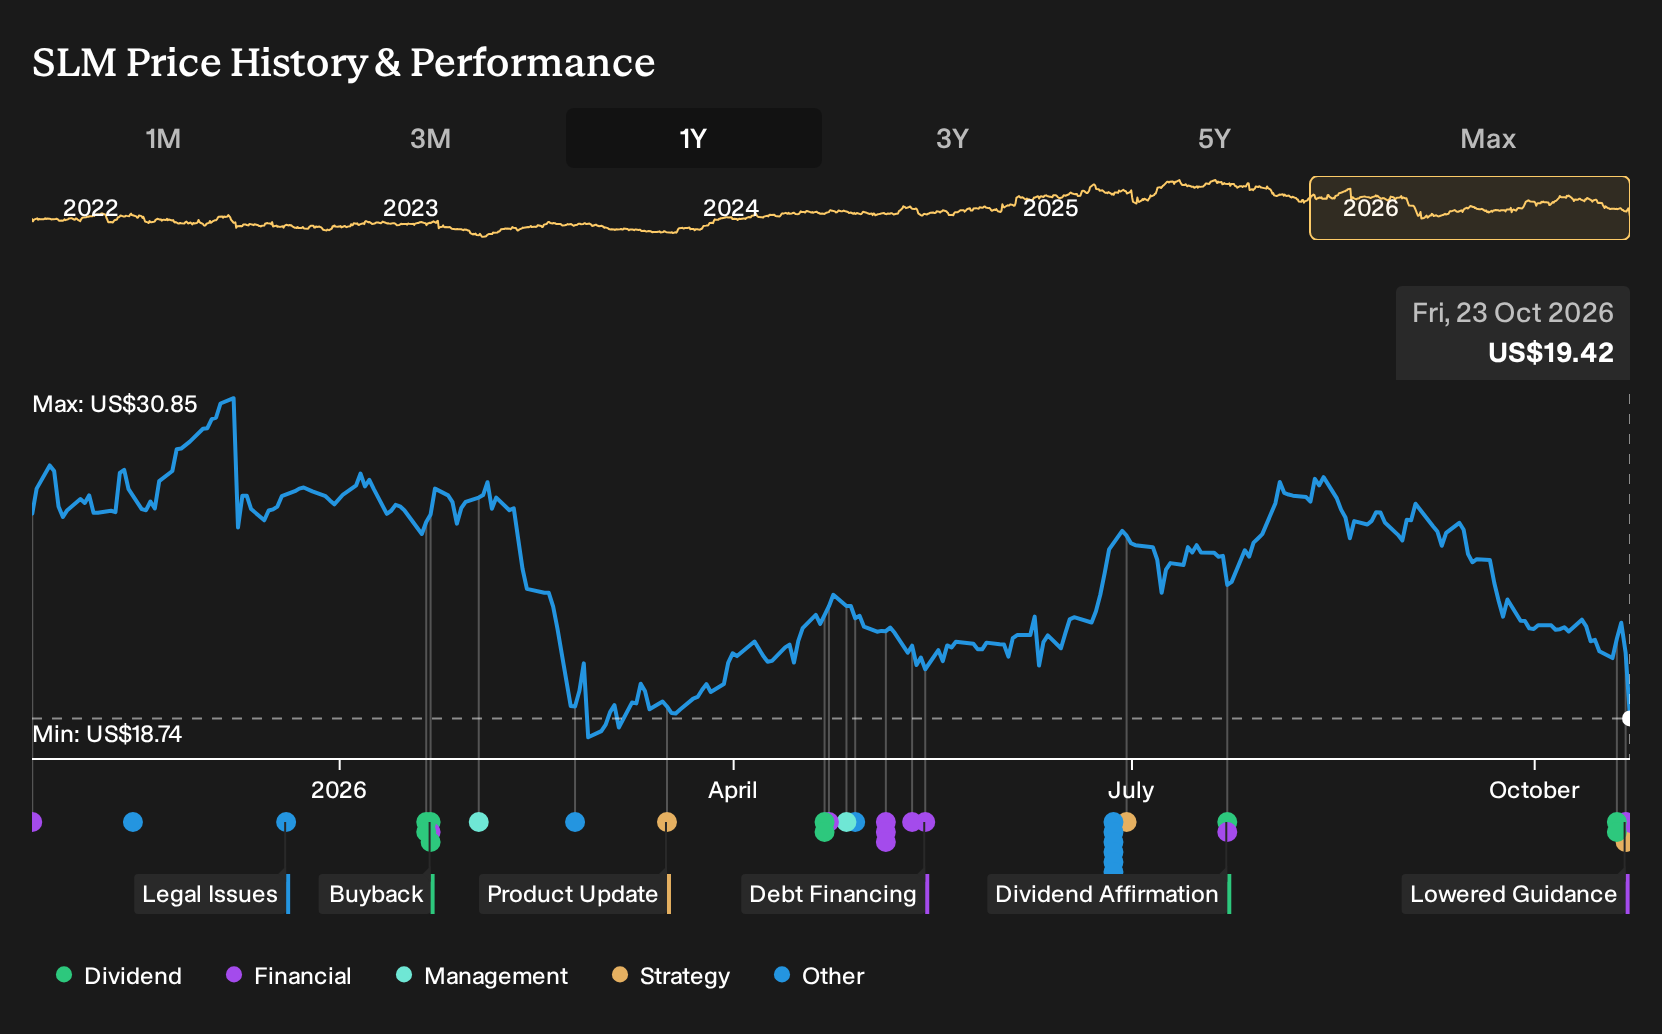
- SLM Corporation reported a third quarter 2026 net loss of US$32.26 million, raised full year net charge off guidance, and cut 2026 diluted EPS guidance to a range of US$1.95 to US$2.05 from a previous range of US$3.10 to US$3.20.
- The business is absorbing higher credit costs and non interest expenses while still returning capital through buybacks and a US$0.13 quarterly dividend. This puts the resilience of SLM's earnings model under closer scrutiny.
- This article will examine how SLM's investment narrative holds up against this guidance cut driven by rising charge offs and provisions.
Contrast SLM's guidance reset and higher charge offs with other lenders by scanning our hand picked 30 resilient stocks with low risk scores, which aim for resilience when credit quality comes under pressure.
SLM Investment Narrative Recap
For an investor to stay with SLM, the belief has to be that private education lending remains a durable niche and that higher risk can still be priced correctly. The recent cut in 2026 EPS guidance to US$1.95 to US$2.05, together with a third quarter loss, puts the near term focus squarely on credit quality and operating discipline.
The key near term catalyst is whether rising provisions and net charge offs start to stabilize as newer, tighter vintages season. The biggest risk is that elevated charge offs and non interest costs persist, which could keep returns on equity reliant on leverage and reduce flexibility to absorb further shocks.
The most relevant recent action is SLM’s decision to keep returning cash through share repurchases while revising earnings lower. From July to September 2026, the company bought back about 5.1 million shares for US$132.22 million, finishing an 11.17 million share program started in January.
That capital return sits alongside a US$0.13 quarterly dividend and comes as the lender reports higher net charge offs and a weaker efficiency ratio. For you as a shareholder, the tension to watch is simple: management is shrinking the share count while credit costs and operating expenses test how much earnings power remains behind each remaining share.
SLM's narrative projects US$1.5b revenue and US$626.4 million earnings by 2029. This suggests relatively stable annual revenue and an increase in earnings of about US$73.6 million from US$552.8 million today.
Uncover why SLM's fair value indicates a 34% potential upside to its current price, which could close quickly if sentiment turns back in SLM's favor.
Exploring Other Perspectives
One alternate view on SLM focuses on capital returns as a risk rather than a benefit. The most pessimistic analysts worried that heavy buybacks could squeeze flexibility if earnings slip, even before this guidance cut. They were already penciling in revenue of about US$1.4b and earnings of roughly US$579.8 million by 2029. This latest update may push those narratives to evolve. You can use that gap between upbeat and bearish assumptions as a reminder that opinions differ widely. It is worth exploring several approaches before deciding how this story fits your own portfolio.
Explore 2 other SLM fair value estimates, including one that suggests it could be worth just $25.30!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SLM research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SLM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SLM's overall financial health at a glance.
Looking for more SLM investment ideas?
Once you have a view on SLM, it can help to compare it with other opportunities that match different risk and income preferences. The Simply Wall St Screener gives you a quick way to line up alternatives that fit the kind of portfolio you want to build next.
- If capital preservation sits near the top of your priority list, check out a curated 30 resilient stocks with low risk scores that may offer a smoother ride when conditions get choppy.
- For investors trying to tilt toward quality at a reasonable price, consider a focused 29 high quality undervalued stocks that highlights companies with strong fundamentals trading below estimated worth.
- If income is a key part of your plan, review a hand picked 5 dividend fortresses that screens for higher yielding payouts with an eye on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com