
Kadant (KAI) Faces Weaker Growth Signals, Is The Pullback Enough To Justify Value?
Kadant (KAI) is back in focus after fresh analyst coverage highlighted weaker annualized revenue growth and a softer return on invested capital. This has raised new questions about how much profitable expansion is left in the story.
The weaker fundamentals have already fed into sentiment. Kadant’s share price has slipped over the past quarter, with a 90-day share price return down 15.94% and a year-to-date share price return down 8.38%, even though the 3-year total shareholder return remains up 21.97%.
Scan beyond Kadant and stress test your watchlist against a curated group of 30 resilient stocks with low risk scores that aim to pair steadier fundamentals with fewer negative surprises.
The drop in Kadant’s share price has reset expectations and cooled enthusiasm. The next issue is simple: does that pullback now fairly reflect the weaker growth profile, or does it still leave buyers taking on more risk than the valuation justifies?
Most Popular Narrative: 27% Undervalued
Kadant’s most followed valuation story pegs fair value well above the recent $262.39 close, which puts the recent share price slide in a different light for anyone weighing risk against long term cash generation.
The aging installed base that Kadant supports is leading customers to spend more on maintenance and upgrades even when facilities are not running at peak utilization, and record aftermarket parts revenue of US$214.2m in Q2 2026 across segments points to a larger pool of recurring service activity that can support future revenue and earnings quality.
Capital equipment projects that management previously described as delayed rather than canceled are now reflected in record bookings of US$320.8m in Q1 2026 and US$312m in Q2 2026 and an equipment backlog of about US$182m to US$193m, which gives Kadant a pipeline of contracted work that has yet to be recognized in revenue or operating profit.
See why 0 investors see Kadant as 27% undervalued.
Result: Fair Value of $361.67 (UNDERVALUED)
Still, weaker gross margins from a less favorable mix and the expected 2026 EPS dilution from Kadant Profil could quickly challenge the bullish Kadant valuation story.
Find out about the key risks to this Kadant narrative.
Another View: Kadant Looks Expensive On Earnings
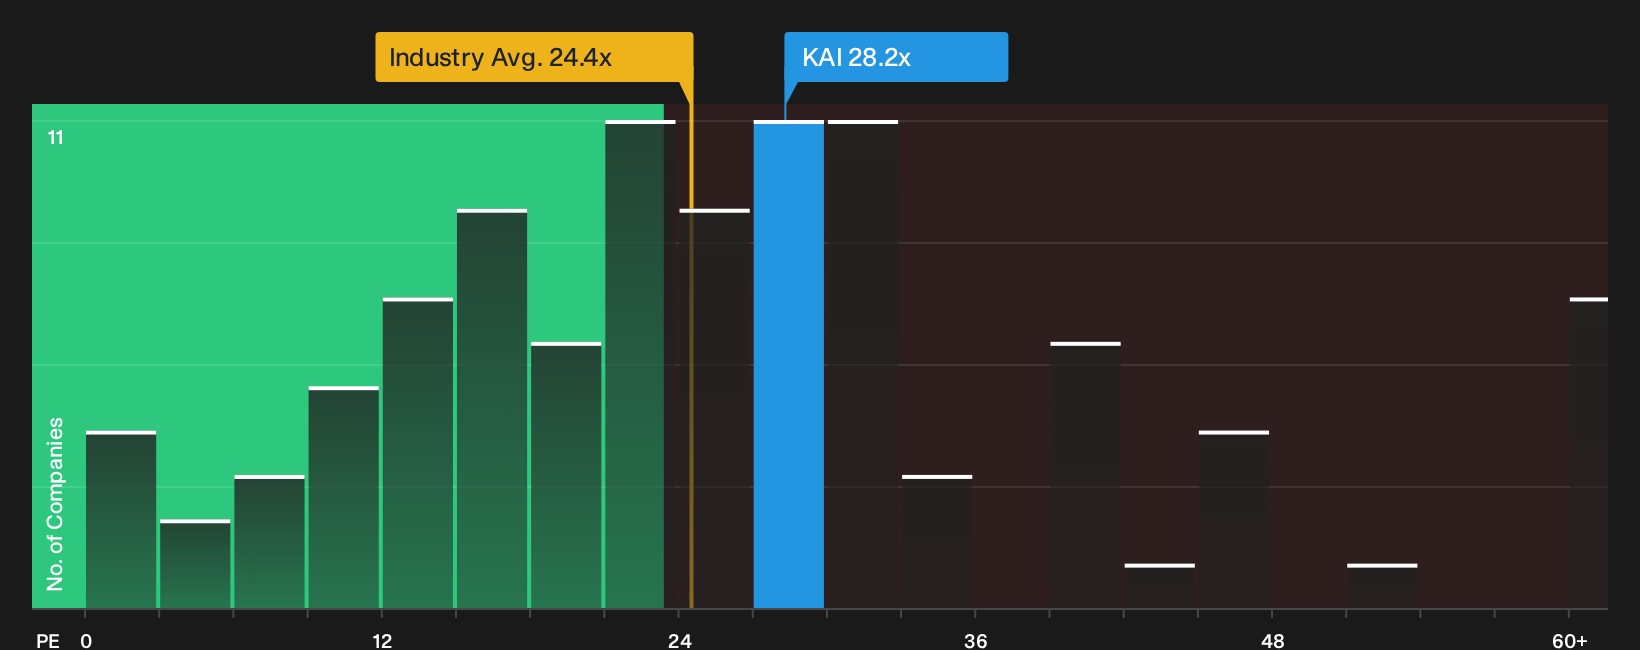
The first story casts Kadant as undervalued at $262.39, but its 28.2x P/E tells a tougher story. That multiple sits above the US Machinery group at 24.4x, peers at 20.9x, and a fair ratio of 22.7x. So is the real risk that expectations are already too rich?
For investors who prefer earnings based checks over cash flow models, this gap in P/E levels is exactly what See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the split views on Kadant leave you unsure, that is understandable. Take prompt action, review the key positives, and weigh them against the softer points in our 3 key rewards
Looking for more Kadant sized investment ideas?
Do not stop at Kadant. Use this pullback as a prompt to refresh your playbook and line up the next wave of opportunities with stronger risk control.
- Target quality at a discount by scanning a curated pool of 29 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Strengthen your income stream by reviewing a focused set of 5 dividend fortresses that aim to combine higher yields with sturdier payout profiles.
- Protect the downside first and shortlist a list of solid balance sheet and fundamentals (24 results) before the rest of the market starts paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com