
Hormel Foods (HRL) Could Be 17% Below Fair Value As Portion Pack Bacon Arrives
Hormel Foods (HRL) just paired a packaging refresh with a governance change, rolling out HORMEL BLACK LABEL Portion Pack Bacon while longtime director Sally J. Smith prepares to retire from the board in 2027.
Recent trading shows Hormel Foods trying to stabilise. The share price has climbed about 6.9% over the past month and 3.2% over the last week, yet remains down roughly 19.2% over 90 days, and the 5 year total shareholder return is lower by about 40.4%.
Capitalize on Hormel Foods' repositioning by reviewing a curated batch of defensive consumer staples with resilient cash flows in our 30 resilient stocks with low risk scores.Hormel Foods now trades well below its 5 year level yet has just rolled out fresh products and is reshaping its portfolio. Do you put cash to work here or wait for a deeper reset on valuation?
Most Popular Narrative: 17% Undervalued
On the most followed narrative, Hormel Foods screens below an estimated fair value of $25.31, compared with a last close of $21.06. This puts the focus squarely on whether the portfolio overhaul can earn that gap.
The ongoing simplification of Hormel Foods' portfolio, including exits from whole bird turkey, Brazil operations, a majority stake in Justin’s, private label snack nuts and certain contract manufacturing, is removing roughly US$300m of lower margin and more volatile annual sales. This can support higher blended net margins and more consistent earnings over time.
See why 41 investors see Hormel Foods as 17% undervalued.
Result: Fair Value of $25.31 (UNDERVALUED)
Still, the bullish Hormel Foods story runs into two clear risks: softer retail volumes after prior price hikes and protein cost swings that could squeeze margins.
Find out about the key risks to this Hormel Foods narrative.
Another View: Hormel Foods Through The P/E Lens
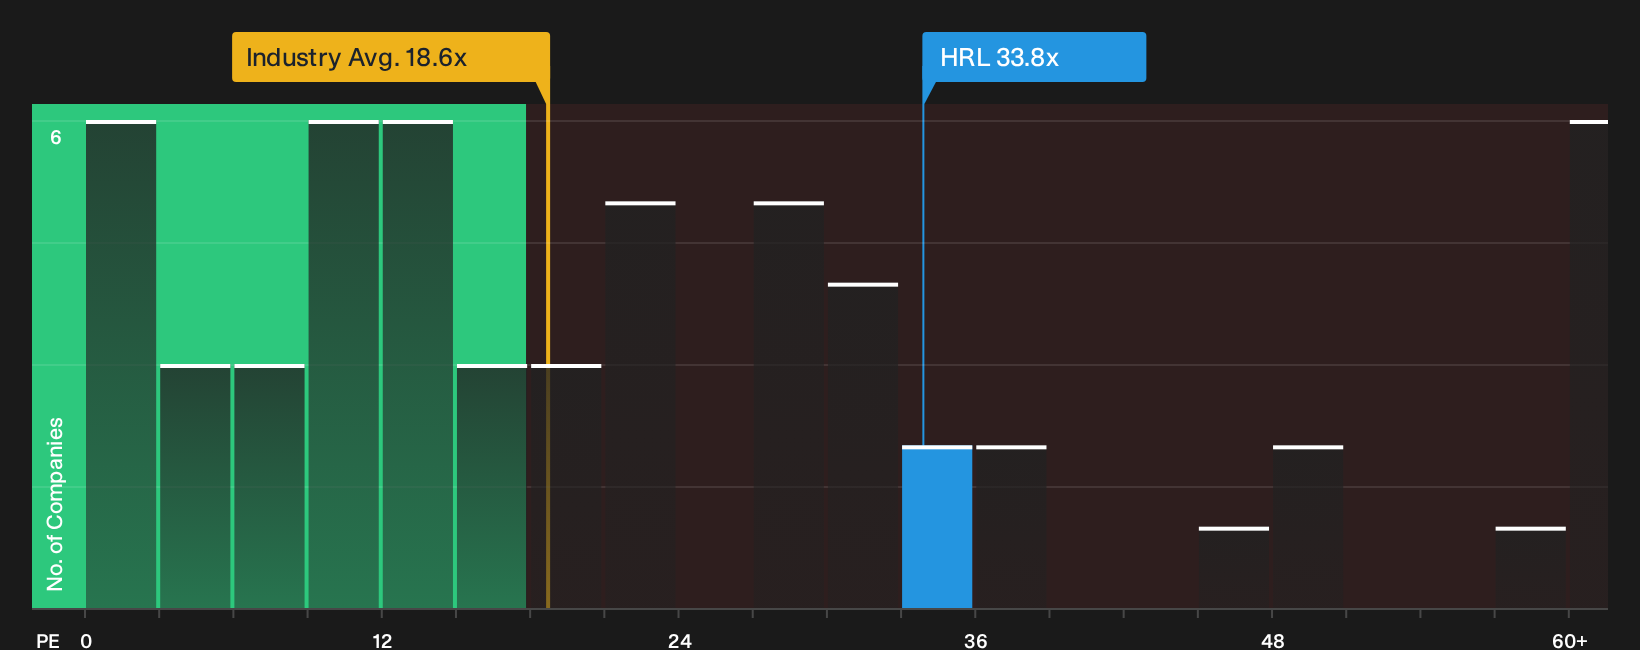
The fair value narrative presents Hormel Foods as undervalued, yet the P/E picture looks less forgiving. HRL trades on about 33.8x earnings versus roughly 22x for peers and 18.6x for the wider US Food group. The fair ratio sits higher at 36.3x. Is that a realistic destination or a valuation trap if sentiment shifts?
Investors who lean on comparative ratios rather than discounted cash flows may want to pressure test that gap using a detailed multiples breakdown before taking a strong view on the stock, starting with the See what the numbers say about this price — find out in our valuation breakdown.
The current P/E premium, the lower industry multiples and the higher fair ratio are all visible in context in the following visual summary. This helps you see how Hormel Foods compares with its sector on price paid for earnings today,
Next Steps
Mixed signals or an early reset for Hormel Foods? Either way, the window to weigh both sides is open now. Pressure test the full set of 3 key rewards and 3 important warning signs in the 3 key rewards and 3 important warning signs
Looking for more Hormel Foods style investment ideas?
Do not stop with Hormel Foods. Use this moment to broaden your watchlist with other opportunities that match your preferred mix of quality, value, and resilience.
- Target steadier capital preservation by scanning a curated 30 resilient stocks with low risk scores that can help you sidestep weaker balance sheets and fragile business models.
- Hunt for mispriced opportunities by running through the 29 high quality undervalued stocks where solid fundamentals and compressed multiples sit side by side.
- Stack potential cash returns on top of price moves by filtering for income ideas in the 5 dividend fortresses that prioritise yield with robust financial backing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com