
Will Stronger Q3 Earnings Change AddLife Stock Narrative
- AddLife reported third quarter 2026 sales of SEK 2,599 million and net income of SEK 127 million, with basic EPS from continuing operations at SEK 1.05, and nine-month sales of SEK 7,965 million and net income of SEK 384 million.
- The stronger earnings per share from continuing operations compared with the prior year suggests that AddLife converted its higher sales into improved profitability rather than relying solely on volume.
- This Q3 uplift in net income and earnings per share is an important factor when considering AddLife's overall investment narrative.
Scan how AddLife's latest earnings stack up against peers by running through the hand picked list of solid balance sheet and fundamentals (207 results).
AddLife Investment Narrative Recap
For an investor to stay with AddLife, the core belief is that its mix of Labtech and Medtech exposure, plus a focus on higher margin product areas, can keep translating into solid earnings. The latest report, with SEK 2,599 million in Q3 sales and SEK 127 million in profit, backs up that focus on profitability rather than pure volume.
The key short term swing factor is execution on tenders and acquisitions without stretching the balance sheet further, since debt levels are already a watchpoint. The main risk right now is pressure on cash flow as new products and inventory build, especially if academic research funding or supply chain conditions soften.
The most relevant update is the Q3 and nine month 2026 earnings release. AddLife reported SEK 7,965 million in sales and SEK 384 million in net income for the period, with basic EPS from continuing operations at SEK 3.15. That is a clear data point on how the business is handling mix shifts and portfolio pruning.
For catalysts, this earnings run rate matters because management has talked about using a stronger balance sheet to pursue more deals in areas like orthopedic surgery and advanced lab technologies. The current profit level gives you a reference when weighing that acquisition plan against existing risks, including higher debt, supply chain exposure and any slowdown in research related demand.
AddLife's current earnings sit at SEK 644.0 million, with analysts projecting SEK 825.4 million in earnings and SEK 13.6b in revenue by 2029. According to those projections, revenue would increase by 8.3% per year and earnings would rise by roughly SEK 181 million compared to today's level.
Uncover why AddLife's fair value points to an 11% potential upside to its current price, a discount that may not last much longer.
Exploring Other Perspectives
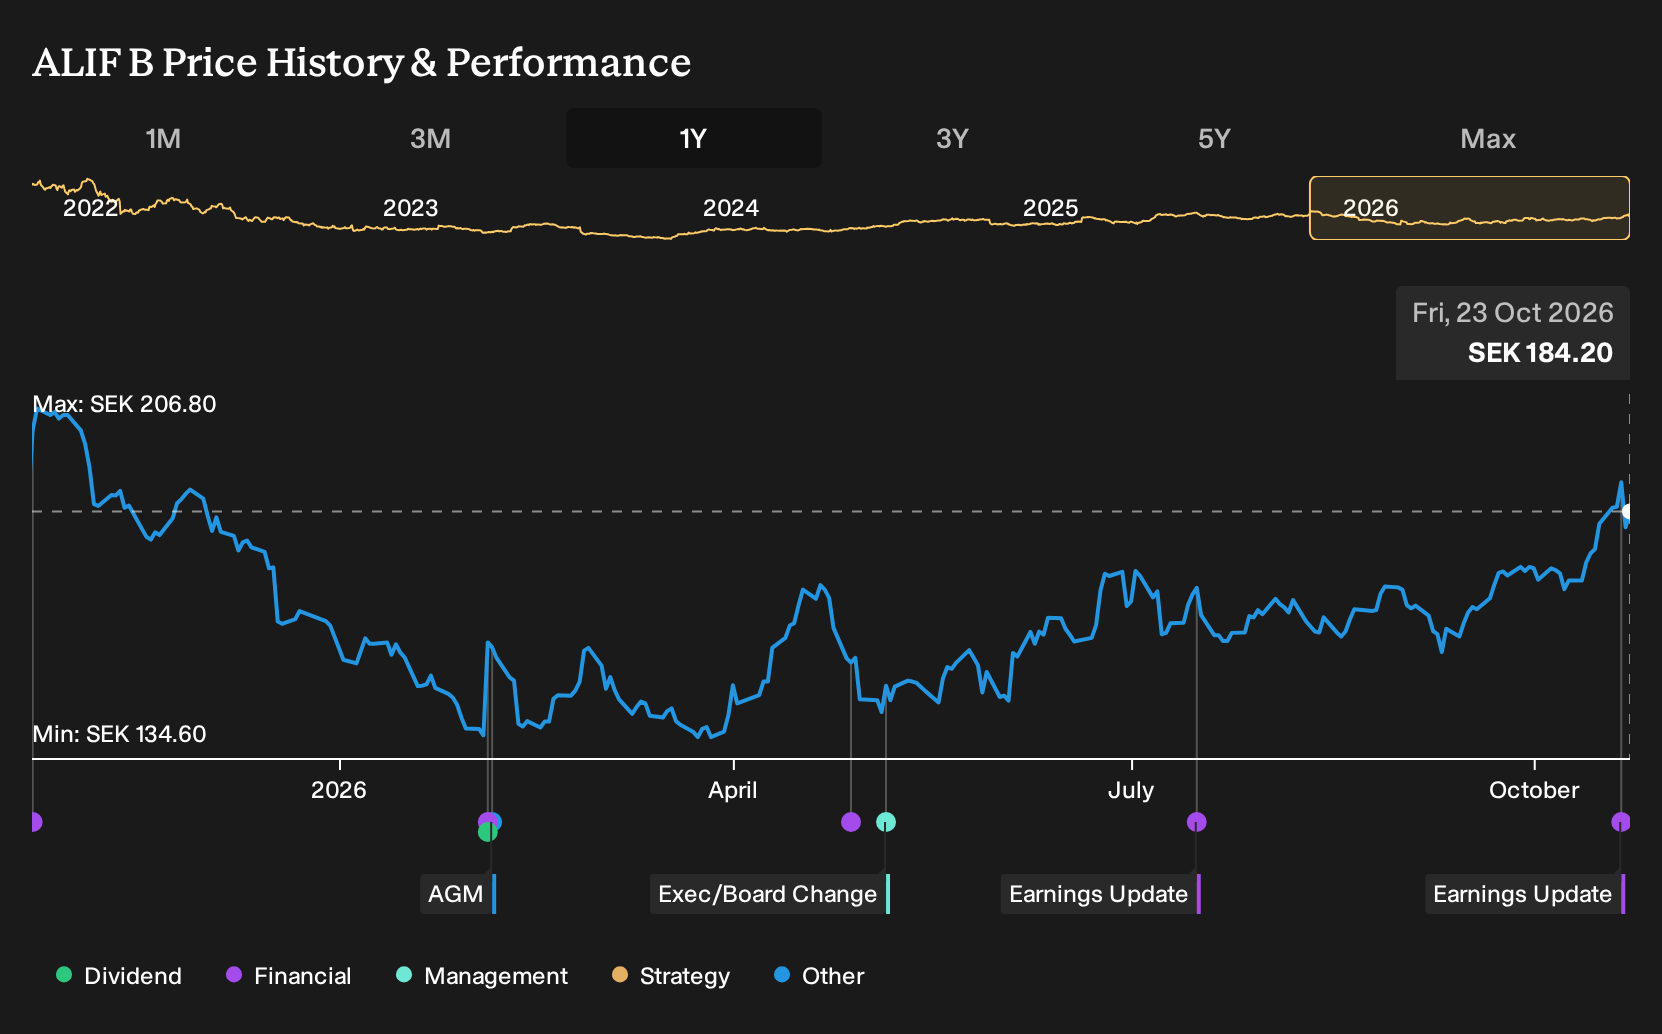
The three fair value estimates from the Simply Wall St Community cluster between SEK 204.75 and about SEK 222.60 per share. This still leaves room for disagreement on what AddLife is worth after the October 2026 earnings release. When you also factor in funding risk around academic research, there is even wider scope for differing views.
Explore 2 other AddLife fair value estimates, including one that suggests up to 21% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Investors who take a different view from the crowd sometimes find unique opportunities, so consider your own analysis and instincts carefully.
- A great starting point for your AddLife research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AddLife. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AddLife's overall financial health at a glance.
Looking For More Ideas Beyond AddLife?
If the AddLife story has sharpened your thinking but you want a wider menu of possibilities, the Simply Wall St Screener can help you compare this stock with other opportunities that fit your style, risk tolerance and time horizon.
- For investors who want potential mispricing combined with quality fundamentals, review a curated set of 194 high quality undervalued stocks that may merit a closer look.
- If resilience and steadier profiles matter more than headline growth, filter the market down to 221 resilient stocks with low risk scores that score well on overall risk metrics.
- To widen the opportunity set into lesser known territory, scan a hand picked group of 612 high quality undiscovered gems that still show solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com