
What Investors Got Wrong Before Van Lanschot Kempen's Rally
If you were watching Van Lanschot Kempen this year, the attention grabber was not a new app or headline deal but a concrete result. H1 2026 revenue reached €411.456 million, with net income of €83.693 million and a higher net margin than a year earlier. Investors who held Van Lanschot Kempen over the past year are up 27.2%, including dividends. If you were deciding back in October 2025, what needed to be true about digital wealth, ESG demand and acquisition execution to make that outcome feel reasonable?
If the move has made Van Lanschot Kempen harder to judge, start where the gap is still open and scan 194 high quality undervalued stocks.
The Argument You Would Have Been Weighing On Van Lanschot Kempen
The shares cost €51.5 at the start of the period, and the debate around Van Lanschot Kempen turned on what that price implied about wealth transfer, digital uptake, and regulation.
The bullish story pointed to a Fair Value of €57, a level that reflected what supporters saw as justified if assumptions played out, built on Van Lanschot Kempen capturing a disproportionately high share of Europe’s intergenerational wealth transfer and using its digital platforms to lift recurring fee income.
The bearish camp leaned on a Fair Value of €44.5 and treated that as the price that would fit if digital disruption and regulatory demands kept pushing up compliance and technology costs, leaving net margins under pressure despite revenue growth assumptions.
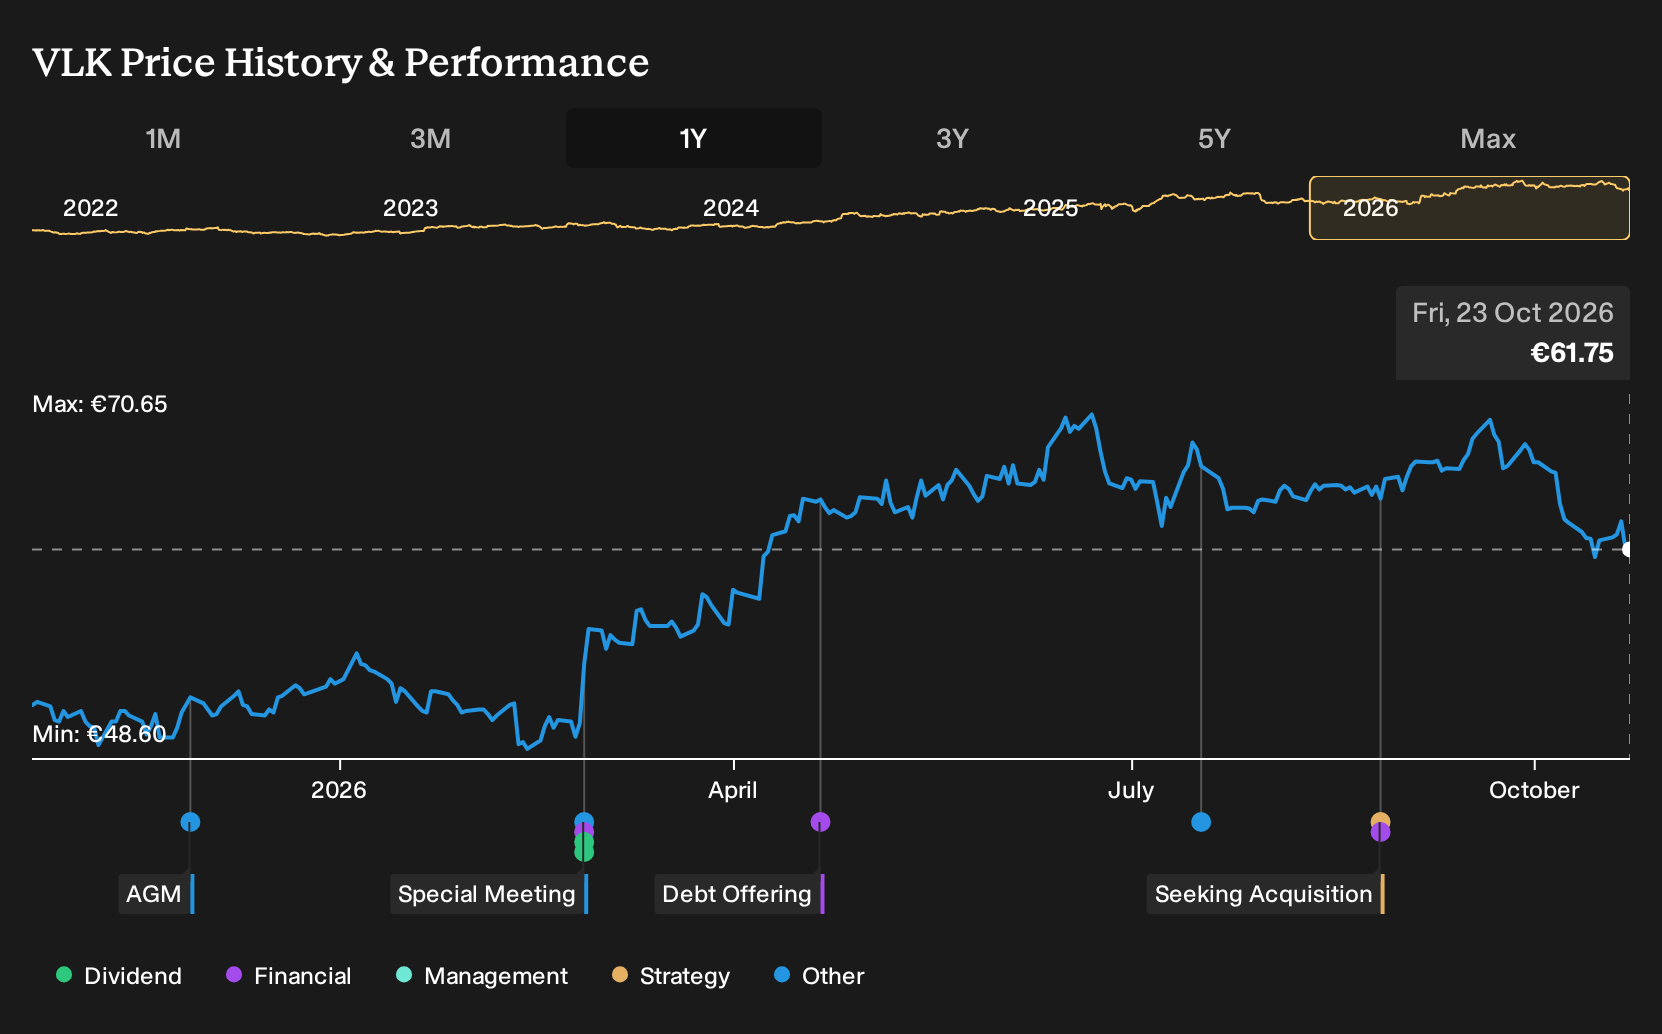
What The Results Changed For Van Lanschot Kempen
H1 2026 gave Van Lanschot Kempen hard numbers to test both stories. Revenue of €411.456 million and net income of €83.693 million, with net margin up from 17.1% to 20.3%, leaned toward the optimistic case that higher quality fees and better efficiency might support stronger profitability.
The lesson is simple. When a thesis hangs on better profitability, focus less on headline growth and more on whether net margin and earnings per share, plus any insider buying, move in the same direction.
What Van Lanschot Kempen's Run Now Prices In
With Van Lanschot Kempen at €61.75 today, the selected Narrative’s Fair Value sits above the current quote rather than below it. That view leans heavily on how a capital light wealth model might scale if the recent mix of client inflows and efficiency holds up.
The crux for investors is whether today’s price fully reflects sustained AUM growth, continued AI driven cost discipline and steady expansion in higher margin mandates. The Narrative effectively argues that the market still underrates how durable those combinations could be.
"The current valuation suggests the market is heavily discounting the durability of Van Lanschot Kempen’s AUM growth, earnings power and capital return capacity, which this bullish narrative considers overly pessimistic and therefore consistent with a potentially undervalued share price."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Go Straight To The Source
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 49% below our estimate - focuses on power and cooling equipment tied to AI data center expansion.
- Company 2 - 15% below our estimate - uses a key gold project to support exploration that sustains production.
- Company 3 - 24% below our estimate - leans on elevator service contracts to expand long-term maintenance relationships.
Three companies from the same screener. Open all 207 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com