
Ascentage Pharma Group International (SEHK:6855) Shares Climbed, What Is Driving Attention Today?
Ascentage Pharma Group International (SEHK:6855) just cleared a fresh regulatory hurdle in China, with lisaftoclax receiving Breakthrough Therapy Designation in combination with acalabrutinib for treatment naive CLL/SLL patients.
Investors have reacted quickly to the Breakthrough Therapy Designation, with Ascentage Pharma Group International’s share price up 6.53% over the last session and showing a 5.05% 1 month share price return. However, momentum has faded over the past quarter, with a 90 day share price decline of 15.57% and a 1 year total shareholder return decline of 55.39%, against still positive 3 and 5 year total shareholder returns.
Spot 611 high quality undiscovered gems that, like Ascentage Pharma Group International after this Breakthrough Therapy Designation, could be quietly building momentum before the wider market pays attention.Ascentage Pharma Group International now has a high profile drug candidate and a volatile share price reaction. The next step is to see whether that story lines up with what investors currently pay for the stock.
Most Popular Narrative: 31% Undervalued
Against the last close of HK$30.36 for Ascentage Pharma Group International, the most followed narrative tags fair value at about HK$44. That gap puts the spotlight on whether recent clinical wins and the cost base can support the kind of business performance implied by that number.
Although Ascentage Pharma Group International has been building a larger commercial footprint with new senior hires and a growing U.S. presence, selling and distribution expenses that more than doubled from 2024 to 2025 and then rose a further 64.3% in 1H26 risk outpacing the revenue that infrastructure can support, which could keep future operating margins under pressure and slow any path toward earnings break even.
See why 2 investors see Ascentage Pharma Group International as 31% undervalued.
Result: Fair Value of HK$44.00 (UNDERVALUED)
Still, if lisaftoclax and olverembatinib continue to match the stronger response data cited in trials, and revenue growth tracks recent trends, the bearish Ascentage Pharma Group International narrative could appear too harsh.
Find out about the key risks to this Ascentage Pharma Group International narrative.
Another View: What Multiples Say About Ascentage Pharma Group International
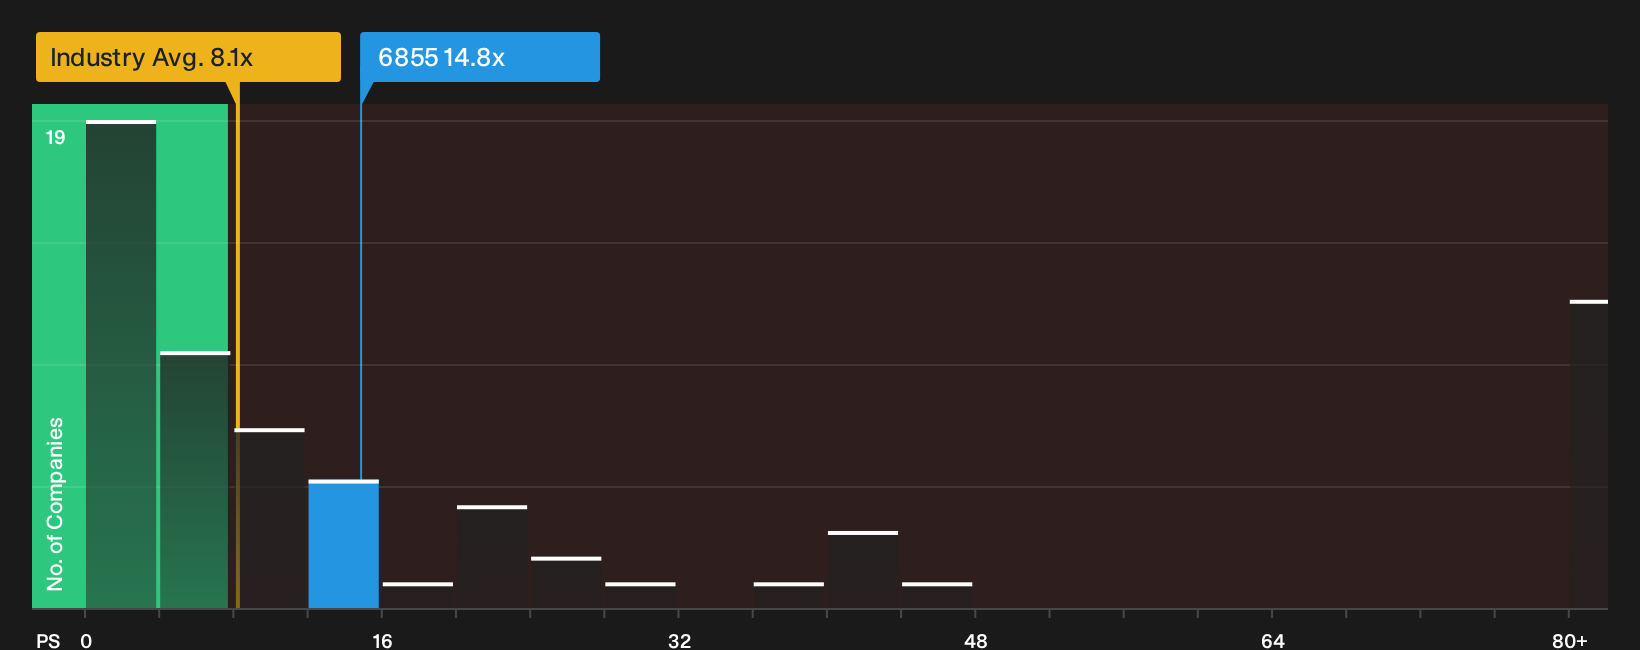
The SWS DCF work points to upside, yet the price investors currently pay for Ascentage Pharma Group International tells a different story. On a P/S of 14.8x, the stock trades well above the Hong Kong Biotechs industry on 8.1x and above its own fair ratio of 13.2x, which implies less margin for error if execution slips or funding needs grow.
For a closer look at how that pricing stacks up against fundamentals and peers, and how the fair ratio could shift if assumptions change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ascentage Pharma Group International can be confusing, so consider acting promptly, reviewing the numbers yourself, and weighing both sides of the story with 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ascentage Pharma Group International?
Ascentage Pharma Group International offers a complex risk reward mix, so it can help to line it up against other opportunities that fit different investing goals.
- Target long term compounding by focusing on quality at a reasonable entry point with 194 high quality undervalued stocks that match your risk profile and time horizon.
- Prioritise sleep at night resilience by reviewing 221 resilient stocks with low risk scores that keep downside in check while still offering meaningful upside potential.
- Get ahead of the crowd by scanning the list of solid balance sheet and fundamentals (207 results) before others notice how much strength sits on those balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com