
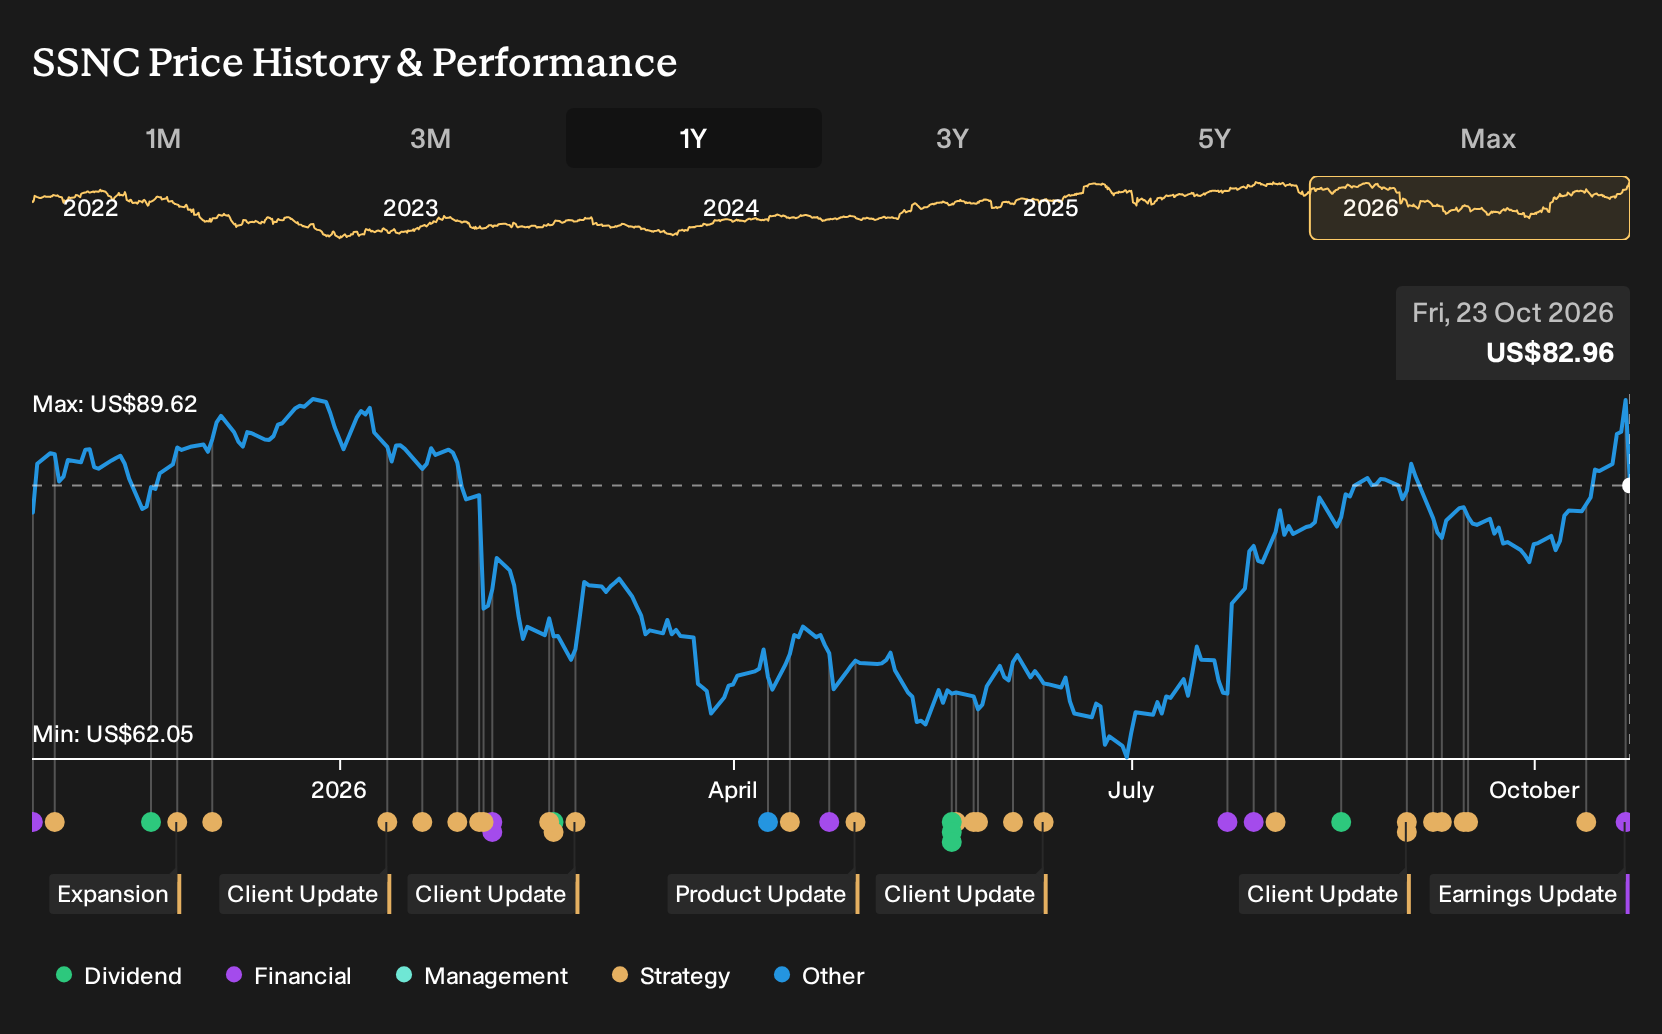
SS&C Technologies Holdings (SSNC) Is Down 7.3% What's Changed After Soft Revenue Outlook
- SS&C Technologies Holdings reported Q3 2026 revenue of US$1.69b and net income of US$198.9m, alongside ongoing share repurchases and a recent dividend increase.
- Management paired solid quarterly results and active capital returns with softer near term revenue guidance, which points to pressure on top line momentum despite continued client wins such as the expanded Thornburg ETF mandate.
- We will now look at how SS&C Technologies Holdings' cautious near term revenue guidance could reshape the longer term investment narrative.
Compare SS&C Technologies Holdings' guidance reset with other potential mispriced opportunities by scanning our hand picked list of 29 high quality undervalued stocks.
SS&C Technologies Holdings Investment Narrative Recap
To own SS&C Technologies Holdings, you need to be comfortable with a story built on sticky software-led services, high recurring activity and the aim of turning that into steady earnings and cash returns. The latest quarter fits that script operationally. Revenue for Q3 2026 was US$1.69b and earnings per share were broadly stable year on year.
The key near term swing factor is whether softer revenue guidance is a temporary pause or the start of slower top line progress after 2026. That matters because margin pressure has already been a concern. The biggest current risk is that expense growth and cautious revenue trends combine to cap profit improvement.
The Thornburg ETF share class mandate is the clearest operational proof point around this earnings update. Thornburg chose SS&C to support actively managed ETF share classes that launched in April and already sit within an ETF roster of more than US$860m in assets. That keeps SS&C Technologies Holdings anchored inside complex, high value workflows.
For you as a shareholder, this type of win ties directly into the main catalysts that matter now. It speaks to growth in outsourced fund administration, ETF infrastructure and AI supported distribution tools. Execution risk sits in delivering these services at scale without further margin slippage, especially while broader revenue guidance has turned more cautious.
SS&C Technologies Holdings’ current analyst narrative points to revenues of US$7.5b and earnings of US$1.3b by 2029. This is based on assumed yearly revenue growth of 4.6% and an earnings increase of about US$436m from US$864.0m today.
Uncover why SS&C Technologies Holdings' fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for SS&C Technologies Holdings from the Simply Wall St Community span roughly US$96 to US$188, based on only two independent models. Those views do not yet reflect the recent revenue guidance reset, share buybacks or dividend increase, so use them as starting points and explore several contrasting opinions before anchoring your own view.
Explore another SS&C Technologies Holdings fair value estimate, including one that suggests up to 126% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SS&C Technologies Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SS&C Technologies Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SS&C Technologies Holdings' overall financial health at a glance.
Looking for more SS&C Technologies Holdings style investment ideas?
If the SS&C Technologies Holdings story has you thinking about where else mispricing or quality might be hiding, it can help to line up a few focused screens and compare patterns side by side.
- For investors who want potential upside paired with disciplined fundamentals, scan our hand picked list of 29 high quality undervalued stocks to see which businesses share similar financial traits.
- If income matters to you and consistency is a priority, take a look at companies in the 5 dividend fortresses that lean into higher yields with an emphasis on resilience.
- When capital preservation sits at the top of your checklist, start with the 30 resilient stocks with low risk scores and focus on businesses that score well on stability and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com