
Impro Precision Industries (SEHK:1286) Reports Stronger Revenue, Is It Still Below Fair Value?
Impro Precision Industries (SEHK:1286) just posted unaudited third quarter revenue of HK$1,782.2 million, up from HK$1,360.8 million a year earlier, with nine month sales reaching HK$4,800.2 million versus HK$3,810.7 million.
The revenue update arrives as Impro Precision Industries’ share price trades at HK$6.165, with the stock climbing 4.31% on a 1-day share price return but down 13.17% over 30 days. The 1-year total shareholder return of 30.90% and 5-year total shareholder return of 237.35% indicate momentum that has been building over a longer horizon.
Scan for other industrials showing similar revenue momentum and long-term returns with a curated list of 611 high quality undiscovered gems that share some of the quality traits behind Impro Precision Industries.
Bulls see Impro Precision Industries’ revenue momentum and long-run shareholder gains as underpriced, while bears point to the recent 30 day slide. Which side does the current valuation actually support next?
Price-to-Earnings of 15x: Is it justified?
Valuation on Impro Precision Industries is split. The stock trades on a 15x P/E, which sits above the Hong Kong Machinery sector but below selected peers, while the SWS fair P/E estimate of 11.4x implies a richer tag than the model suggests.
The P/E ratio compares the HK$6.165 share price with the company’s earnings per share. For a manufacturer supplying precision parts across autos, aerospace and medical devices, this metric helps you see what investors are paying today for each unit of current profit.
On one side, Impro Precision Industries is flagged as good value against a peer average multiple of 20.1x. This implies the market is not paying as much for each dollar of earnings as it does for similar stocks. On the other side, the same 15x P/E screens as expensive versus the Hong Kong Machinery industry average of 11.1x, and also above the estimated fair P/E of 11.4x, a level the market could move toward if sentiment or expectations cool.
Explore the SWS fair ratio for Impro Precision Industries.
Result: Price-to-Earnings of 15x (ABOUT RIGHT)
Still, the recent 30 day share price slide and revenue exposure to autos and aerospace leave room for sentiment to turn if sector demand softens.
Find out about the key risks to this Impro Precision Industries narrative.
Another view on Impro Precision Industries’ value
The P/E picture looks mixed, yet the SWS DCF model tells a very different story for Impro Precision Industries. At a share price of HK$6.17 and an estimated future cash flow value of HK$10.32, the stock is flagged as trading well below that cash flow based fair value.
This kind of gap can signal either a pricing opportunity or a market that sees real risks the model cannot fully capture. Which side do you think is getting it right?
Look into how the SWS DCF model arrives at its fair value.
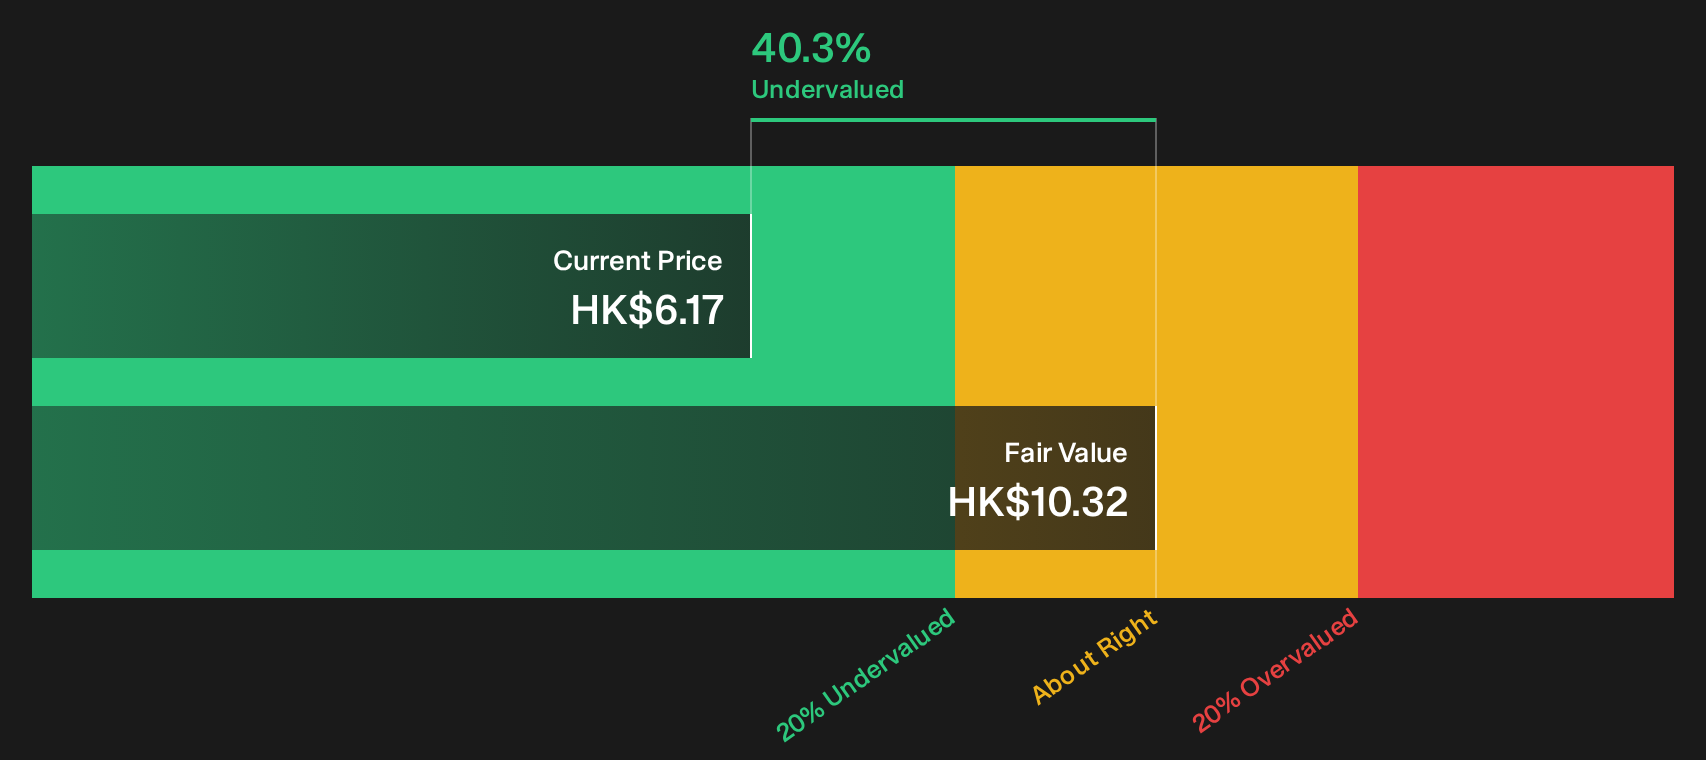
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Impro Precision Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big swings in sentiment often create more questions than answers, so treat Impro Precision Industries as a starting point and test the numbers yourself. To see what optimism is already reflected in the data, review the 3 key rewards
Looking for more investment ideas beyond Impro Precision Industries?
If you stop with Impro Precision Industries, you might miss out on other opportunities that fit your style just as well or even better.
- Start hunting for mispriced quality with the 194 high quality undervalued stocks that already screens for strong fundamentals and supportive balance sheets.
- Prioritise resilience and sleep better at night by focusing on companies highlighted in the 221 resilient stocks with low risk scores that target steadier business profiles.
- Target staying power and financial strength through the list of solid balance sheet and fundamentals (207 results) to spot businesses built on firmer foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com