
LANXESS (XTRA:LXS) Stock Looks Reasonable After a 78% Five Year Fall
LANXESS has seen its share price fall sharply in recent years, which puts fresh attention on whether today's valuation can still be explained by the sales the business generates. For anyone tracking the chemicals group, the core issue is how a much lower stock price lines up with the revenue base that remains in place.
- The share price has fallen 78.2% over the past 5 years, which raises a direct question about how the current valuation lines up with LANXESS' sales profile.
- The group's business model is tied closely to volumes, pricing and product mix in its chemicals portfolio, which can have a direct impact on how much investors are willing to pay for each euro of sales.
- Your read on LANXESS is one view; the desks covering it have another. See what analysts think LANXESS's shares could be worth.
The stock's next move may depend on whether the current share price is adequately explained by LANXESS' sales when compared with the Fair Ratio benchmark.
If you are weighing whether LANXESS' current price fits its sales profile, it can help to benchmark that question against a wider set of 194 high quality undervalued stocks.
Does LANXESS Look Undervalued on Sales?
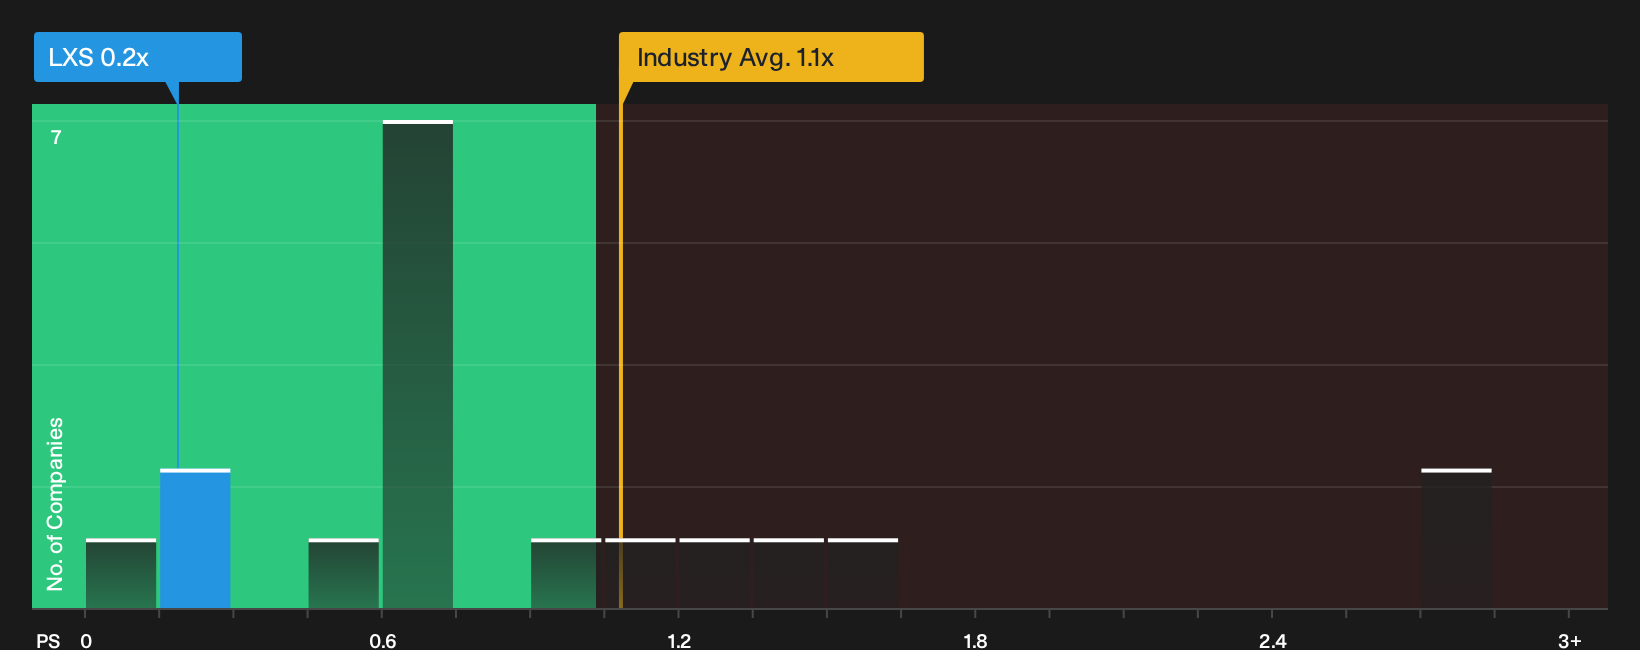
The P/S ratio often suits LANXESS because the group is heavily tied to volumes and pricing, so investors frequently focus on what each euro of revenue costs in the market. On this measure, LANXESS trades on a P/S of about 0.2x, compared with a chemicals industry average near 1.2x and a peer group around 1.1x. The gap shows that the share price values the revenue base at a much lower level than many listed rivals.
The Fair Ratio, which reflects what investors might typically pay for LANXESS once its size, margins, sector and risk profile are taken into account, sits above the current P/S. That places the stock in undervalued territory on this framework, with the market applying a sizeable discount to each euro of sales relative to that tailored benchmark. For anyone assessing LANXESS, the key question is whether the current business quality and risk justify that discount or whether it points to potential mispricing in the revenue multiple. Explore the numbers behind LANXESS's P/S valuation.
The LANXESS Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle around LANXESS leaves off and spell out which combinations of future growth, margins and earnings would need to occur for the share price to look meaningfully higher or lower than it does today, based on frameworks shared on the Community page. Each Narrative sets out fair value as a specific, testable view on LANXESS' business so you can see how that thesis holds up over time.
Community views on LANXESS split between a discounted recovery story and a market that may already be pricing in a cleaner turnaround.
Bull case: 23% undervalued
"Strategic portfolio optimization including the divestiture of the urethane business, accelerated closure of high cost, high CO2 assets, and network consolidation positions LANXESS to allocate capital toward higher margin, resilient segments..."
Discover why this Narrative puts LANXESS at 23% undervalued.
Bear case: 7% overvalued
"The current valuation implies that LANXESS shares already discount a successful earnings recovery, effective capital deployment and clear benefits from the Envalior JV and specialty shift..."
Explore why this Narrative puts LANXESS at 7% overvalued.
LANXESS’ price is only one piece of the investment puzzle
Numbers on a screen do not tell you who is steering LANXESS, how their incentives line up with your interests, or what that might mean for future decisions. See who runs LANXESS and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com