
VSE (VSEC) Could Be 45% Undervalued After Its 21% Monthly Slide
VSE stock performance and recent context
VSE (VSEC) has drawn fresh attention after a sharp pullback, with the share price down about 4% on the day and roughly 21% over the past month. That moves against a three year total return that is materially higher than its one year performance.
Recent trading has shifted the tone around VSE, with the 1-day, 7-day and 30-day share price returns all firmly negative and the stock now at $142.17, while the three year total shareholder return of 168.74% still reflects a very strong earlier run.
Look beyond VSE's pullback and explore other potential opportunities using our hand picked 21 high quality undiscovered gems featuring companies with strong fundamentals that may not yet be on most investors' radar.
After a 21% slide over the past month, VSE now trades near $142.17 while its three year return remains far higher. Does that reset tilt the risk reward balance in favour of buyers or caution?
Most Popular Narrative: 45% Undervalued
VSE last closed at $142.17, while the most followed narrative pegs fair value near $257, which frames the recent pullback very differently for anyone focused on long term cash generation and margin mix.
Continued expansion of VSE’s pure-play aviation aftermarket platform following the Precision Aviation Group acquisition, which adds 61 locations across 8 countries and higher EBITDA margin contribution, can widen the company’s revenue base and support stronger consolidated earnings.
Planned run-rate cost and in-sourcing synergies of about US$15 million annually from Precision Aviation Group, with most impact expected in 2027, have the potential to support higher net margins and cash generation than currently implied by the stock.
See why 6 investors see VSE as 45% undervalued.
Result: Fair Value of $257.11 (UNDERVALUED)
Still, VSE’s heavy tilt to aviation cycles and the US$2b Precision Aviation Group deal funded with debt could pressure cash generation if integration stumbles or demand softens.
Find out about the key risks to this VSE narrative.
Another view on VSE’s valuation
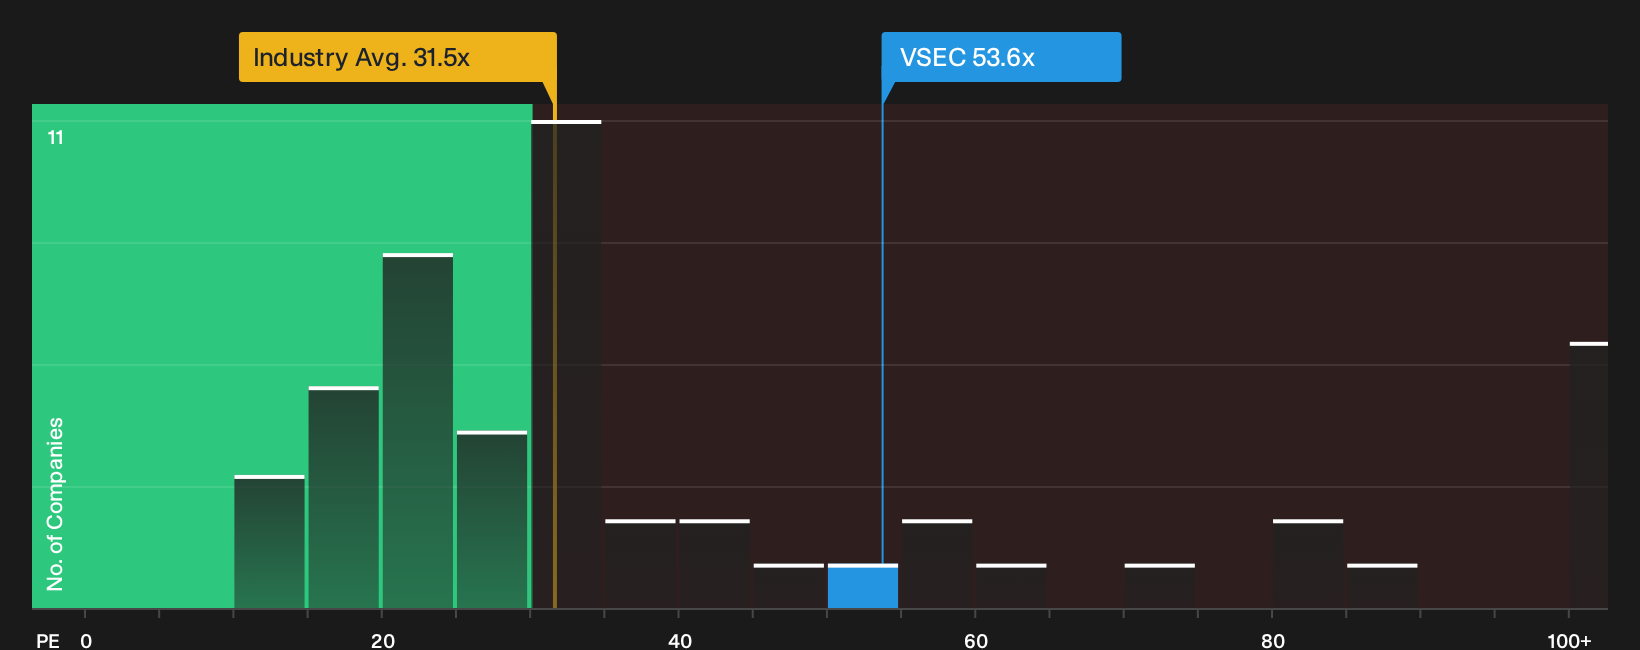
On simple P/E math, VSE looks far less generous. The stock trades around 53.6x earnings, which is richer than the US Aerospace & Defense sector on 31.5x and above a fair ratio estimate of 32.5x. That gap points to valuation risk if growth or margins do not meet expectations.
To see how this earnings multiple stacks up against sector peers and the fair ratio in more detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals like these around VSE rarely remain this stark for long. Look through the full picture and weigh both the potential upside and the potential downside using our breakdown of 4 key rewards and 1 important warning sign.
Looking for more VSE investment ideas?
Do not stop your research with VSE alone. You miss real opportunities if you ignore other businesses that fit the quality, value, or resilience you want.
- Target robust balance sheets and steady fundamentals through our curated list of solid balance sheet and fundamentals (24 results), which can help you filter for financial strength in seconds.
- Hunt for mispriced quality by scanning the 29 high quality undervalued stocks, which highlights businesses where fundamentals and current pricing do not fully align.
- Prioritise resilience first and use the 30 resilient stocks with low risk scores to focus on companies with more measured risk profiles when building out your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com