
Is AI Subscription Push Altering The Investment Case For Data#3 (ASX:DTL)?
- Data#3 has been expanding its AI-focused services, including Microsoft 365 Copilot rollouts, AI analytics, and AI security offerings, and is shifting more of its technology stack to multiyear subscription and as-a-service contracts.
- This combination of AI-led solutions and recurring contracts changes how Data#3 earns revenue and manages risk, tying client outcomes more tightly to long-term service relationships.
- The investment narrative for Data#3 will now be assessed in the context of its expansion into Microsoft 365 Copilot driven AI and its increasing use of recurring contracts.
Data#3 Investment Narrative Recap
To own Data#3, you need to trust that its mix of AI services, Microsoft 365 Copilot work and multiyear subscriptions can keep attracting customers and converting them into recurring relationships. The recent AI focused news mainly reinforces that thesis. The key near term swing factor is simple: how quickly those Copilot and AI projects turn into scaled, repeatable contracts.
The main risk stays the same. Data#3 leans heavily on major vendors, especially Microsoft, for both product and economics. Any further pressure on channel incentives or pricing would test margins, even if recurring revenue grows. If that happens, the business would need stronger contributions from security, managed services and analytics to keep returns where investors expect.
The most relevant development here is Data#3 leaning into Microsoft 365 Copilot deployments as part of its existing Microsoft ecosystem work. That is not just another software sale; it plugs directly into the firm’s cloud, security and workplace offerings and gives customers a clear AI use case linked to productivity rather than experimentation.
For investors watching catalysts, the interesting part is how Copilot related projects can feed the wider subscription engine. Each rollout gives Data#3 an opportunity to attach AI security, analytics and managed services on multiyear terms. Execution risk sits on two fronts: proving customer value quickly and managing any squeeze from Microsoft program changes that could affect profitability on those same engagements.
Analysts mapping out Data#3's trajectory are effectively asking investors to weigh a scenario in which revenue reaches A$4.4b and earnings come in at A$75.0m by 2029, based on an assumed 69.7% annual revenue growth rate and an earnings uplift of about A$20.5m from A$54.5m today.
Uncover why Data#3's fair value indicates a 10% potential downside to its current price, which leaves little room for error.
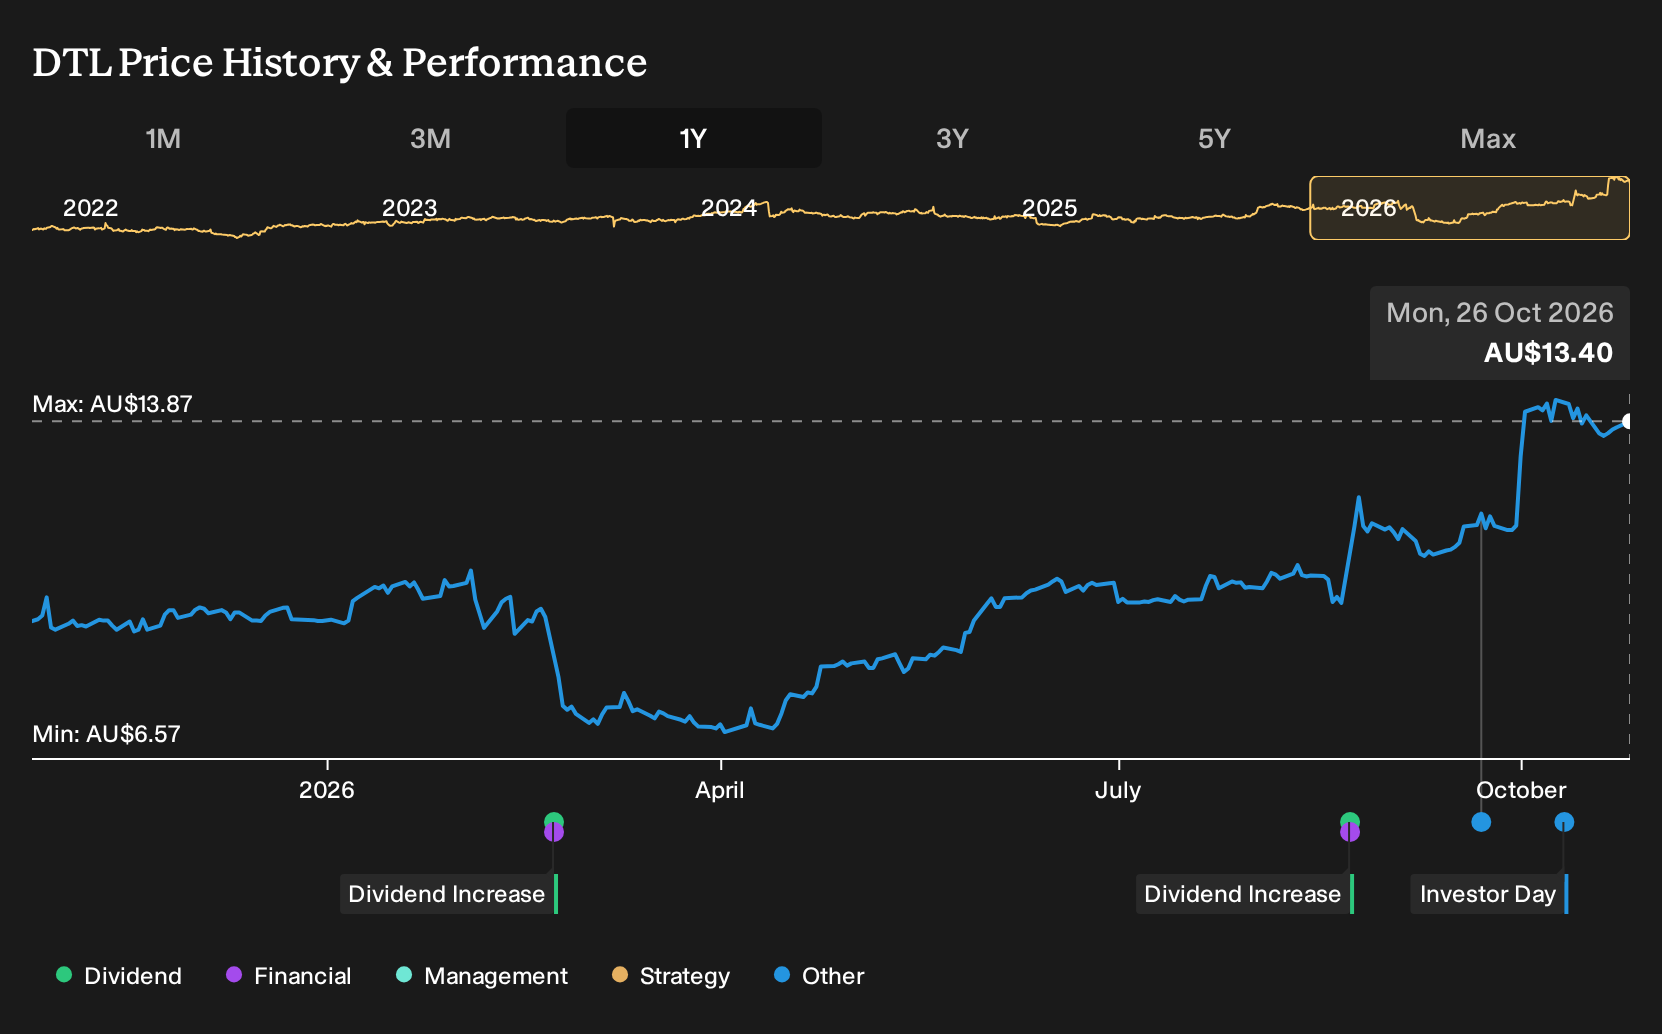
Exploring Other Perspectives
One bearish twist to watch is margin pressure. Some analysts worry that higher staff costs and new AI and security investments at Data#3 will squeeze profits. They were pencilling in earnings of about A$70.1 million on A$4.4b revenue by 2029. Those forecasts came before this Copilot news, so opinions may shift as adoption unfolds.
Explore 2 other Data#3 fair value estimates, including one that suggests up to 10% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Data#3 research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Data#3. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Data#3's overall financial health at a glance.
Looking for more investment ideas beyond Data#3?
Once you have a view on Data#3, it can help to compare it with other opportunities that match your risk profile, income needs and balance sheet preferences. The Simply Wall St Screener gives you a way to filter the market down to a short list that fits your own checklist instead of someone else's.
- If you want income to do more of the work for you, focus on robust cash returns and payout strength through the 4 dividend fortresses.
- If capital preservation matters most, narrow the field to companies that combine financial resilience with steadier risk profiles using the 7 resilient stocks with low risk scores.
- If you prefer businesses with cleaner finances, concentrate on balance sheet strength and solid fundamentals with the list of solid balance sheet and fundamentals (12 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com