
3 Oil And Gas Stocks Retail Investors May Watch As Supply Risks Return
Oil prices have just cooled after a sharp run, yet weekly gains and fresh supply risks from Houthi attacks keep energy markets on edge. That mix of relief and uncertainty can quickly reshuffle which integrated oil and gas majors look resilient and which appear exposed. This article walks through three stocks from the Global Integrated Oil & Gas Majors screener that are closely tied to this news backdrop and explains why their current positioning might matter to your portfolio.
The three integrated oil and gas majors highlighted below are just a sample, and the broader screen surfaced another 7 large, liquid operators with equally compelling narratives that are not covered here.
To see how these players compare in terms of size, balance sheet strength and valuation, head straight into the Global Integrated Oil & Gas Majors screener to identify, analyze and focus on the highest conviction ideas for your watchlist.
Mangalore Refinery and Petrochemicals (BSE:500109)
Mangalore Refinery and Petrochemicals gives you pure downstream exposure inside a screen built around large integrated energy operators. This means its refining heavy profile can react differently to crude swings than the diversified giants it sits alongside.
Mangalore Refinery and Petrochemicals refines crude oil into fuels and petrochemicals in India and overseas, generating about ₹1,095.6b from its downstream petroleum segment, and the stock carries a roughly ₹284.5b market value.
"High dependence on imported crude and recent sanction-driven volatility in Russian crude supply pose ongoing risk to cost stability. An overvalued stock price may be ignoring how these geopolitical and supply chain disruptions could compress gross margins and earnings in the medium term."
What really matters now is how one less obvious pressure on Mangalore Refinery and Petrochemicals ultimately feeds through to refining margins and earnings resilience.
If that pressure point has your attention, read the full narrative for Mangalore Refinery and Petrochemicals to see how margin risk, pricing power and any potential upside might really be interacting.

Channel Infrastructure NZ (NZSE:CHI)
Channel Infrastructure NZ plugs into the Global Integrated Oil & Gas Majors theme as a fuel infrastructure hub that leans on throughput and storage rather than direct crude exposure. This makes its contracts and fee structure crucial when oil markets stay volatile.
Channel Infrastructure NZ operates fuel import, storage and pipeline assets in New Zealand, earning about NZ$143 million from its infrastructure segment and holding a market value of roughly NZ$1.4b.
"The company is leaning heavily on long duration storage contracts and CPI indexation. However, the contracted $5 million annual step down in fixed terminal fees from April 2025 and the expiry of the legacy Wiri lease show how future contract renewals or resets could dilute pricing power and pressure revenue and EBITDA margins."
What matters most now is whether one quiet shift in contract economics tilts that infrastructure fee model toward sturdier margins or a slower grind.
To see how that contract risk could evolve for Channel Infrastructure NZ, read the full narrative for Channel Infrastructure NZ and see whether fee shifts are masking a stronger earnings story.

HD Hyundai (KOSE:A267250)
HD Hyundai is a Korea based energy and industrial group in the Global Integrated Oil & Gas Majors theme, with refining, shipbuilding, electrical equipment and construction machinery operations. Essential Oil contributes about ₩51.6b, Shipbuilding & Marine Engineering ₩37.5b and Construction Equipment ₩13.2b in revenue, while the stock carries a roughly ₩9,738.1b market value.
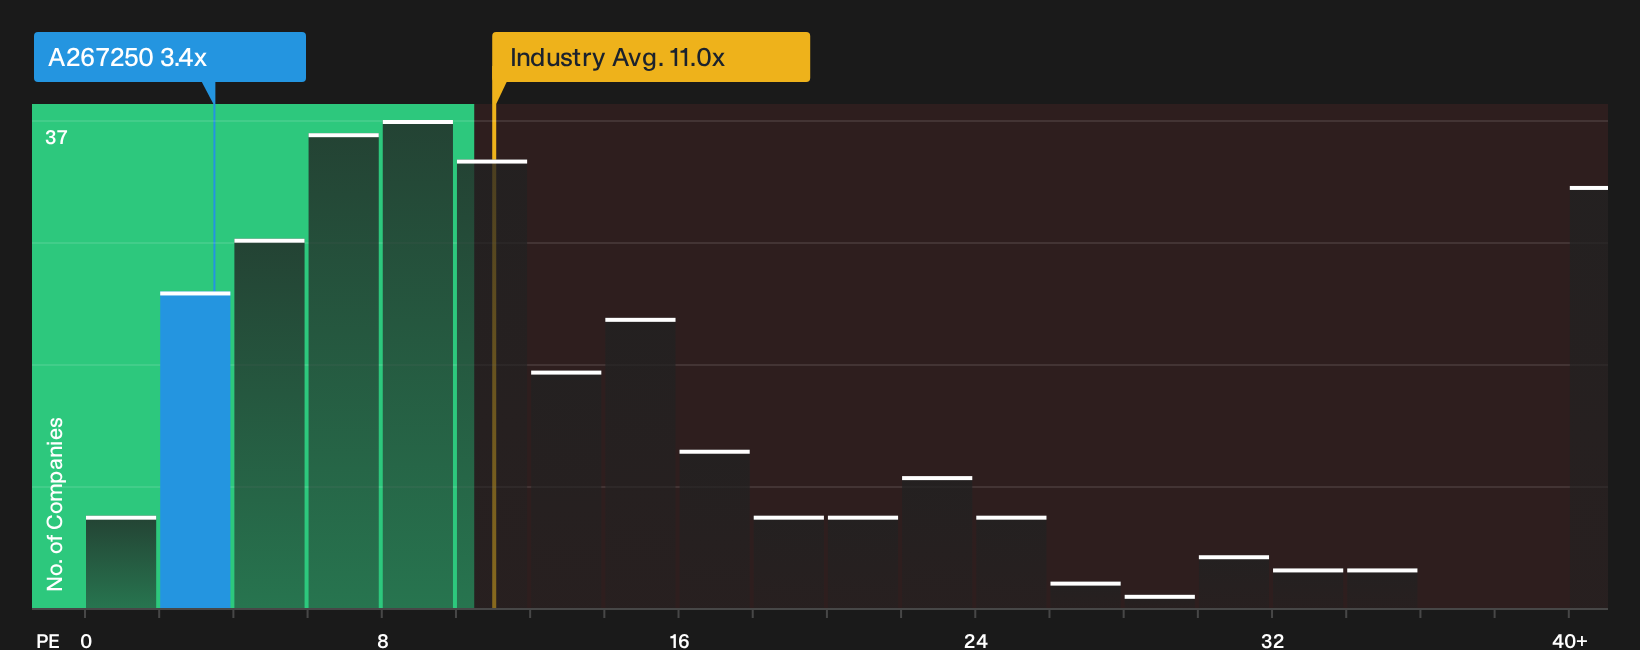
HD Hyundai offers investors a large scale, refining led way to tap broader oil price moves, wrapped inside a diversified industrial group that also builds ships and heavy equipment. The appeal is that this integrated exposure trades on a low P/E and improving profitability. One unseen pressure could still shift how reliable those refining economics feel.
That hidden pressure point is exactly what the 5 key rewards and 1 important warning sign is built to unpack, so you can judge whether HD Hyundai’s low P/E is mispricing future swings.
Seeking Alternatives Before The Window Closes
Fresh opportunities do not wait. While attention locks on today’s headlines, other ideas gain momentum under the radar for now. Before ideal entry points get caught, consider acting soon.
- Identify resilient income plays with pricing power by scanning the 230 dividend fortresses before yields change and the crowd starts targeting the same payouts.
- Explore potential AI-related opportunities by checking the 55 AI infrastructure stocks, focusing on infrastructure enablers that may not yet be widely followed.
- Review the curated 16 top copper producer stocks to stay informed on materials names that could be affected by evolving supply and demand conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com