
Top Undervalued Small Caps With Insider Action In Global For October 2026
In October 2026, the global markets have experienced a notable shift as small-cap stocks, represented by the Russell 2000 Index, outperformed major indices with a 2.00% gain amid a rotation in market leadership. This environment has sparked interest in small-cap companies that demonstrate resilience and potential growth, particularly those showing insider activity which can be an indicator of confidence from within the company.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 4.0x | 0.9x | 22.04% | ★★★★★★ |
| Timbercreek Financial | 16.7x | 9.7x | 38.50% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.8x | 0.9x | 40.56% | ★★★★★☆ |
| Centurion | 15.7x | 3.0x | 20.54% | ★★★★☆☆ |
| Franchise Brands | 26.6x | 2.0x | 48.64% | ★★★★☆☆ |
| Yellow Pages | 8.5x | 0.8x | 28.53% | ★★★☆☆☆ |
| Transcontinental | 2.8x | 0.2x | -112.45% | ★★★☆☆☆ |
| Pizza Pizza Royalty | 11.6x | 8.9x | 40.21% | ★★★☆☆☆ |
| Citicore Energy REIT | 13.0x | 9.9x | 27.84% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.7x | 23.45% | ★★★☆☆☆ |
Let's take a closer look at a couple of our picks from the screened companies.
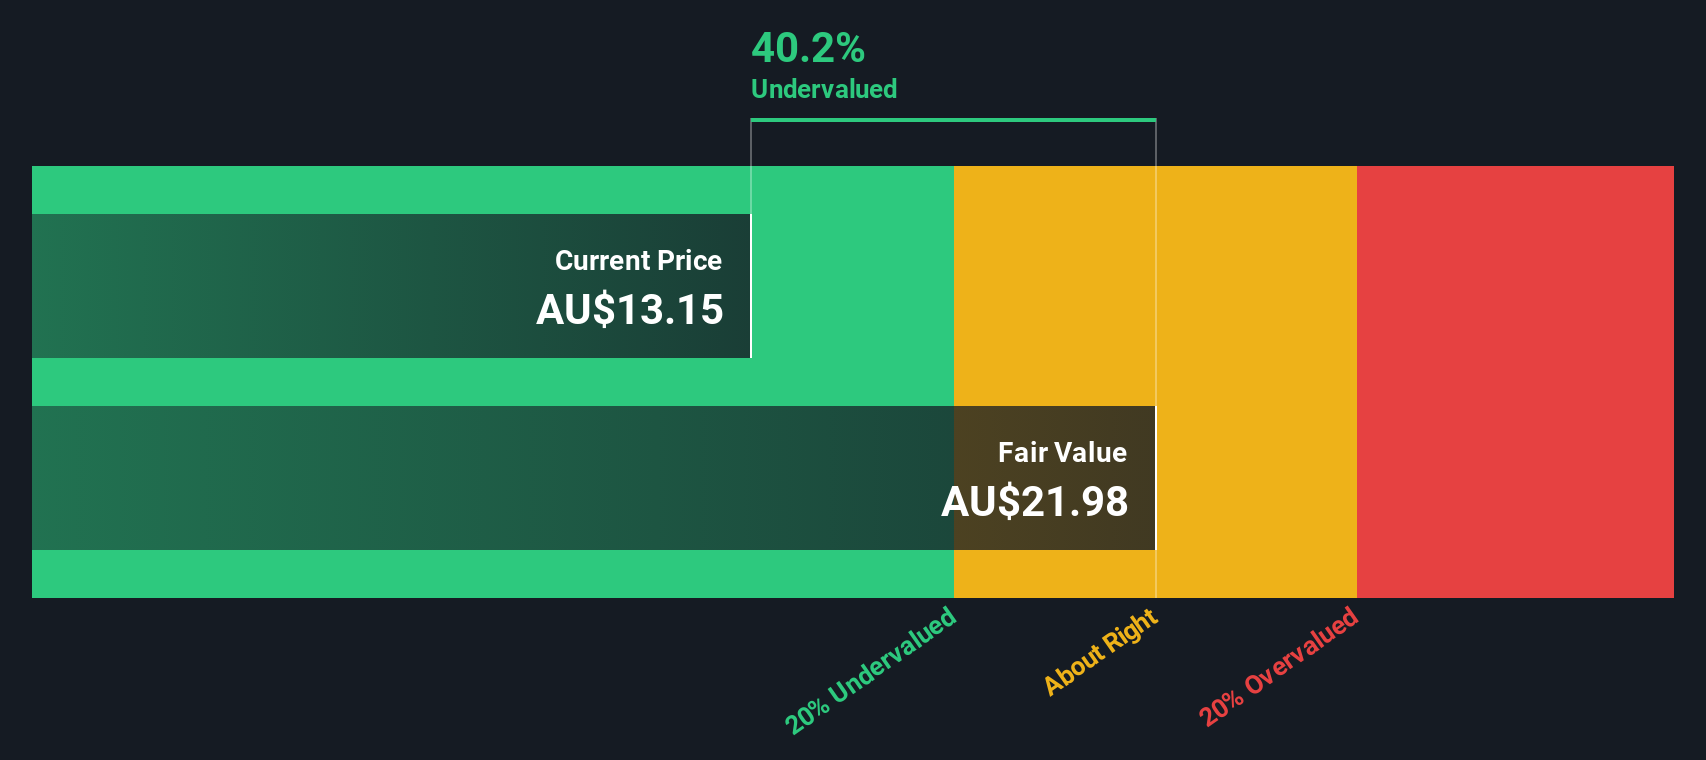
Credit Corp Group (ASX:CCP)
Simply Wall St Value Rating: ★★★★★☆
Overview: Credit Corp Group is a financial services company specializing in debt ledger purchasing and consumer lending across Australia, New Zealand, and the United States with a market capitalization of A$1.61 billion.
Operations: The company generates revenue primarily from debt ledger purchasing in the United States and Australia/New Zealand, as well as consumer lending in Australia and New Zealand. Over recent periods, net income margin has shown variability, with a notable decrease to 13.36% by December 2023 before recovering to 22.08% by June 2026. Operating expenses are a significant component of costs, consistently comprising over half of the revenue across multiple periods.
PE: 9.4x
Credit Corp Group, a company with a market niche in debt buying, shows potential as an undervalued investment. With insider confidence evident from Bradley Cooper's recent purchase of 10,948 shares worth A$151,783 in September 2026, the company is seeing interest from within. Despite its reliance on higher-risk external borrowing for funding and challenges in the US market, Credit Corp projects earnings growth between 4% to 12% for FY2027. The firm's recent net income increase to A$105.51 million and dividend hike reflect financial resilience amidst these conditions.
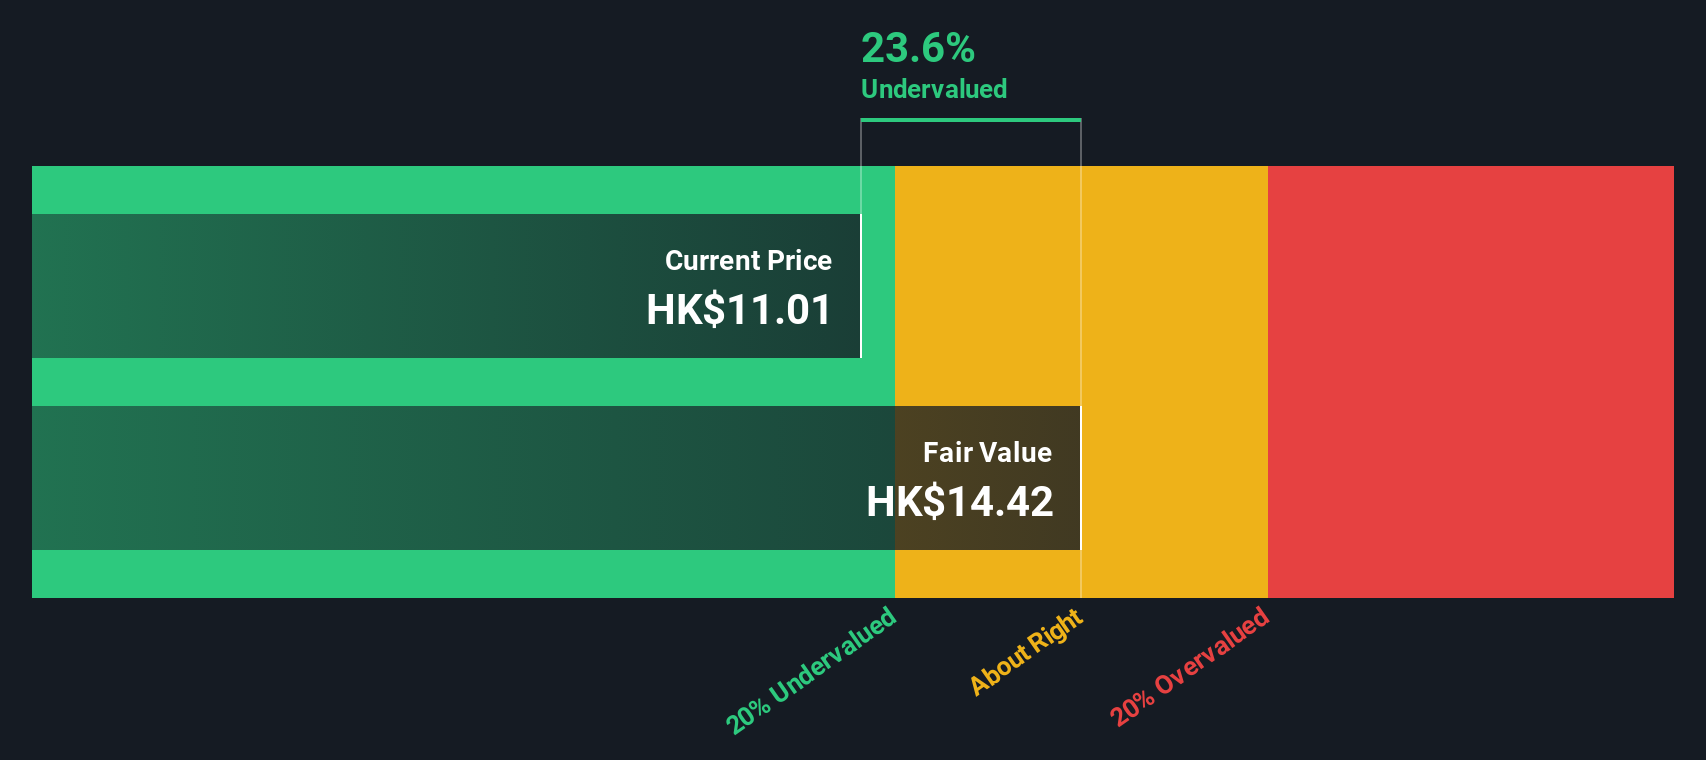
Q Technology (Group) (SEHK:1478)
Simply Wall St Value Rating: ★★★★★☆
Overview: Q Technology (Group) is a company engaged in the design, manufacturing, and sales of camera modules and fingerprint recognition modules with a market capitalization of CN¥8.54 billion.
Operations: Q Technology (Group) generates revenue primarily from its core business operations, with recent figures showing CN¥21.97 billion in revenue for the quarter ending June 2026. The company's cost of goods sold (COGS) was CN¥20.35 billion, leading to a gross profit of CN¥1.62 billion and a gross profit margin of 7.36%. Operating expenses include significant allocations towards research and development, which amounted to CN¥723.40 million in the same period, reflecting an emphasis on innovation within their financial structure.
PE: 3.3x
Q Technology is capturing attention in the investment landscape, particularly with insider confidence shown by Fuqiang Fan's purchase of 218,000 shares worth CNY 1.13 million, boosting their stake by 7.76% in August 2026. Despite a forecasted earnings decline of 4.2% annually over three years, revenue is expected to grow nearly 9% yearly. Recent sales data reveals robust activity with mobile product volumes reaching over 473 million units year-to-date September 2026, indicating potential for future growth amid higher risk funding reliance.
- Click to explore a detailed breakdown of our findings in Q Technology (Group)'s valuation report.
Explore historical data to track Q Technology (Group)'s performance over time in our Past section.
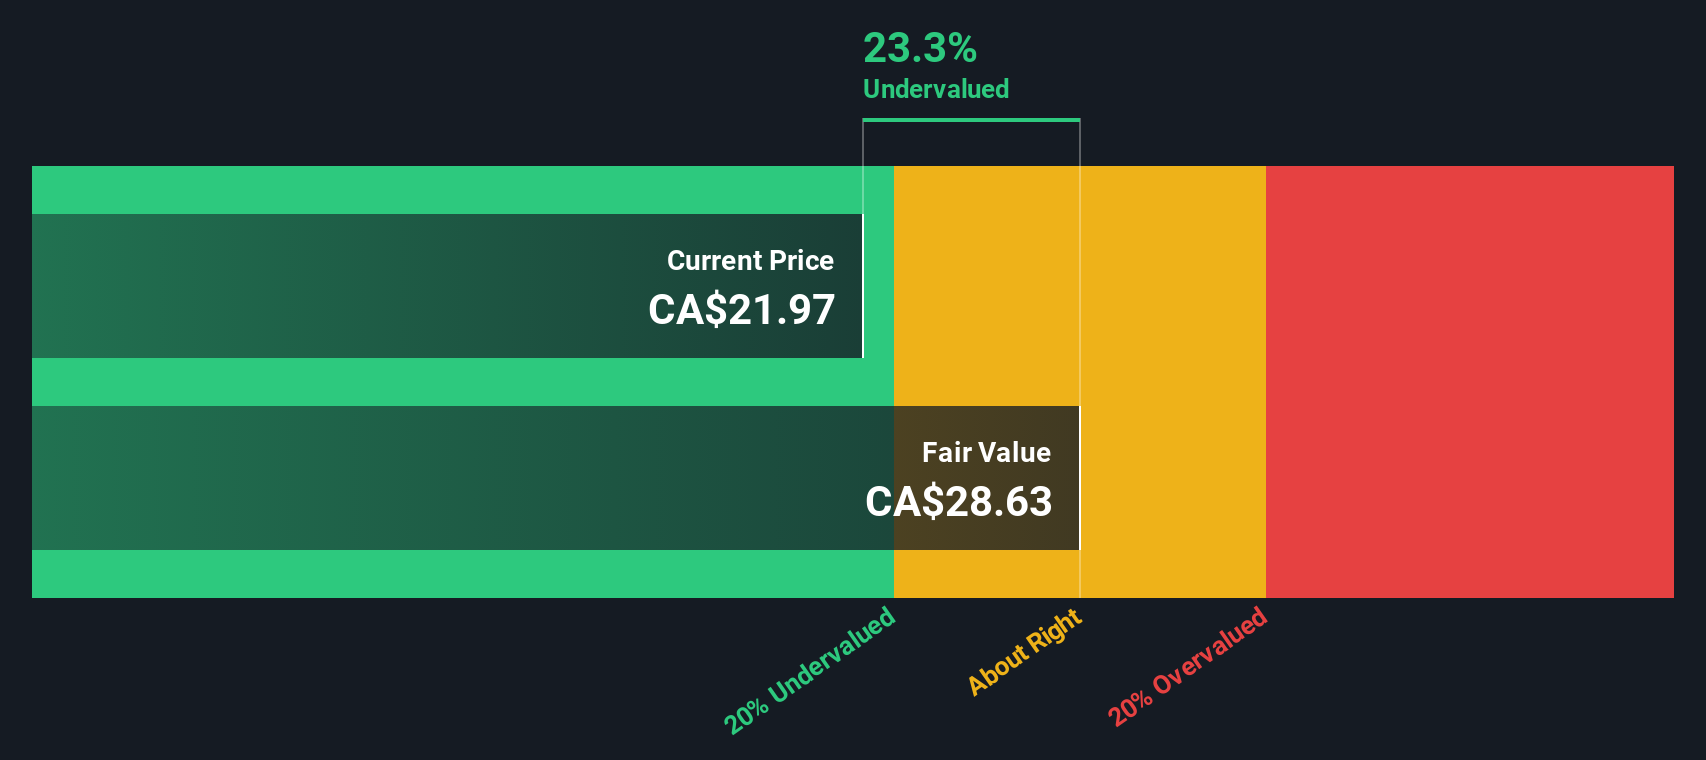
Allied Properties Real Estate Investment Trust (TSX:AP.UN)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Allied Properties Real Estate Investment Trust focuses on owning, managing, and developing urban workspace properties in major Canadian cities with a market capitalization of CA$2.72 billion.
Operations: The company generates revenue across key regions including Toronto & Kitchener, Montréal, Vancouver, and Calgary. Over recent periods, the gross profit margin has shown a decline from 57.11% to 10.45%, indicating changes in cost structures or pricing strategies. Operating expenses have been relatively stable with general and administrative expenses being a significant component. The net income margin has experienced fluctuations, recently reaching negative levels due to substantial non-operating expenses impacting profitability.
PE: -0.5x
Allied Properties Real Estate Investment Trust, a smaller player in the market, recently appointed Donald E. Clow to its Board of Trustees, bringing extensive real estate expertise. Despite reporting a net loss of C$891.4 million for the first half of 2026, Allied maintains consistent monthly distributions at C$0.06 per unit. The company repurchased 569 shares for C$0.006 million between April and June 2026, signaling potential insider confidence in its future prospects amidst challenging financials and reliance on external borrowing for funding.
Seize The Opportunity
- Embark on your investment journey to our 117 Undervalued Global Small Caps With Insider Buying selection here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com