
Global Market Insights Three Stocks Possibly Trading Below Estimated Value
In recent weeks, global markets have been characterized by volatility driven by AI investment concerns and rising oil prices, with small-cap and value-oriented stocks outperforming amidst a shift in market leadership. As investors navigate these turbulent conditions, identifying stocks that may be trading below their estimated value can offer potential opportunities for those looking to diversify their portfolios.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Thai Credit Bank (SET:CREDIT) | THB22.90 | THB45.74 | 49.9% |
| STO ExpressLtd (SZSE:002468) | CN¥14.64 | CN¥29.16 | 49.8% |
| Smartsens Technology (Shanghai) (SHSE:688213) | CN¥109.28 | CN¥216.15 | 49.4% |
| Sentia (OB:SNTIA) | NOK80.00 | NOK159.56 | 49.9% |
| P.S.P. Specialties (SET:PSP) | THB7.40 | THB14.65 | 49.5% |
| P&H Tech (KOSDAQ:A239890) | ₩3110.00 | ₩6206.43 | 49.9% |
| Nissei ASB Machine (TSE:6284) | ¥7900.00 | ¥15788.69 | 50% |
| Kissei Pharmaceutical (TSE:4547) | ¥3870.00 | ¥7679.17 | 49.6% |
| Henan Mingtai Al.IndustrialLtd (SHSE:601677) | CN¥14.09 | CN¥28.15 | 50% |
| DWS Group GmbH KGaA (XTRA:DWS) | €63.60 | €126.79 | 49.8% |
Underneath we present a selection of stocks filtered out by our screen.
Southern Publishing and MediaLtd (SHSE:601900)
Overview: Southern Publishing and Media Co., Ltd. operates as a publishing company in China with a market cap of CN¥11.45 billion.
Operations: Southern Publishing and Media Co., Ltd. generates revenue through its core operations in publishing within China.
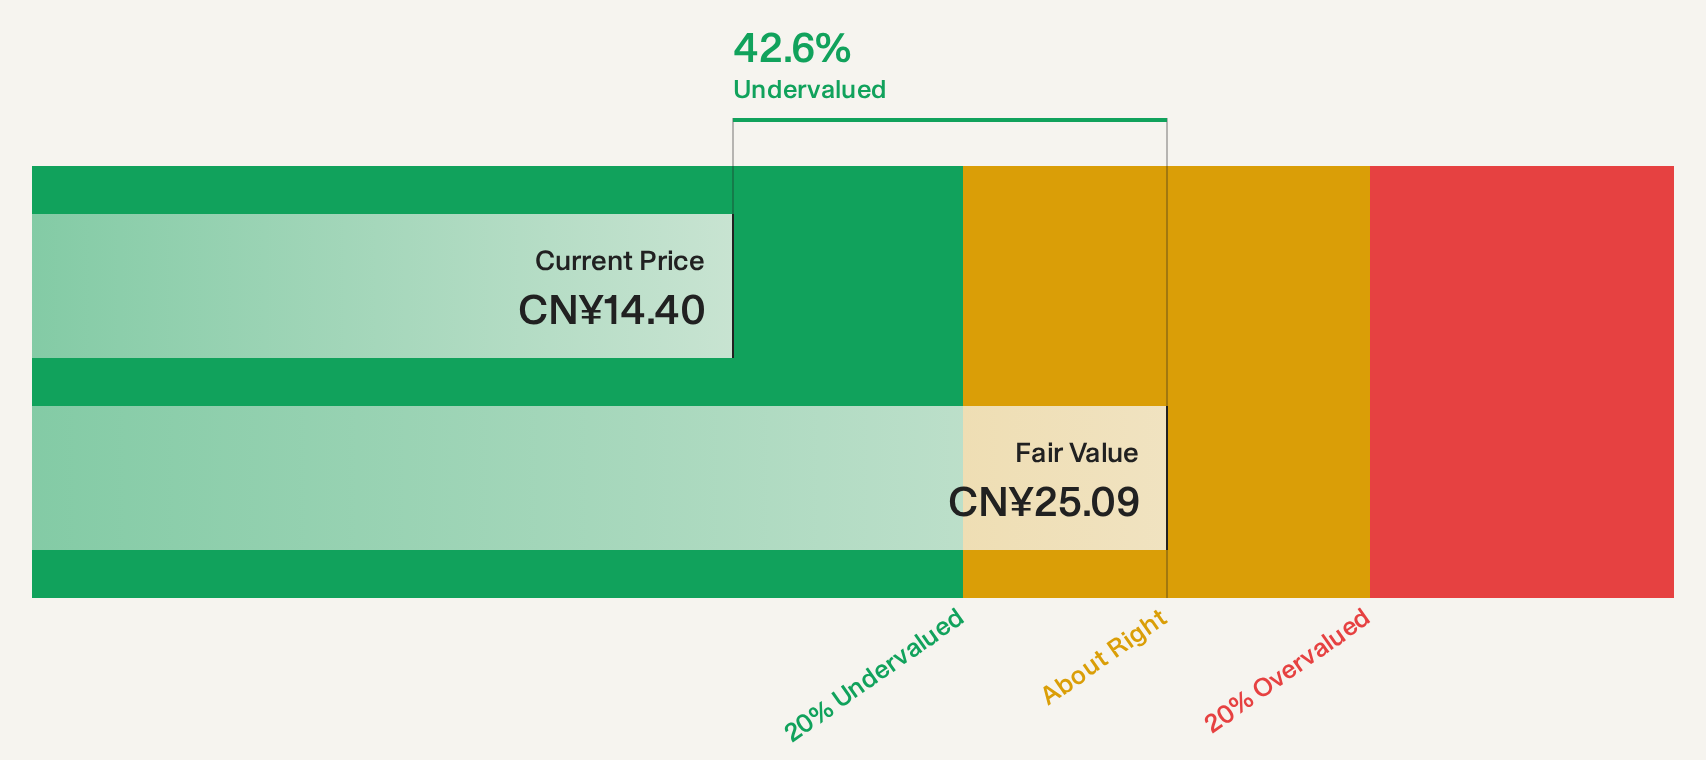
Estimated Discount To Fair Value: 43%
Southern Publishing and Media Ltd. trades at CN¥14.28, significantly below its estimated future cash flow value of CN¥25.05, indicating strong undervaluation based on discounted cash flows. Despite a modest earnings growth forecast of 2.2% annually, the company offers a reliable dividend yield of 3.92%. Recent earnings show net income rising to CN¥1,078.16 million from CN¥850.62 million year-over-year, supporting its good relative value compared to peers and industry standards.
- The growth report we've compiled suggests that Southern Publishing and MediaLtd's future prospects could be on the up.
- Navigate through the intricacies of Southern Publishing and MediaLtd with our comprehensive financial health report here.
Shantui Construction Machinery (SZSE:000680)
Overview: Shantui Construction Machinery Co., Ltd. manufactures and sells construction machinery products both in China and internationally, with a market cap of CN¥13.53 billion.
Operations: The company generates revenue from two main segments: Commercial Product Sales amounting to CN¥164.76 million and Sales of Industrial Products totaling CN¥14.64 billion.
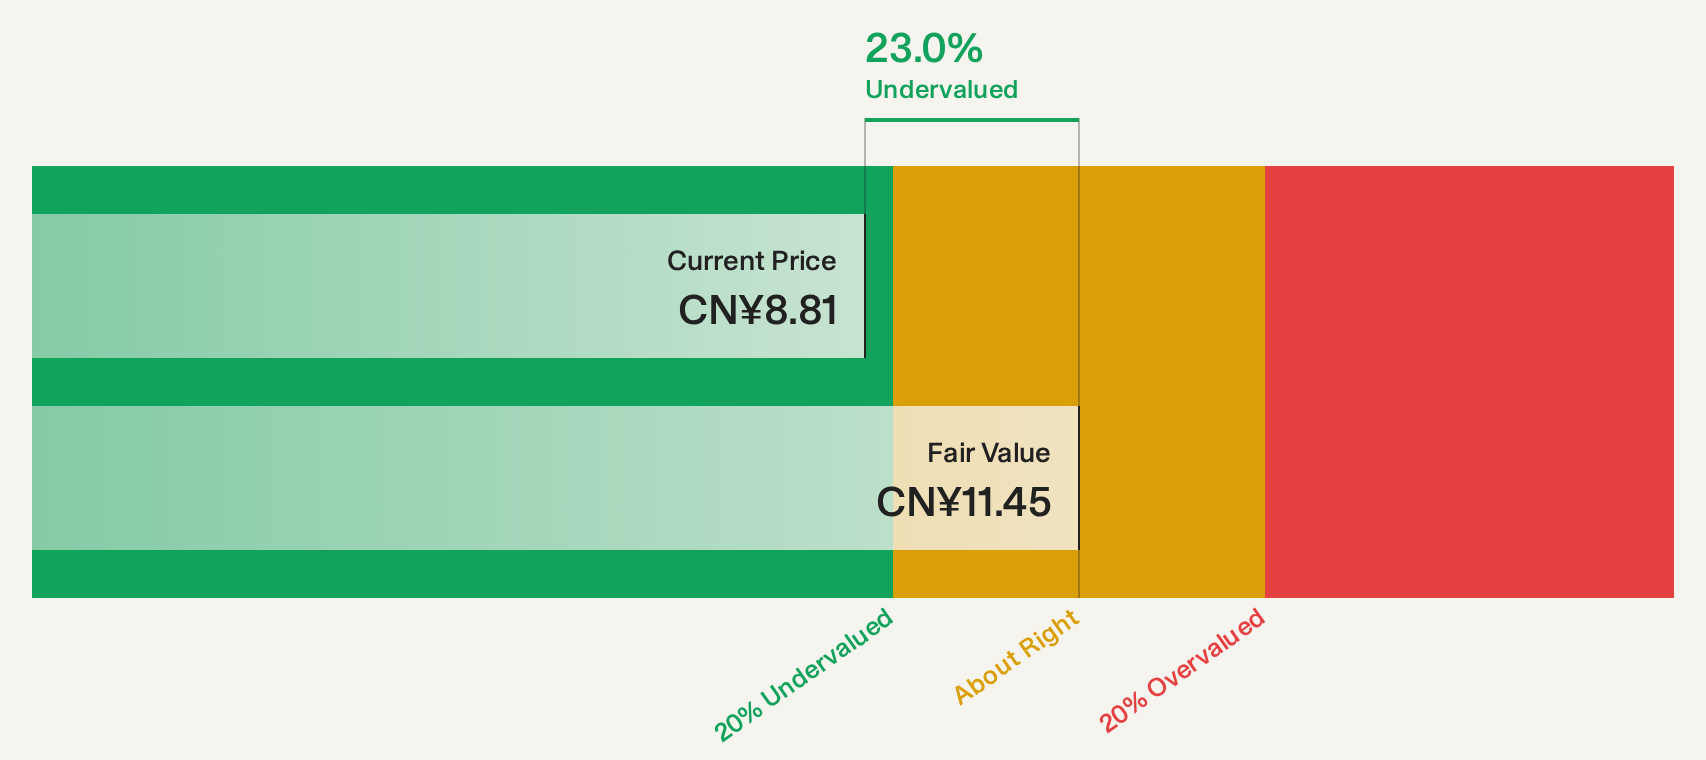
Estimated Discount To Fair Value: 20.6%
Shantui Construction Machinery is trading at CN¥9.11, notably below its estimated future cash flow value of CN¥11.47, showcasing substantial undervaluation based on discounted cash flows. With earnings expected to grow significantly at over 20% annually, the company presents a compelling investment case despite slower revenue growth compared to the broader market. Recent interim profit distribution and board changes highlight ongoing corporate activities amidst steady financial performance improvements year-over-year in sales and net income.
- Our growth report here indicates Shantui Construction Machinery may be poised for an improving outlook.
- Get an in-depth perspective on Shantui Construction Machinery's balance sheet by reading our health report here.
Amoy Diagnostics (SZSE:300685)
Overview: Amoy Diagnostics Co., Ltd. focuses on the research, development, production, sale, and support services of tumor precision medical diagnostic products both in China and internationally with a market cap of CN¥7.44 billion.
Operations: Amoy Diagnostics generates revenue through its involvement in the research, development, production, sale, and support services of precision medical diagnostic products for tumors across domestic and international markets.
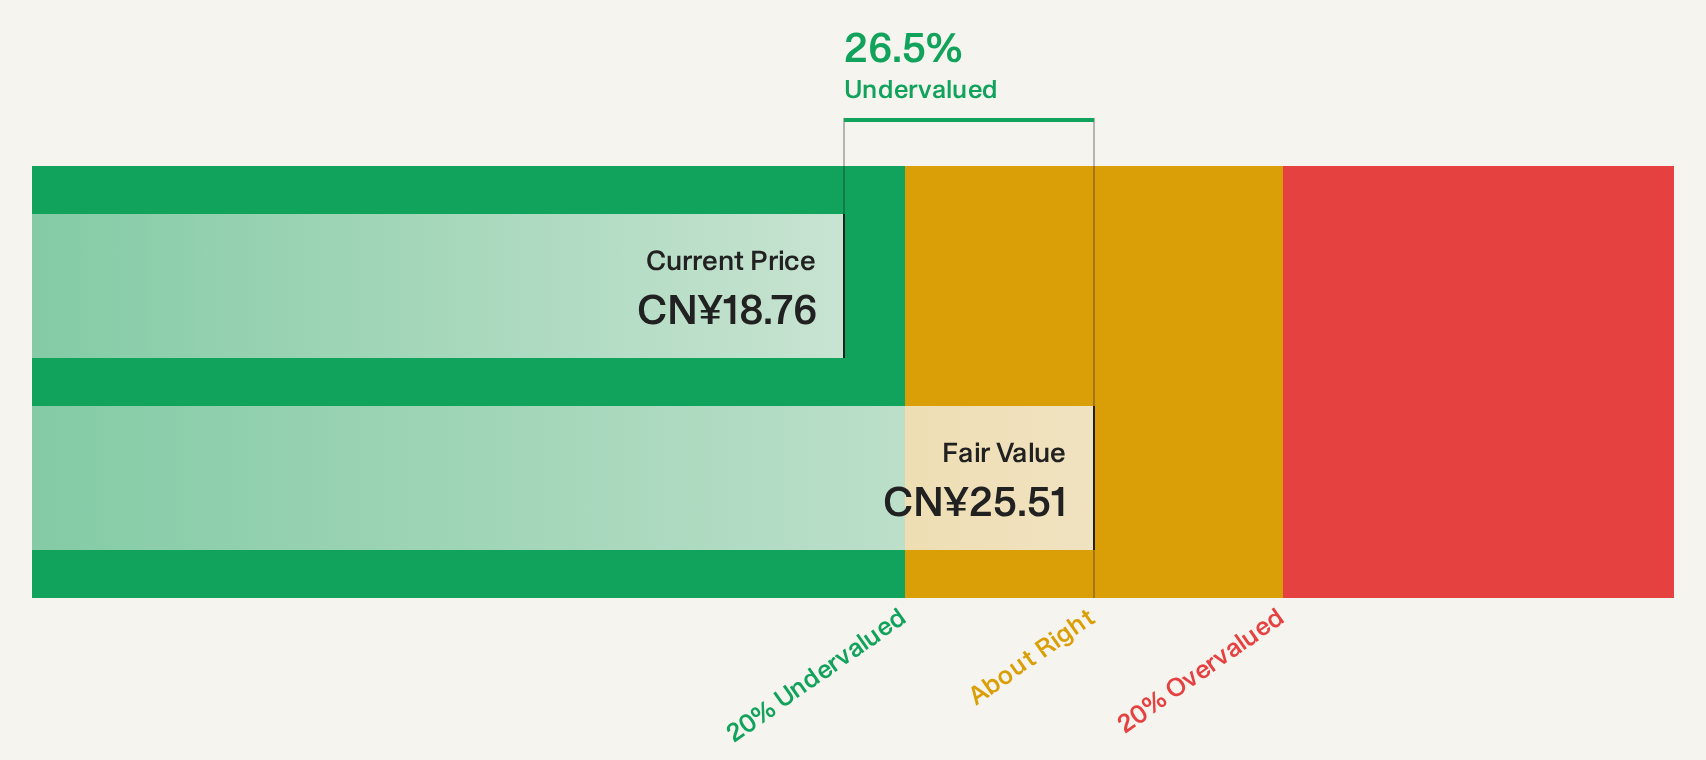
Estimated Discount To Fair Value: 23.4%
Amoy Diagnostics is trading at CN¥20.48, significantly below its estimated future cash flow value of CN¥26.73, indicating undervaluation based on discounted cash flows. Despite slower forecasted revenue and earnings growth compared to the Chinese market, the company maintains good relative value against peers. Recent earnings reports show stable sales but a slight decline in net income year-over-year, while a completed share buyback program reflects strategic capital management efforts amidst modest financial performance trends.
- Our earnings growth report unveils the potential for significant increases in Amoy Diagnostics' future results.
- Take a closer look at Amoy Diagnostics' balance sheet health here in our report.
Seize The Opportunity
- Click through to start exploring the rest of the 254 Undervalued Global Stocks Based On Cash Flows now.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com