
Elite Australian Small Cap Stocks To Own In October 2026
Central banks are hinting at tighter policy again, which tends to reward businesses with solid balance sheets and real earnings power instead of hype. That backdrop can be a gift for Australian small caps that already have strong fundamentals but little analyst coverage. This article breaks down three high quality, under followed stocks from our screener and explains why patient investors may want them on the watchlist now.
The three stocks featured below are only a sample, as the full screen surfaced 12 more small caps with similarly detailed stories that are not covered in this article. To identify potential high conviction ideas that fit your style, head straight into the High-Quality Undiscovered Gems screener
Emerald Resources (ASX:EMR)
Overview: Emerald Resources is an Australian miner focused on exploring and operating gold deposits, anchored by its 100% owned Okvau Gold Project in Cambodia.
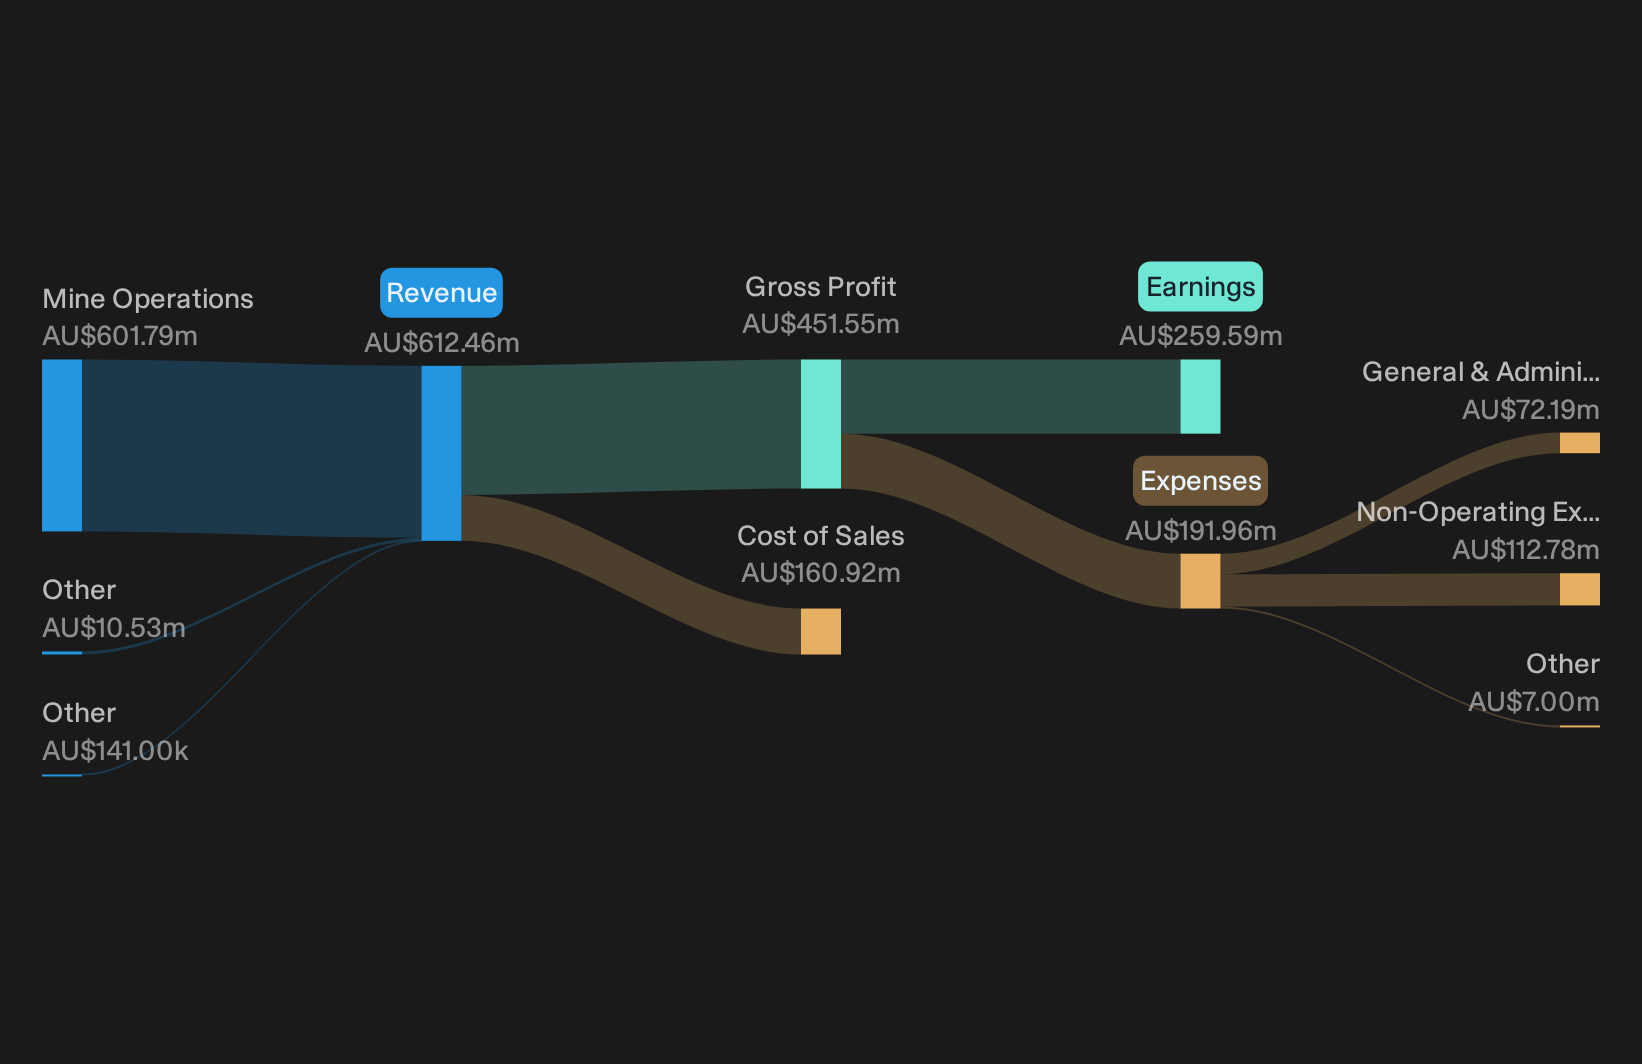
Operations: The business generates about A$602 million from Mine Operations and A$11 million from Other activities, with roughly A$609 million earned in Cambodia.
Market Cap: A$3.83b
Emerald Resources gives you pure exposure to the Okvau Gold Project, with A$612.32 million in FY2026 sales and A$259.59 million in net income already flowing from this once under the radar asset. For a theme built around under owned quality, the key question is how that 42.4% net margin holds up if a single key assumption breaks.
If that margin durability is the real question, start with the Emerald Resources financial health report to see how Emerald Resources’ balance sheet and cash flows line up against that risk.
Australian Ethical Investment (ASX:AEF)
Overview: Australian Ethical Investment runs values based equity, fixed income and balanced funds, with a strong focus on under owned small cap opportunities.
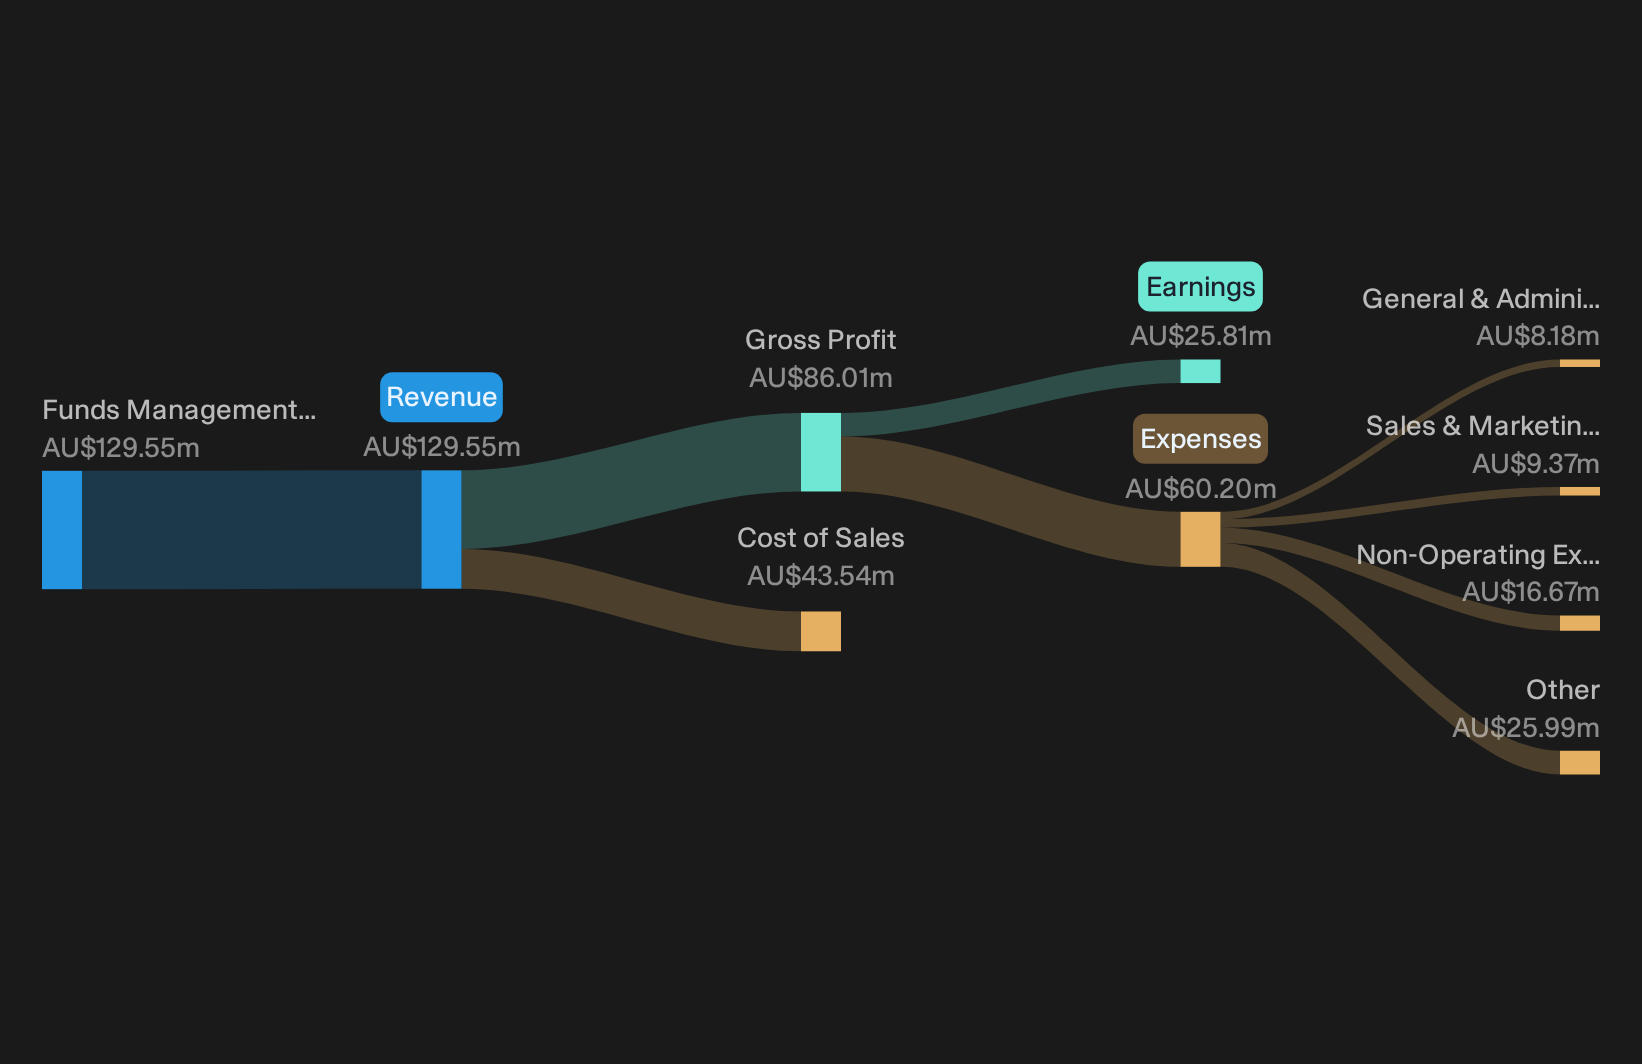
Operations: The group earns A$129.55 million from funds management, entirely sourced from Australian clients whose capital is allocated across its managed portfolios.
Market Cap: A$476 million
Australian Ethical Investment fits this screener because it channels capital into under researched small caps through its active funds, linking investors directly to the kind of under owned opportunities big institutions often overlook.
"Growing preference for ethical investment continues to support Australian Ethical Investment, with rising interest from NGOs, charities, foundations and family offices and an estimated A$50b Australian foundation pool. This segment may influence net inflows and revenue outcomes if a larger share allocates to values aligned products."
The real test is how one still developing revenue mix might affect future fee margins if a single key assumption about client behaviour shifts.
That client mix risk is exactly what the full narrative for Australian Ethical Investment unpacks, showing where Australian Ethical Investment could see inflows accelerate, stall or quietly decouple from peers.
EDU Holdings (ASX:EDU)
Overview: EDU Holdings runs higher education and vocational colleges in Australia through Ikon and Australian Learning Group, teaching in demand human services and care qualifications.
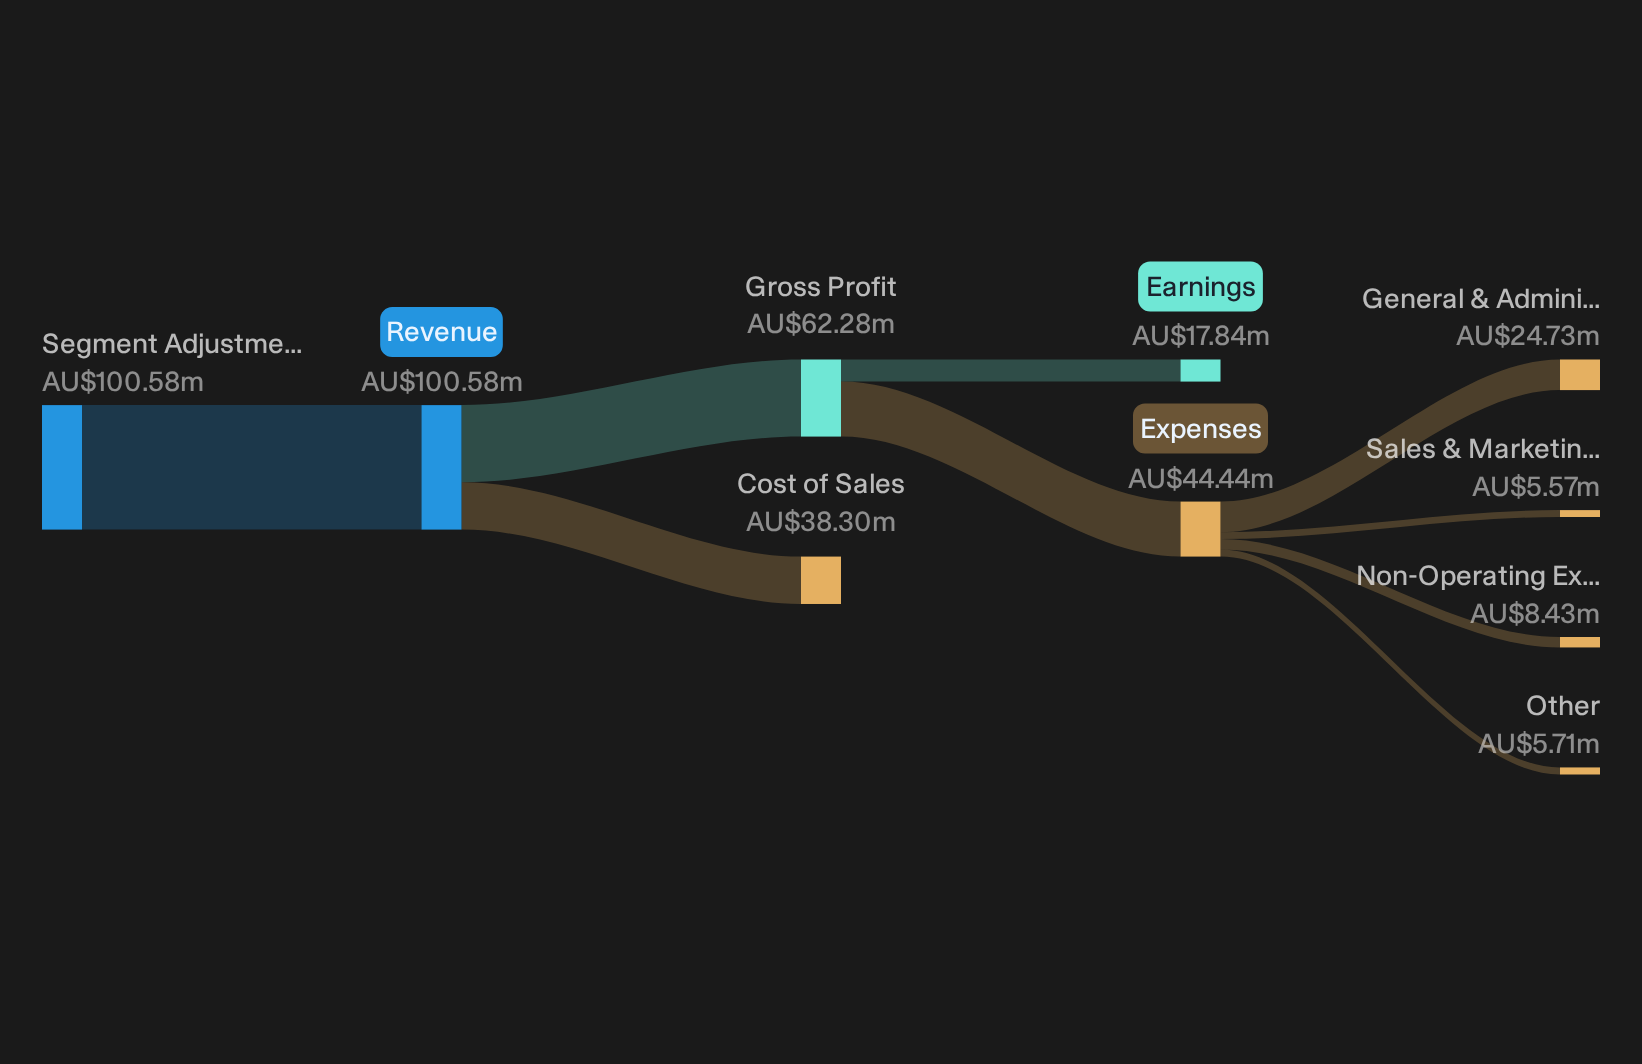
Operations: EDU Holdings generates about A$100.6 million in revenue, almost entirely from Australian education services across its higher education and vocational offerings.
Market Cap: A$101 million
EDU Holdings fits this High Quality Undiscovered Gems theme because its Ikon and ALG programs convert very specific skill shortages into fee paying enrolments that larger funds still treat as a niche education story.
"The single biggest risk is regulatory. A minister can wake up tomorrow and decide private education providers are politically inconvenient."
Whether EDU Holdings continues quietly or encounters a setback may depend on how one policy driven pressure affects margins.
That policy risk is where the story gets interesting, and the full narrative for EDU Holdings shows how EDU Holdings could still compound value if funding rules tighten again.
Seeking Alternatives Before Momentum Flies
Fresh opportunities do not stay quiet for long. Once momentum hits, entries get harder, spreads widen and mispricing shrinks. Scan these under the radar lists while it matters and get in early.
- Spot resilient cash generators before they are fully appreciated by the crowd by scanning the list of solid balance sheet and fundamentals (12 results) and lining up potential watchlist additions ahead of the next breakout.
- Track where future income streams might come from by reviewing the 4 dividend fortresses that focuses on higher yielding businesses before yields get compressed by later buyers chasing the same story.
- Position around long term infrastructure themes by working through the 42 power grid technology and infrastructure stocks while these under followed operators are still pricing in older assumptions instead of fresh demand expectations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com