
Plains GP Holdings (PAGP) Stock Trades At A Discount To Its Sales
Plains GP Holdings has put up a striking share price run in recent years, which naturally raises the question of whether the current valuation is supported by its sales base. For anyone looking at the stock today, the key issue is how that trading history lines up with the revenue it generates.
- Over the past 5 years, Plains GP Holdings has returned about 255.8%, which puts real weight on whether its sales can carry the market value now attached to the business.
- The partnership structure and midstream model mean cash flows lean heavily on volumes and contract terms, so expectations for how those translate into revenue can shape what investors are willing to pay for each dollar of sales.
- The analysts covering Plains GP Holdings have run their own numbers. See what analysts think Plains GP Holdings's shares could be worth.
The issue now is whether the price investors see on screen today is justified by the sales that Plains GP Holdings produces.
If you want to test the same sales based valuation question across more than just Plains GP Holdings, line it up against 28 high quality undervalued stocks.
Is Plains GP Holdings Still Cheap on Sales?
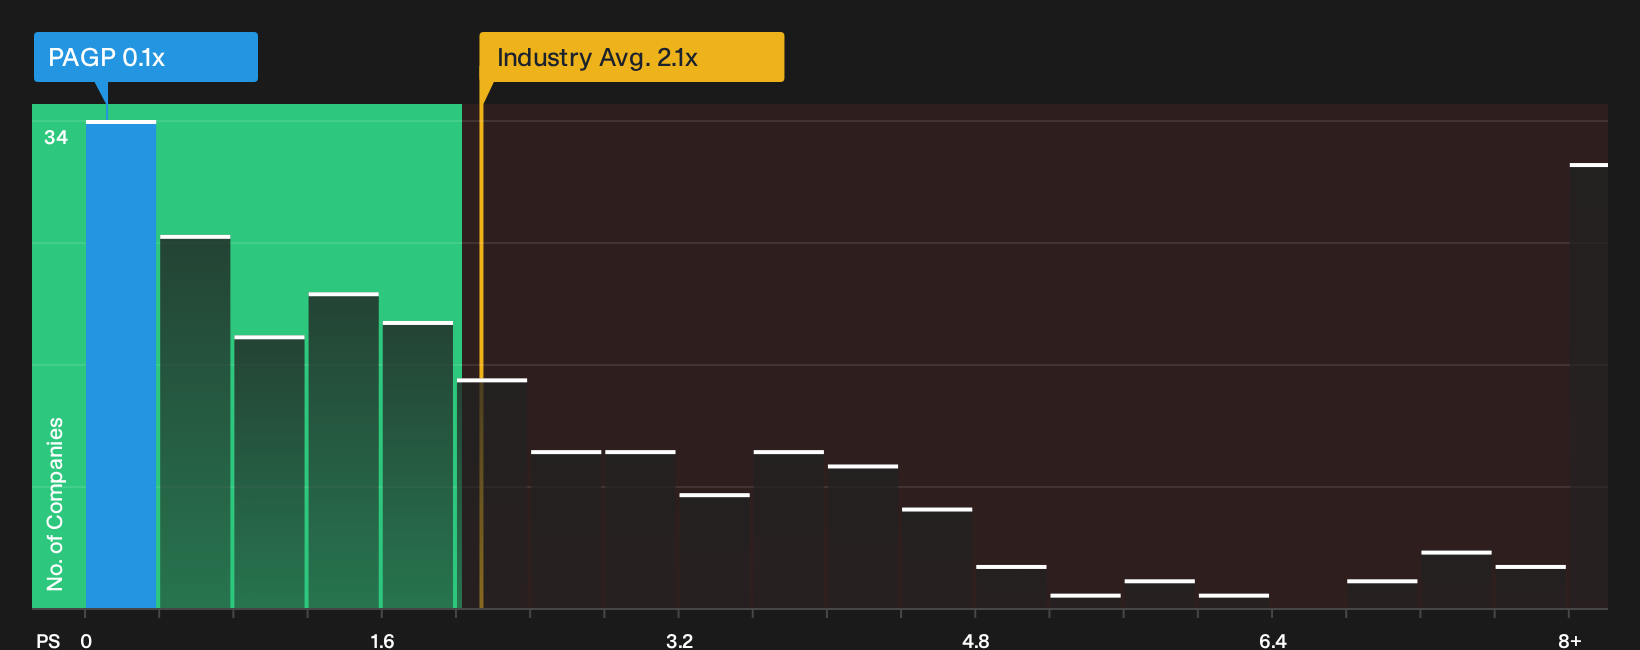
P/S tends to fit Plains GP Holdings because investors often focus on how much revenue the partnership can run through its pipelines rather than on accounting earnings. On this yardstick, the current P/S of about 0.1x is far below the broader oil and gas industry average of roughly 2.1x, and it also sits well under the peer group near 3.8x. For every dollar of sales, the equity market is only assigning a small fraction of the revenue multiple seen across similar businesses.
The Fair Ratio, which adjusts for factors like margins, size and risk, also points to a higher P/S than the one attached to Plains GP Holdings right now. That gap suggests the market is applying a steep discount to its top line and is pricing in heavier risks or weaker economics than the model assumes. Long term investors will want to weigh that against their own view of the partnership’s cash generation and contract quality. Explore the numbers behind Plains GP Holdings's P/S valuation.
The Plains GP Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this Plains GP Holdings valuation puzzle leaves off by spelling out what kind of future growth, margins and earnings path would need to occur for the current share price to look materially higher or lower than it does today, and they sit on Simply Wall St's Community page. Rather than relying on a single multiple or model output, each scenario explains the key assumptions behind its fair value so you can later compare those expectations with the figures Plains GP Holdings' management actually reports.
Bulls see more running room in Plains GP Holdings than the more cautious camp, which views the current setup as largely reflected in the price.
Bull case: roughly fairly valued
"Management expects about US$1.75b to US$1.85b of adjusted free cash flow in 2026 and has lowered the targeted distribution coverage threshold to 150%..."
Discover why this Narrative puts Plains GP Holdings at roughly fairly valued.
Bear case: 8% overvalued
"The current valuation suggests Plains GP Holdings is fairly valued, with the market already accounting for a stable crude-focused portfolio, targeted $0.15 per unit annual distribution increases and a conservative 150% coverage ratio..."
Explore why this Narrative puts Plains GP Holdings at 8% overvalued.
For Plains GP Holdings, the share price is only one piece of the puzzle
Before you stop at the valuation, you need to look at who is steering Plains GP Holdings and how their rewards line up with your interests. See who runs Plains GP Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com