
Is McGrath RentCorp (MGRC) Above Fair Value on Earnings?
McGrath RentCorp has delivered a solid long run for shareholders, and the current share price of US$117.16 now puts the focus squarely on what its earnings justify. With that backdrop, the question is whether the market price still lines up with what the business is earning today.
- Over the past 5 years the stock has returned 74.0%, which makes it important to ask if that share price journey is still backed by the underlying profit stream.
- The rental-focused business model depends heavily on asset utilization and pricing discipline, so any change in equipment demand or rental margins can shift how comfortably earnings support the current valuation.
- The analysts covering McGrath RentCorp have run their own numbers. See what analysts think McGrath RentCorp's shares could be worth.
The stock's next move may depend on whether McGrath RentCorp's current earnings are strong enough to justify where the shares trade today.
If you want to stress test this same earnings question across a wider set of businesses, scan through the 28 high quality undervalued stocks for potential ideas that fit your framework.
Is McGrath RentCorp Getting Expensive on Earnings?
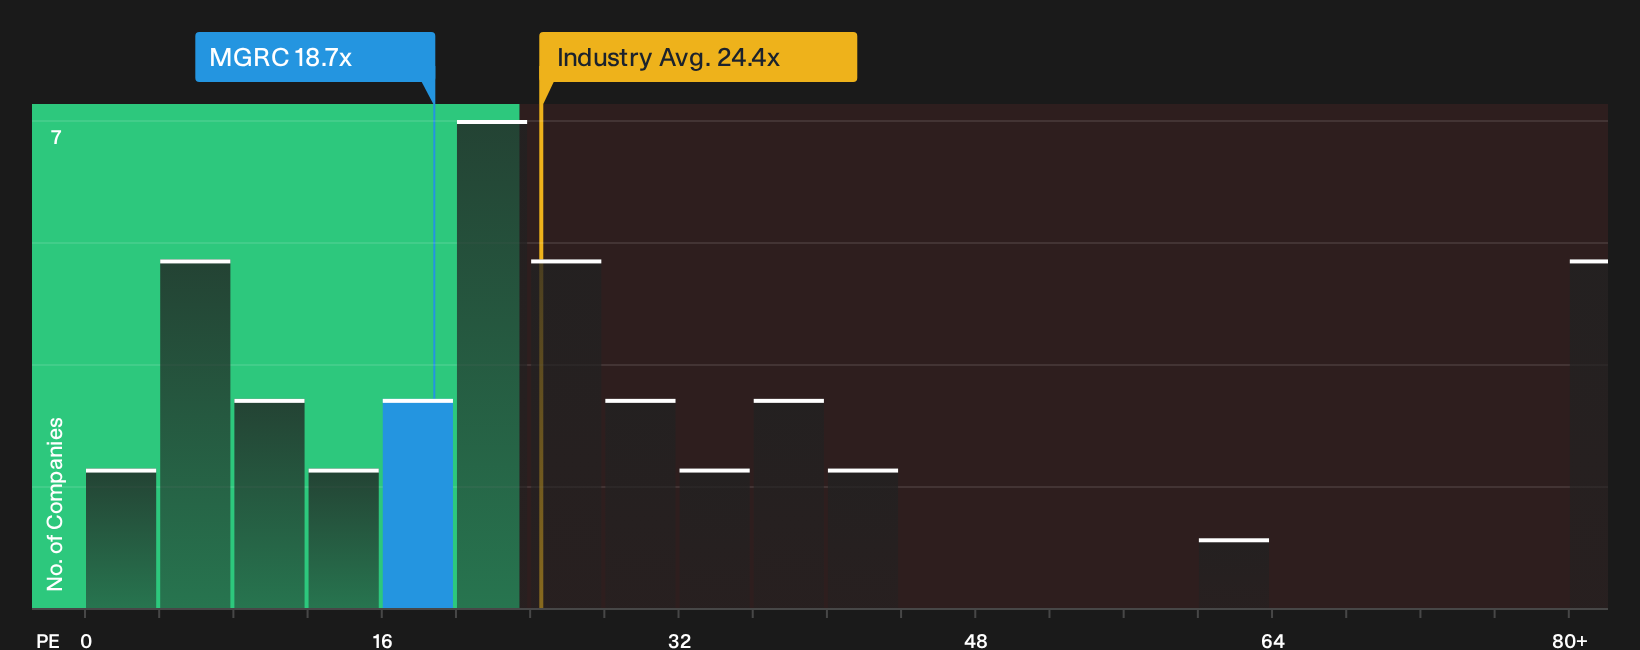
The P/E ratio is a useful lens for McGrath RentCorp because earnings are a core driver for a rental-heavy operation. At the current share price, the stock trades on a P/E of 18.7x, which sits below the Trade Distributors industry average of 24.4x and well under the broader peer group at 43.9x. That gap indicates the market is assigning a lower price tag to each dollar of McGrath RentCorp's profit than to many comparable businesses.
A tailored fair multiple that blends the company’s growth profile, profitability, size and risk suggests McGrath RentCorp’s current 18.7x P/E is above what those fundamentals would typically justify, so the shares screen overvalued on this framework even though they trade at a discount to peers. For an investor, the key question is whether the quality and durability of the earnings stream are strong enough to support paying a premium to that fair level while still accepting a lower headline multiple than many industry comparables. Explore the numbers behind McGrath RentCorp's P/E valuation.
The McGrath RentCorp Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for McGrath RentCorp leaves off by explaining which paths for revenue growth, profit margins and earnings would need to unfold for the current share price to look materially higher or lower over time. Instead of stopping at one headline valuation number, they unpack the future that figure rests on so you can see what to watch and follow those assumptions on the Community page as new information arrives.
One of the top community narratives on McGrath RentCorp: 19% undervalued
"The main thing that has to go right is that Mobile Modular and TRS-RenTelco continue to convert early traction in expansion markets..."
Discover why this Narrative puts McGrath RentCorp at 19% undervalued.
McGrath RentCorp’s valuation still hinges on one unresolved factor
Price and earnings only tell part of the story, because the people setting priorities, taking capital decisions and rewarding themselves can heavily shape future outcomes for shareholders. See who runs McGrath RentCorp and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com