
China Life Stock Still Looks Cheap but Can Earnings Justify Its Low P E
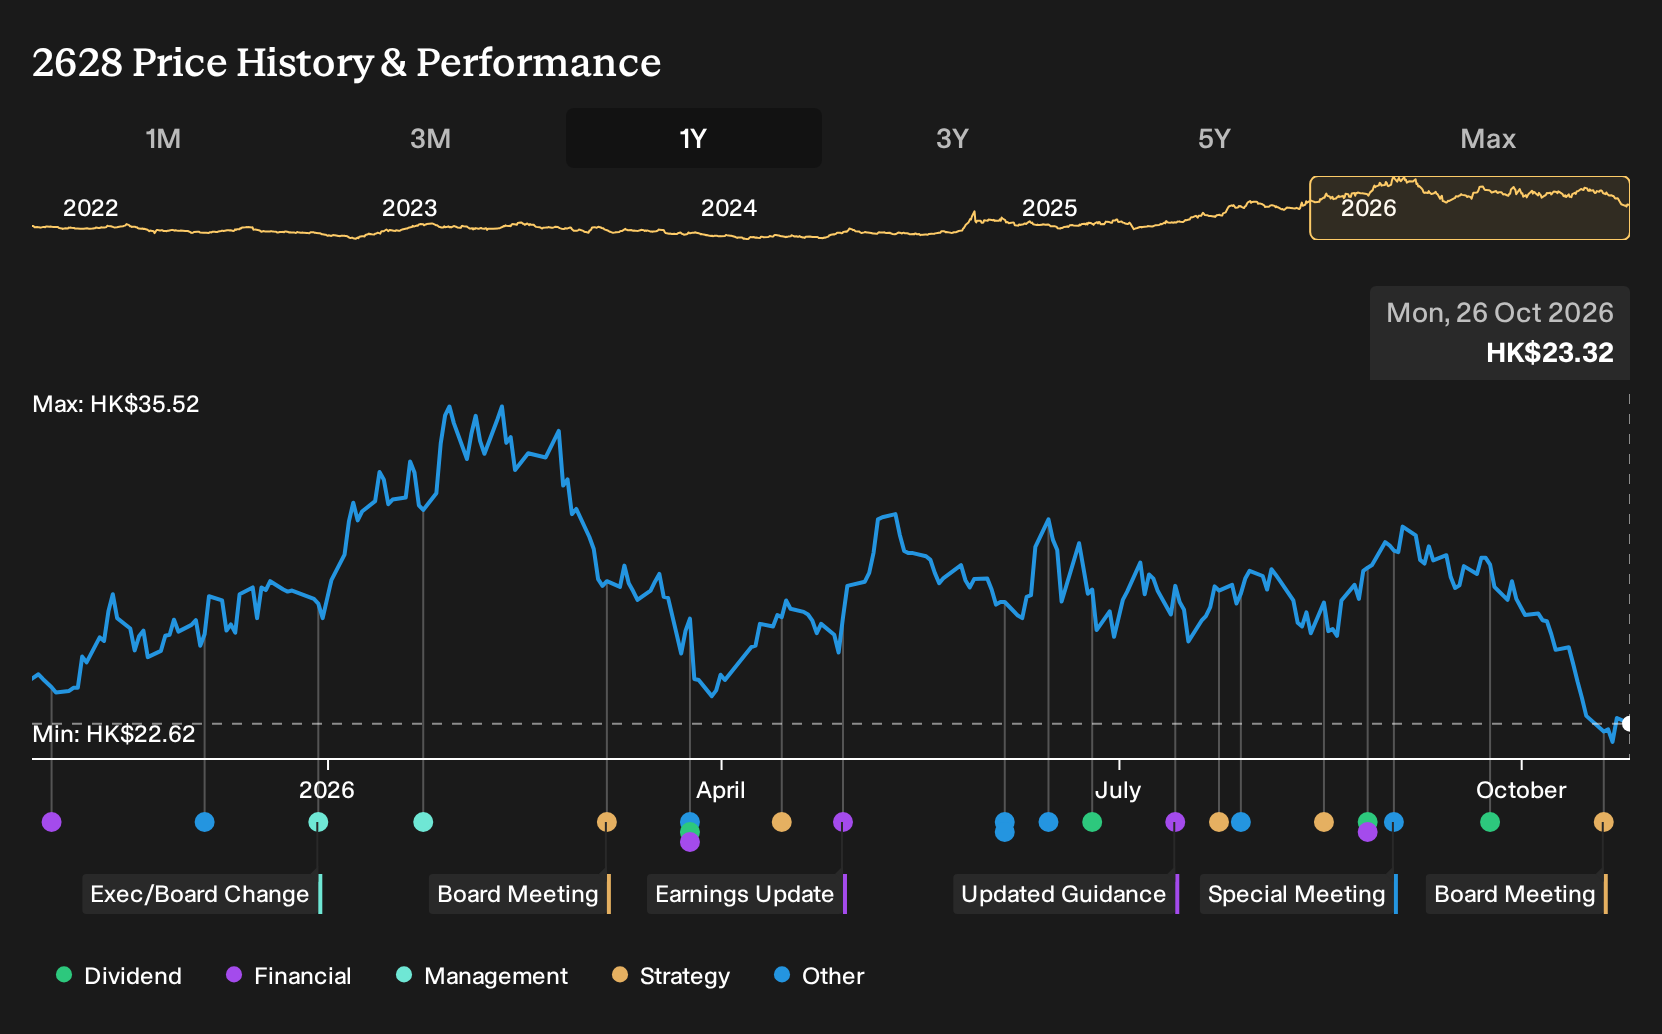
- China Life Insurance has drawn fresh attention after a period of strong past share price performance while still trading on a P/E ratio that remains well below many industry peers, putting its earnings power under a microscope.
- The debate now centres on whether the insurer’s profitability, value of new business, and large 644,000 strong agent force can support this valuation gap, given earlier pressure on operating income, net profit, EPS and ROE.
- We will now look at how China Life Insurance's low P/E valuation relative to peers could influence the broader investment narrative.
Compare China Life Insurance with a curated basket of insurers and financials that also screen as potential value opportunities through the 195 high quality undervalued stocks.
China Life Insurance Investment Narrative Recap
To own China Life Insurance, you need to believe its push into higher margin products and its 644,000 strong agent force can keep turning solid value of new business into durable earnings. The recent share price pullback mostly affects sentiment rather than operations. The key near term swing factor is still whether revenue growth converts into stable net margins.
The biggest risk right now is that strong gross written premiums and high reported net profit margins do not hold up if claims, costs or investment income move against the insurer. Volatile investment returns and taxation related losses, as seen in Q1 2026, remain important pressure points for earnings quality.
The most relevant recent disclosure is the Q1 2026 solvency report, where China Life Insurance highlighted full compliance with updated Chinese solvency and risk rules. That matters because strong regulatory capital gives the insurer room to keep reshaping its product mix toward higher margin policies without immediately constraining growth.
Compliance also links directly to catalysts investors are watching. Flexibility on capital allocation can support the shift toward more profitable products and the productivity push across the agent base, while still absorbing periods of weaker investment income or earnings volatility if those risks flare again.
What The Current Forecasts Assume For China Life Insurance
China Life Insurance's current analyst narrative points to CN¥787.1b in revenue and CN¥120.0b in earnings by 2029. That profile is built on forecast revenue growth of 19.9% each year and a drop in earnings of CN¥127.6b from CN¥247.6b today.
Uncover why China Life Insurance's fair value indicates a 56% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
The Simply Wall St Community has supplied 2 fair value views on China Life Insurance, stretching from CN¥36.49 to CN¥124.35. That spread shows that expectations vary widely. When you also consider risks around claims costs, investment income and taxation impacts, you can end up with very different stories for future earnings power. Explore those competing viewpoints before forming your own stance.
Explore another China Life Insurance fair value estimate, including one that suggests it could be worth just HK$36.49!
Decide For Yourself
Disagree with existing narratives? Extraordinary outcomes rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your China Life Insurance research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for China Life Insurance. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate China Life Insurance's overall financial health at a glance.
Looking For More Investment Ideas Beyond China Life Insurance?
If the China Life Insurance story has sharpened your view on value, income and risk, broaden your watchlist by scanning a wider field of opportunities using the Simply Wall St Screener.
- For investors hunting for mispriced quality, review a curated 195 high quality undervalued stocks that combine robust fundamentals with appealing valuations.
- If reliable income is your priority, filter for companies that emphasise resilience in their payouts through the 226 dividend fortresses.
- For those who care most about balance sheet strength, focus on businesses with disciplined finances using the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com