
Why Casio ComputerLtd Doubters Were Wrong Before An 89% Gain
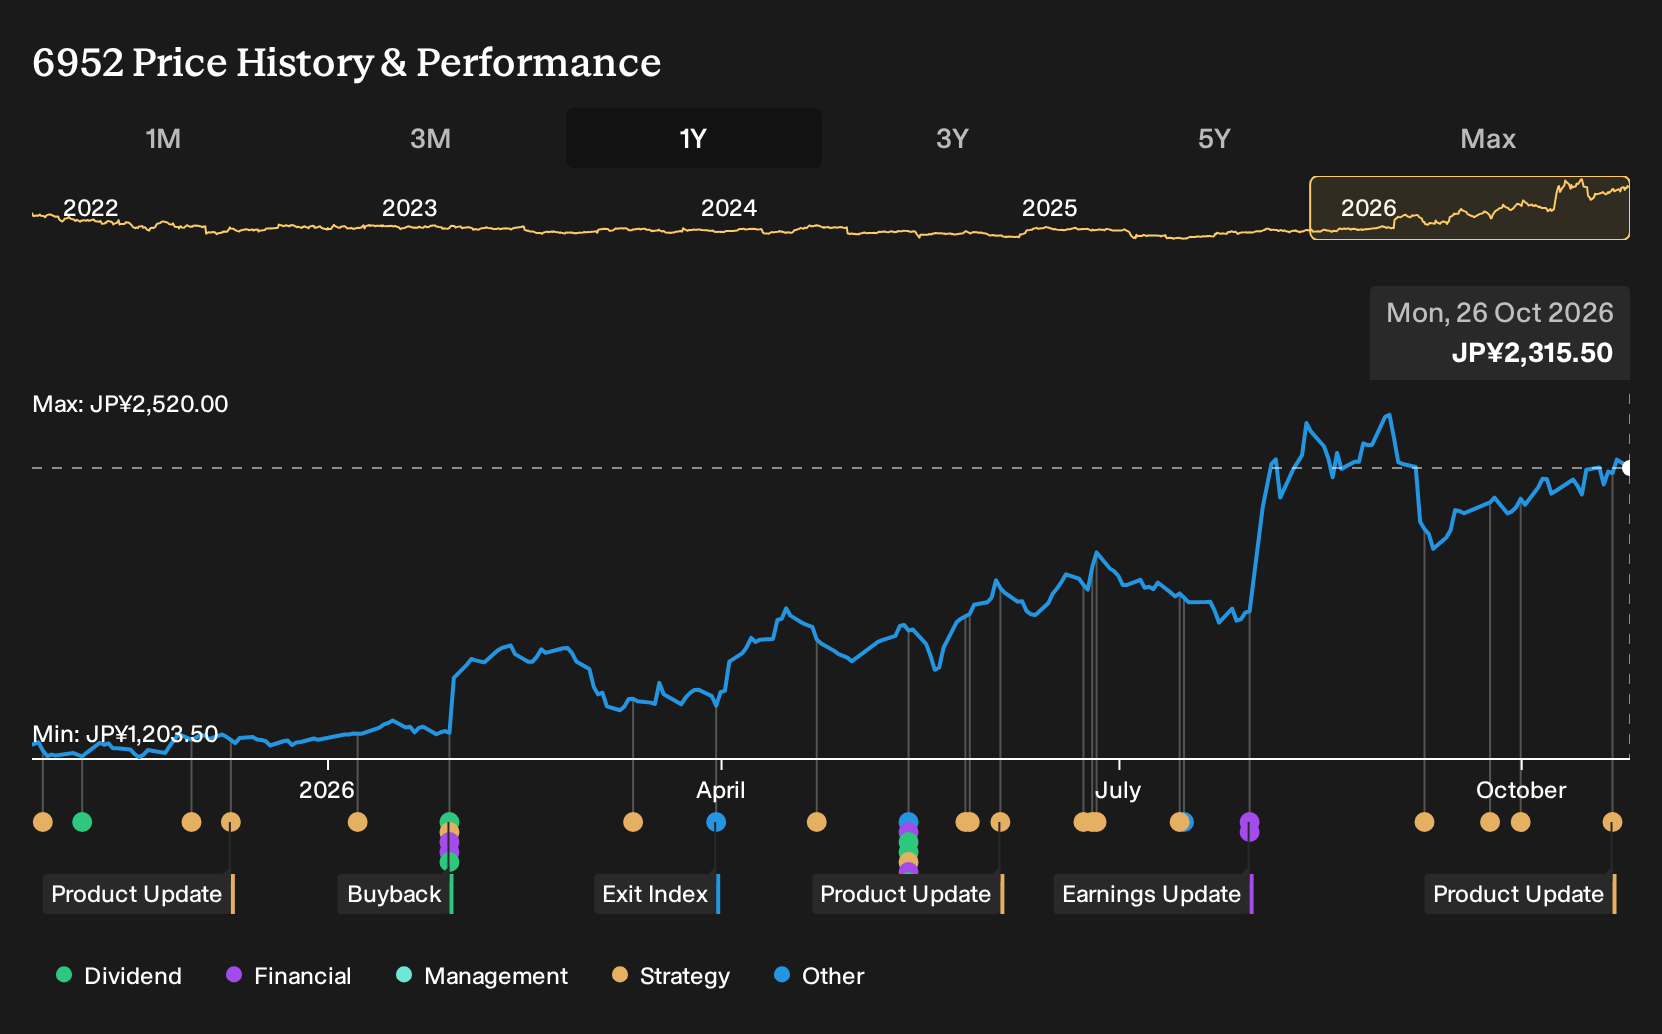
The latest headline for Casio ComputerLtd was not a blockbuster acquisition or a surprise profit warning, but a fresh twist on its core G-SHOCK line with the new analog 2500 series and a cluster of limited editions, collaborations, and sensor packed sports models. For Casio ComputerLtd shareholders, the return over the past year was 88.5%, including dividends. If you were deciding back on 26 October 2025, what would you have needed to believe about these launches and the Timepieces segment to press “buy” before any of that payoff was visible?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Casio ComputerLtd harder to judge, start where the gap is still open and scan 14 high quality undervalued stocks.
The Argument Casio Investors Were Actually Weighing
The shares cost ¥1,239 at the start, and anyone looking at Casio ComputerLtd then was really choosing between two very different but plausible stories.
On the bullish side, the narrative pointed to a fair value of ¥1,700 and leaned on Casio using e-commerce and direct-to-consumer sales more aggressively, especially in higher margin education and music technology products.
The bearish view anchored fair value at ¥1,070 and focused on accelerating substitution of watches and calculators by smartphones, with digital tools threatening core educational hardware and long term profits.
What The Results Changed For Casio ComputerLtd
The launch of the analog G-SHOCK 2500 series, the GRAVITYMASTER GWRB3000 line, and sensor heavy G-LIDE models gave bulls fresh product proof for Casio ComputerLtd’s Timepieces story. A new Pink Ribbon model and J Balvin collaboration also underlined brand reach. Reported Q1 2027 revenue of ¥74,511m and net income of ¥9,377m, with net margin rising to 12.6%, supported the optimistic case on profitability.
The useful takeaway is clear. When a thesis hinges on higher margin lines doing more of the heavy lifting, track segment rich launches alongside net margin in later filings and check whether the mix shift shows up in that single figure.
What Casio’s Current Price Already Assumes
Casio ComputerLtd shares now trade at ¥2,316, after an 88.5% gain over the past year. The selected Narrative’s Fair Value sits below the current price, which frames today’s level as one where the cautious case sees limited cushion if execution disappoints.
That view depends on legacy categories holding up while Timepieces expansion, EdTech, and Sound restructuring carry more weight. A buyer today is effectively assuming those profit ambitions are achieved. This raises the question of how the risk of pressure in China, tariffs, and loss-making segments weighs on that expectation.
"The valuation implies the share price already prices in Casio ComputerLtd achieving its new midterm plan targets, restoring profitability in the Sound business and maintaining high margins and shareholder returns, leaving limited room for disappointment if these goals are not met."
One Narrative disagrees with today's price. → See where this Narrative says Casio ComputerLtd should trade
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 35% below our estimate - monetizes AI driven hiring and local services matching through premium and GMV linked tools.
- Company 2 - 23% below our estimate - adds salespeople to win more maintenance contracts and deepen high margin modernization work.
- Company 3 - 50% below our estimate - shifts toward AI native security platforms where ARR expansion must justify heavier upfront spending.
Three companies from the same screener. Open the full list of 23 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com