
What Talos Energy Holders Bought Into Before An 89% Run
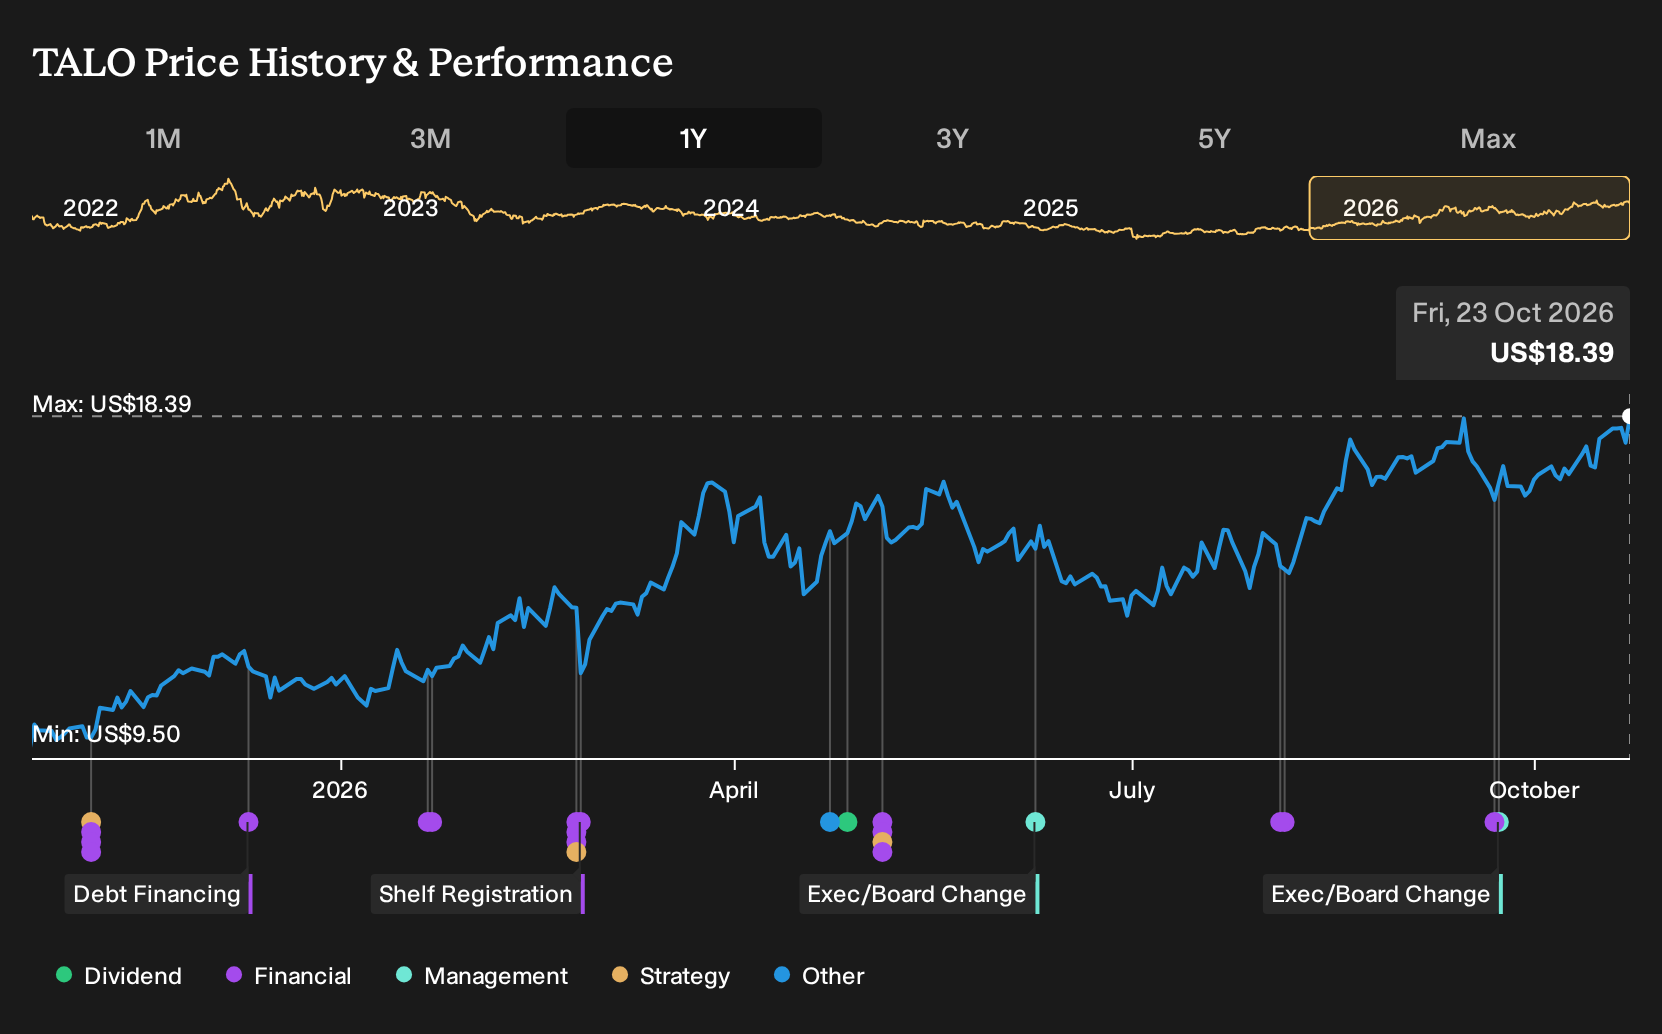
Talos Energy spent the past year juggling sector selloffs, chunky insider sales and a string of bullish headlines about Gulf projects and acquisitions. For Talos Energy shareholders, the return over the past year was 88.8%, including dividends. If you had been weighing those conflicting signals on 23 October 2025, the eventual payoff would have looked anything but obvious. So what exactly in the record at that time justified taking that ride?
The easy part of this move is behind Talos Energy. Zero in on 28 high quality undervalued stocks for companies trading below our estimates.
The Two Talos Energy Stories Investors Had To Weigh
The shares cost US$9.92 at the start of the period, and anyone looking at Talos Energy then faced two very different but plausible stories.
The bullish view pointed to a Fair Value of US$13.17, a price that would only make sense if cost discipline and Gulf of Mexico projects supported recurring free cash flow improvement from a targeted US$100 million per year efficiencies program.
The bearish camp argued for a Fair Value of US$9, based on concerns that heavy Gulf concentration and large decommissioning and exploration costs could keep revenue declining 8.2% a year and delay any benefit from early stage carbon capture activities.
What The Talos Energy Evidence Actually Showed
The clearest development for Talos Energy was the swing from a Q2 2025 loss of US$185.9 million to a Q2 2026 profit of US$149.7 million, with net margin moving from a loss of 43.8% to a 22.5% profit. That shift, together with acquisitions of producing Gulf assets and the Block 29 farm in offshore Mexico, largely supported the optimistic cost discipline story.
The key lesson is simple. When a thesis hangs on efficiency and capital allocation, track net margin and free cash flow against past guidance rather than letting production headlines do the talking.
What Talos Energy's Price Already Assumes
Talos Energy now trades at US$18.39, and the selected Narrative places its Fair Value above that mark. The gap reflects a belief that the offshore portfolio and capital return plans are stronger than the current quote implies.
For any buyer today, the key judgment is whether Talos can keep turning Gulf, Mexico and Honduras projects into profitable barrels while holding costs and leverage to plan.
"The main factor that has to go right is that Talos Energy continues to convert its Gulf of America acquisition, Mexico Block 29 farm-in, and Honduras exploration entry into profitable production while holding operating costs and leverage at targeted levels."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Talos Energy’s Story Connects
Talos Energy focuses on exploring and producing hydrocarbons offshore for its customers.
One step away, another business concentrates on transporting those molecules between key regions.
It runs long networks that move gas, liquids and crude to major hubs.
Power plants and data centers depend on its pipes and storage to keep fuel available.
Export facilities connected to this system handle cargos heading overseas, leaving that quieter infrastructure story sitting alongside Talos in a portfolio.
One Narrative has already put a figure on it. → Uncover the company trading 16% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com