
Airbnb (ABNB) Stock May Be 41% Undervalued Despite New Travel Partnership
Airbnb has delivered strong multi year gains for shareholders, and the question now is whether the current US$172.01 share price lines up with the cash the business is expected to generate. With the spotlight back on travel and a new partnership with American Express broadening its reach, the key issue is how much of that story is already reflected in the valuation.
- The stock is up 47.1% over the past 3 years, which puts real weight on whether the cash flow narrative can keep backing up that kind of long term return.
- The American Express tie up brings over 1 million Airbnb listings into Amex Travel and may support expectations for higher booking volumes and potentially more robust cash generation over time.
- What if you looked at Airbnb through its earnings instead? See why Airbnb's 37.7x P/E tells a different valuation story.
The issue now is whether Airbnb's recent share price level is adequately supported by the cash flows implied in its intrinsic value estimate.
If you want more context around whether Airbnb's cash flow story and partnership news stack up against other opportunities, it can help to line it up beside 28 high quality undervalued stocks.
Does Airbnb Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Airbnb is forecast to generate for shareholders and then discounts it back to today. On the latest figures, the business produced about $4.9b of free cash flow over the last twelve months, and the projections used in this DCF assume that annual free cash flow grows from that base to several billions of dollars over the coming decade rather than shrinking.
Those cash flow estimates stay in positive territory throughout the forecast window, which aligns with a company already generating several billion dollars of excess cash. Because the projections suggest rising free cash flow per share, the DCF output currently sits substantially above the $172.01 share price. The American Express partnership, which brings Airbnb inventory into Amex Travel, is one factor analysts cite when assessing potential future booking volumes and the associated cash flow profile in this model. Find out what Airbnb could be worth using our Discounted Cash Flow (DCF) estimate.
The Airbnb Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Airbnb pick up where that cash flow puzzle leaves off and explain what would need to happen with growth, margins and earnings for the stock to be worth materially more or less than today’s price on the Community page. Rather than treating one multiple or model result as a final answer, each narrative lays out the specific assumptions behind its fair value so you can track those against Airbnb's actual results over time.
Community views on Airbnb now split between those who see a cash rich platform still mispriced and those who think the quality premium already runs high.
Bull case: 5% undervalued
"They’ve launched long-term rentals, made over 500 product improvements, and are going all-in on AI to make the platform smoother…"
Discover why this Narrative puts Airbnb at 5% undervalued.
Bear case: 8% overvalued
"Major cities have introduced regulations limiting short-term rentals, capping listings, or imposing compliance requirements on hosts…"
Explore why this Narrative puts Airbnb at 8% overvalued.
One more Airbnb signal that could change how you read the story
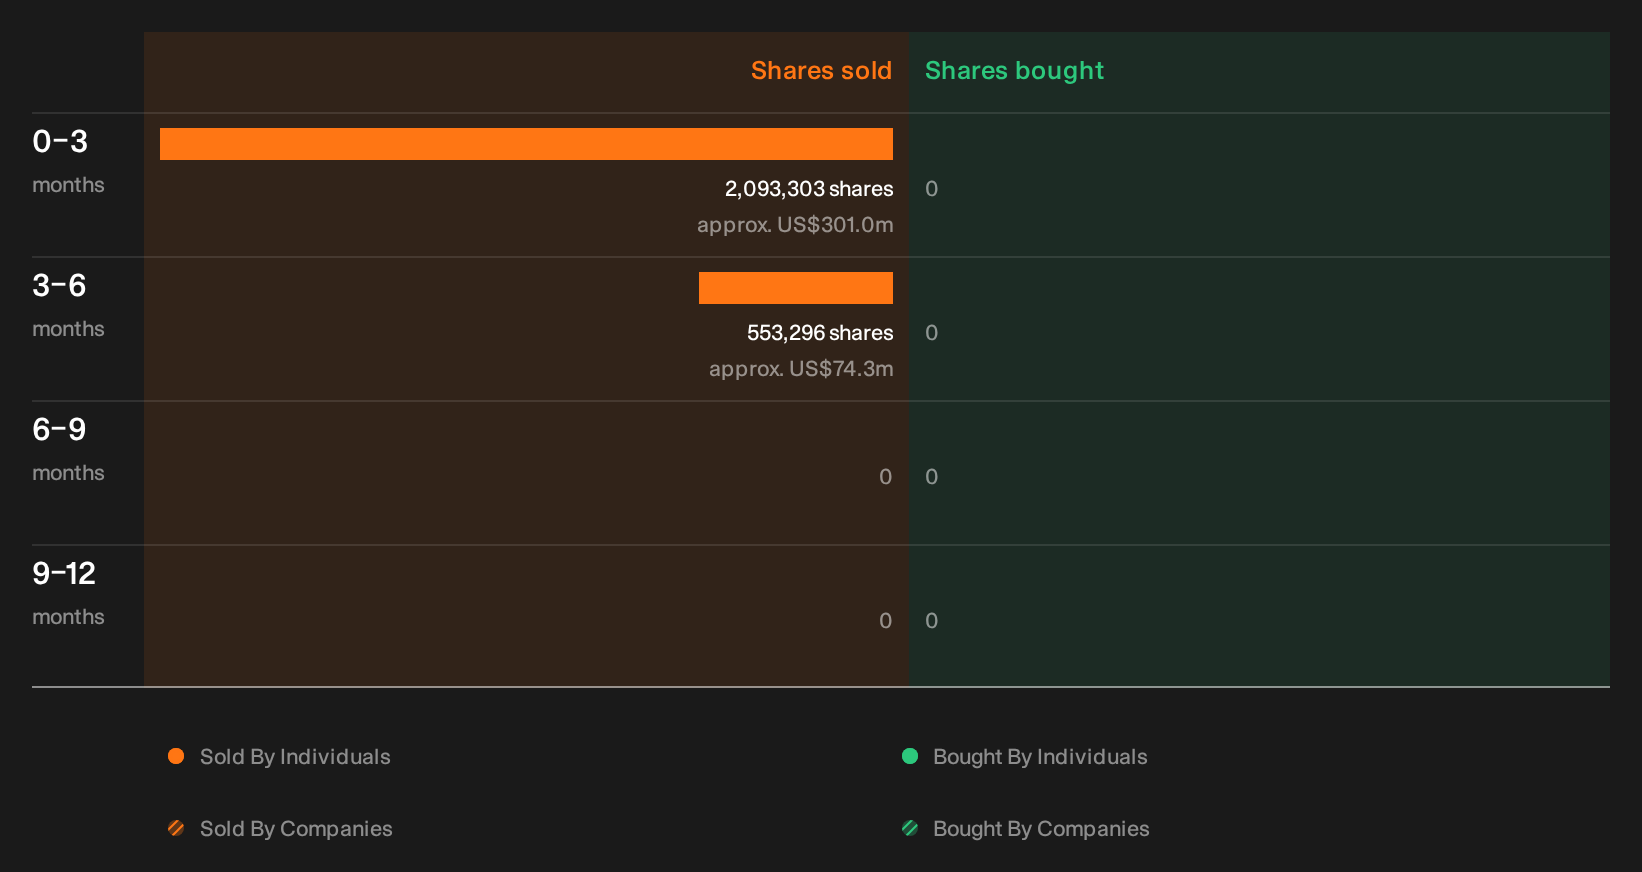
Valuation, cash generation and partnerships tell only part of Airbnb's picture, because recent activity by people inside the business adds another clue that investors often watch closely. See the recent insider selling flagged for Airbnb.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com