
Comcast (CMCSA) Stock Stays Cheap On Its 45% Five Year Slide
Comcast has seen its share price slide over a multi year stretch, even as recent news has sparked a short term bounce. With the stock last closing at US$22.69, the question for investors is whether that price can be explained by the earnings power of the business.
- Over the past 5 years the share price has fallen 44.8%, which puts the focus squarely on whether current earnings still justify even this lower valuation.
- Recent results highlighted pressure in the core broadband unit alongside growth in streaming and wireless, a mix that can reshape assumptions about future profitability and the timing of cash generation from Comcast's earnings base.
- Your read on Comcast is one view; the desks covering it have another. See what analysts think Comcast's shares could be worth.
The stock's next move may depend on whether Comcast's current earnings are strong and reliable enough to support the price investors are paying today.
If you want to test this same earnings driven question across a wider field, compare Comcast with 28 high quality undervalued stocks.
Does Comcast Look Undervalued on Earnings?
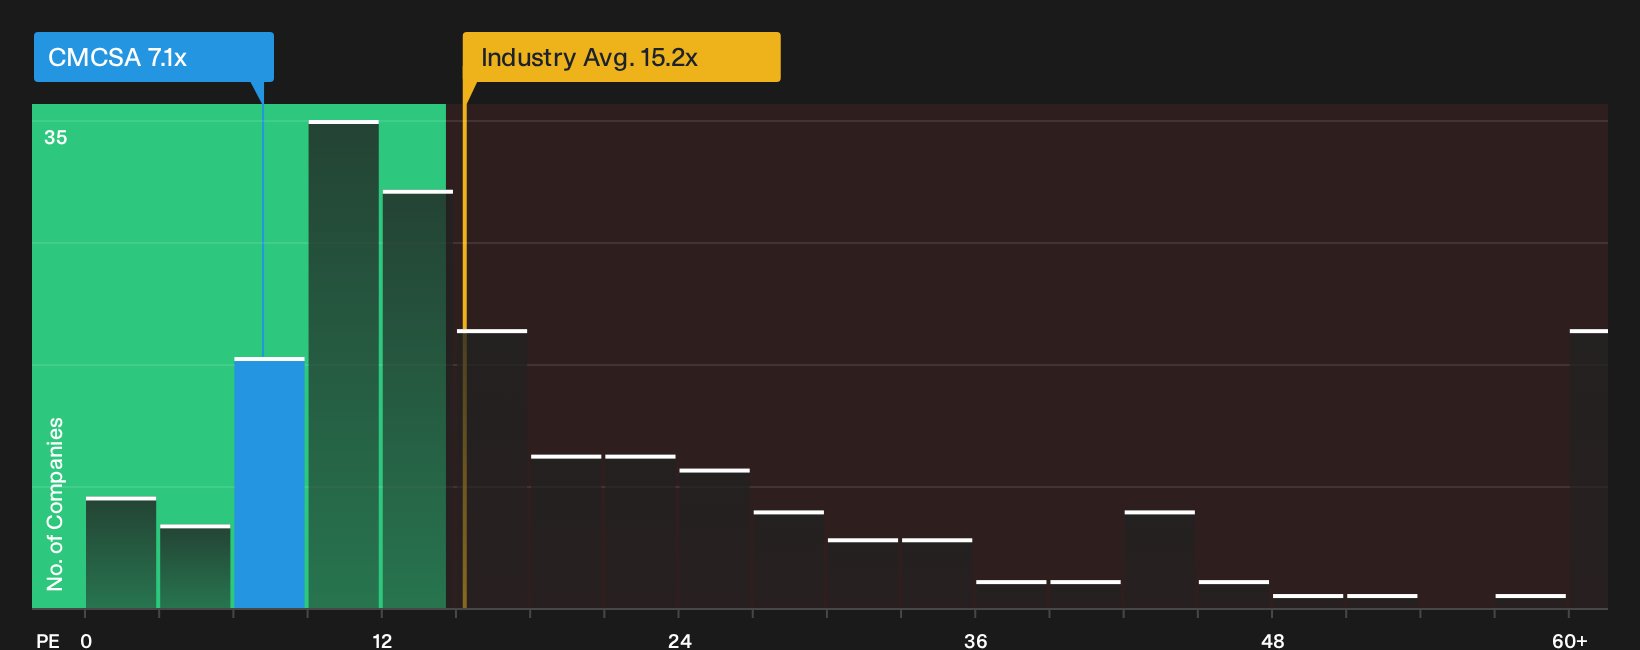
The P/E ratio gives a clean read on how the market prices Comcast's current earnings stream. On this measure, Comcast trades at about 7.1x earnings, compared with roughly 15.2x for the wider telecom sector and around 12.7x for peers in its comparison set. That is a sizeable gap between what investors are willing to pay for each dollar of Comcast profit and what they pay across the industry.
Because of this gap, and based on a tailored fair multiple that factors in Comcast's own growth profile, margins, scale and risk, the stock screens on the undervalued side of that range. The recent Q3 beat on earnings, despite pressure in broadband and a planned separation of NBCUniversal and Sky, has not closed that discount, so the shares still change hands at a lower earnings multiple than many comparable telecom groups. Explore the numbers behind Comcast's P/E valuation.
The Comcast Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Comcast's valuation puzzle leaves off, spelling out which paths for growth, profitability and earnings would need to play out for the stock to trade meaningfully above or below where it is today. They sit on Simply Wall St's Community page. Rather than relying on a single multiple or model line, each narrative lays out its own set of assumptions for Comcast's worth so you can compare those expectations with the actual numbers as quarterly results arrive.
Community views on Comcast are split between those who see underappreciated earnings power and those who worry the multiple still has room to compress.
Bull case: 19% undervalued
"The current setup implies the share price does not fully reflect the potential value of Comcast’s converged connectivity, profitable AVOD streaming, and expanding experiences businesses..."
Discover why this Narrative puts Comcast at 19% undervalued.
Bear case: 33% overvalued
"The numbers imply Comcast's share price already reflects meaningful confidence in the long term earnings power of its converged connectivity, streaming and parks businesses..."
Explore why this Narrative puts Comcast at 33% overvalued.
One more angle on Comcast that could change how you read today’s price
Valuation work tells you what you are paying for Comcast as it stands today, but the projections that professionals are building a few years out can either reinforce or challenge that picture. Explore where analysts expect Comcast to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com