
Premium P E Debate Might Change The Case For Investing In Bird Construction Stock
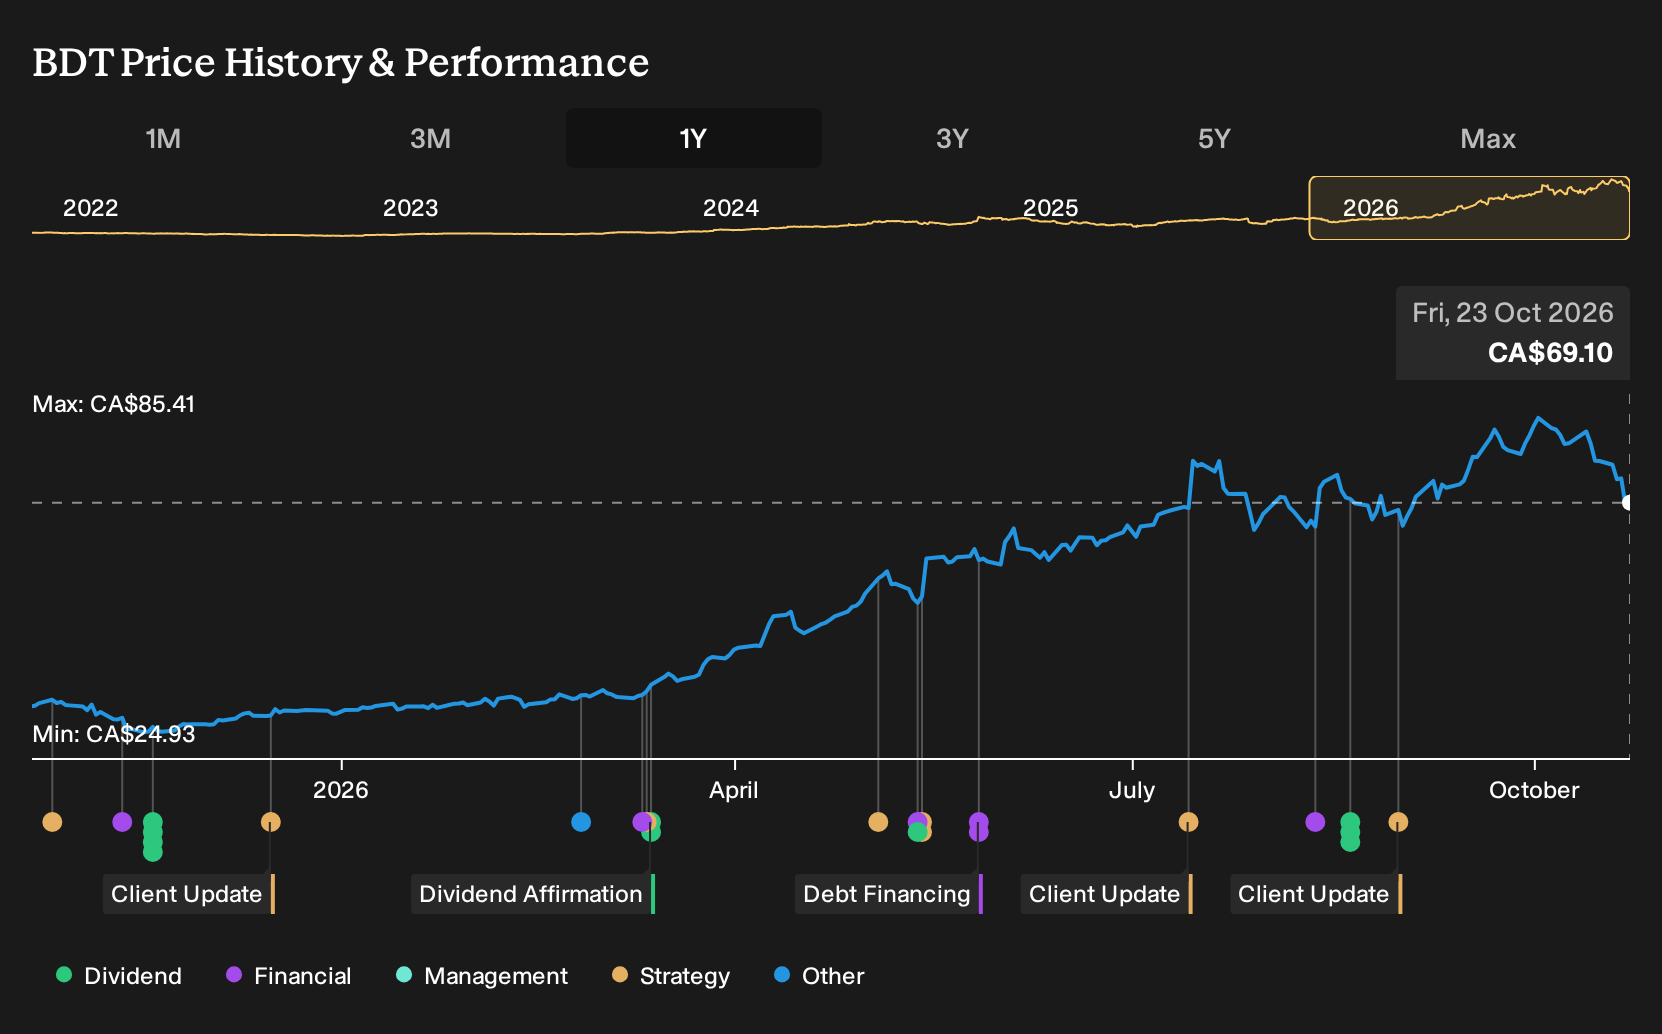
- Bird Construction is trading at a P/E multiple well above Canadian construction peers, reflecting strong multi-year execution and a premium being paid for its current earnings power.
- The real pressure point is how resilient Bird Construction’s profit engine proves across future project cycles, given that investors are already paying up for today’s profitability.
- We will now look at how Bird Construction's premium valuation and the debate around its earnings durability could reshape its broader investment narrative.
Compare Bird Construction’s premium P/E and the debate around its earnings durability with other potential opportunities by scanning our handpicked 3 high quality undervalued stocks, which may offer stronger value for the risk you are taking.
Bird Construction Investment Narrative Recap
For Bird Construction to make sense in your portfolio, you need to be comfortable with a construction group priced for strong execution on a CA$12b combined contracted and pending backlog and higher embedded margins in collaborative work. The key short term swing factor is how efficiently that backlog is turned into revenue and cash without further pressure on already thin 1.6% profit margins.
The recent focus on Bird Construction’s rich P/E multiple mainly sharpens attention on downside risk if large projects slip or margins compress. At this stage, the news is more about valuation than operations, so it does not materially change the primary near term catalyst or the main earnings risk.
Without a fresh batch of company specific announcements tied directly to this valuation debate, the most relevant reference point remains the Q2 2026 snapshot. That period showed revenue above CA$1.043b, adjusted EBITDA margin of 7.1%, and combined backlog of about CA$12b, with more than 80% tied to collaborative or recurring arrangements.
For you as an investor, that operational setup links neatly to the premium multiple discussion. Execution on higher margin collaborative work, FRPD’s high utilization, and the Bell AI Fabric data centre pipeline are all practical catalysts that could support earnings quality, while any repeat of credit issues like the CA$62.2m impairment or slower backlog conversion sits on the risk side of the ledger.
Bird Construction's current analyst narrative points to CA$5.8b in revenue and CA$338.9m in earnings by 2029, based on an assumed 16.9% yearly revenue growth rate and an earnings increase of about CA$279.5m from today’s CA$59.4m level.
Discover how Bird Construction's fair value indicates a 29% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
One bullish twist on Bird Construction is how much weight some analysts put on the data centre opportunity. Before this news, the most optimistic forecasts already pencilled in about CA$6.1b of revenue and CA$341.3m of earnings by 2029, which is a far more aggressive path than consensus. These views could shift as fresh information lands, so consider them as one of several competing storylines to compare for yourself.
Explore 3 other Bird Construction fair value estimates, including one that suggests up to 29% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own process and analysis.
- A great starting point for your Bird Construction research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bird Construction. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bird Construction's overall financial health at a glance.
Looking for more investment ideas beyond Bird Construction?
Once you have a view on Bird Construction, it can help to widen the lens and compare it with other businesses that better fit your return and risk preferences. The Simply Wall St Screener lets you do exactly that by filtering the market using fundamentals that match your own checklist rather than someone else's story.
- If you care most about quality at a reasonable entry point, start with companies that pass tight valuation and balance sheet filters using our 3 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than rapid growth, narrow the universe to resilient businesses with measured risk using the 8 resilient stocks with low risk scores.
- If you are hunting for resilient cash generators with cleaner finances, focus your search on companies screened for strong balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (7 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com