
Brazil Implodes -21%. Cybersecurity Breaks Out. The Market Doesn't Care About Either.
John Salama, CMT
ETF Market Strategist & Derivatives Trader | CMT | Author, Physical Over Digital Alpha | Featured Author, Barchart | 500+ Institutional Subscribers
October 26, 2026
Monday’s session is defined by violent extremes at the margins and remarkable composure at the core. SPY adds ~+0.8%, essentially flat on the 5-day window, while the session’s biggest single-name event was EWZ, the iShares MSCI Brazil ETF, collapsing -21% in a single day. That move, nearly 4 standard deviations on a daily basis, barely registered in U.S. equity breadth.
Beneath the surface, the structural moves are more instructive:
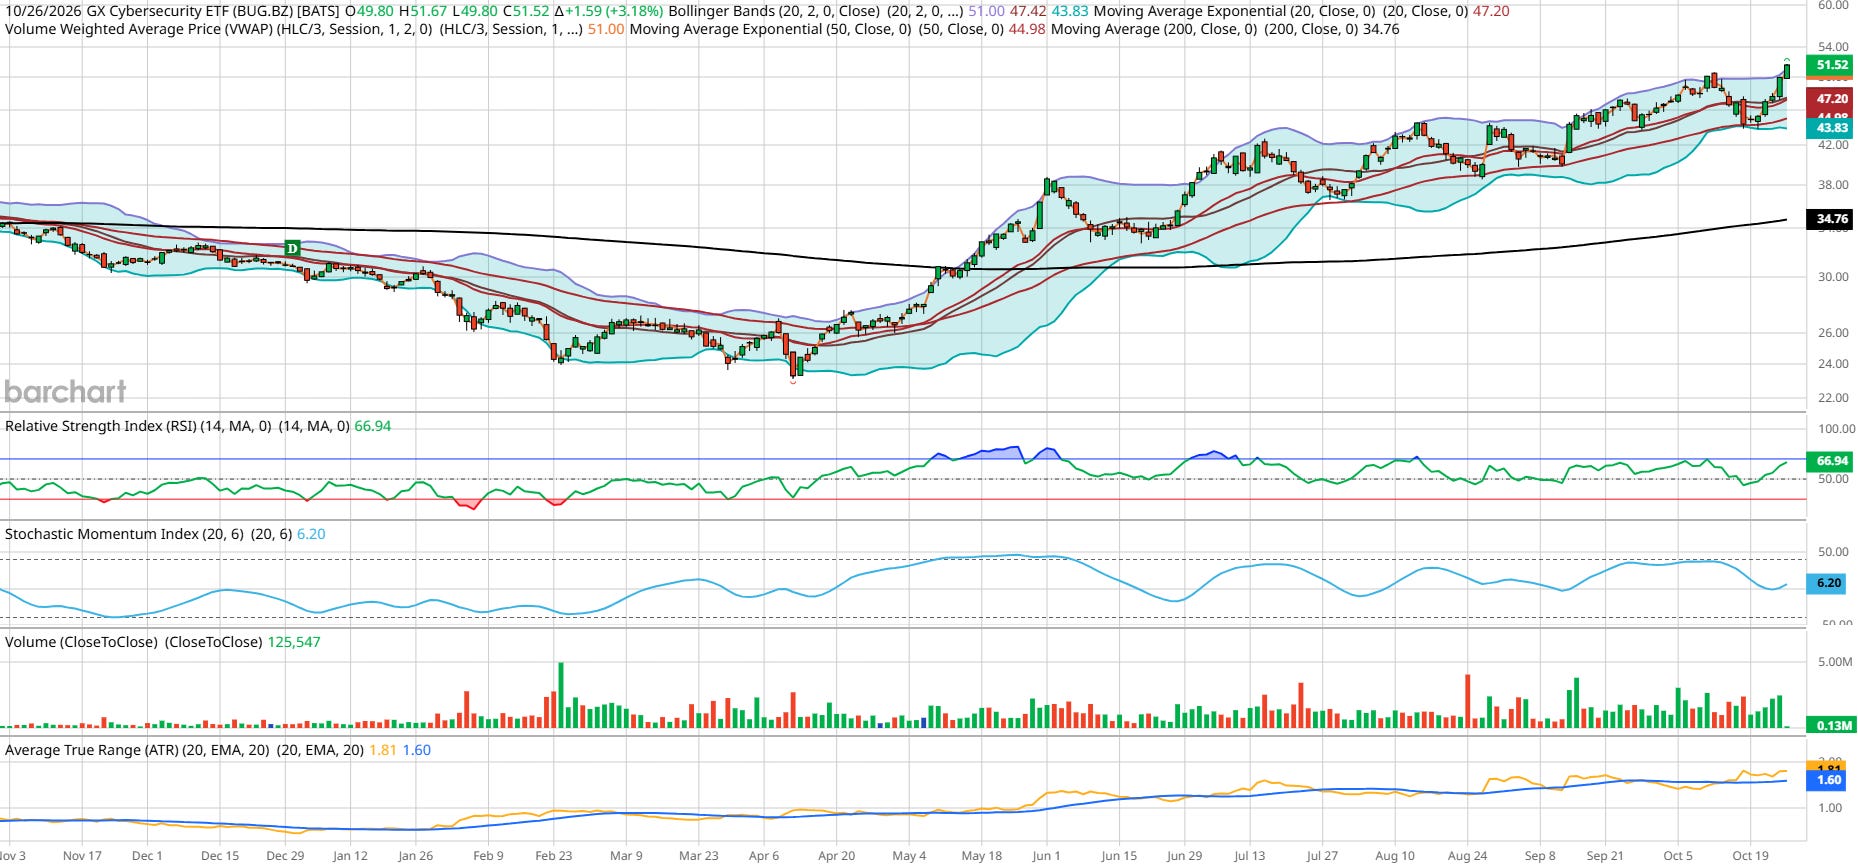
BUG (GX Cybersecurity ETF) surged +14% over five days to a fresh all-time high, home construction (ITB +6%) and regional banks (KRE +5%) confirmed the rate-sensitive bid is intact, while natural gas (UNG -8%) printed a fresh all-time low and gold miners (GDX -6%) continued systematic distribution.
Key Session Highlights:
New All-Time High:
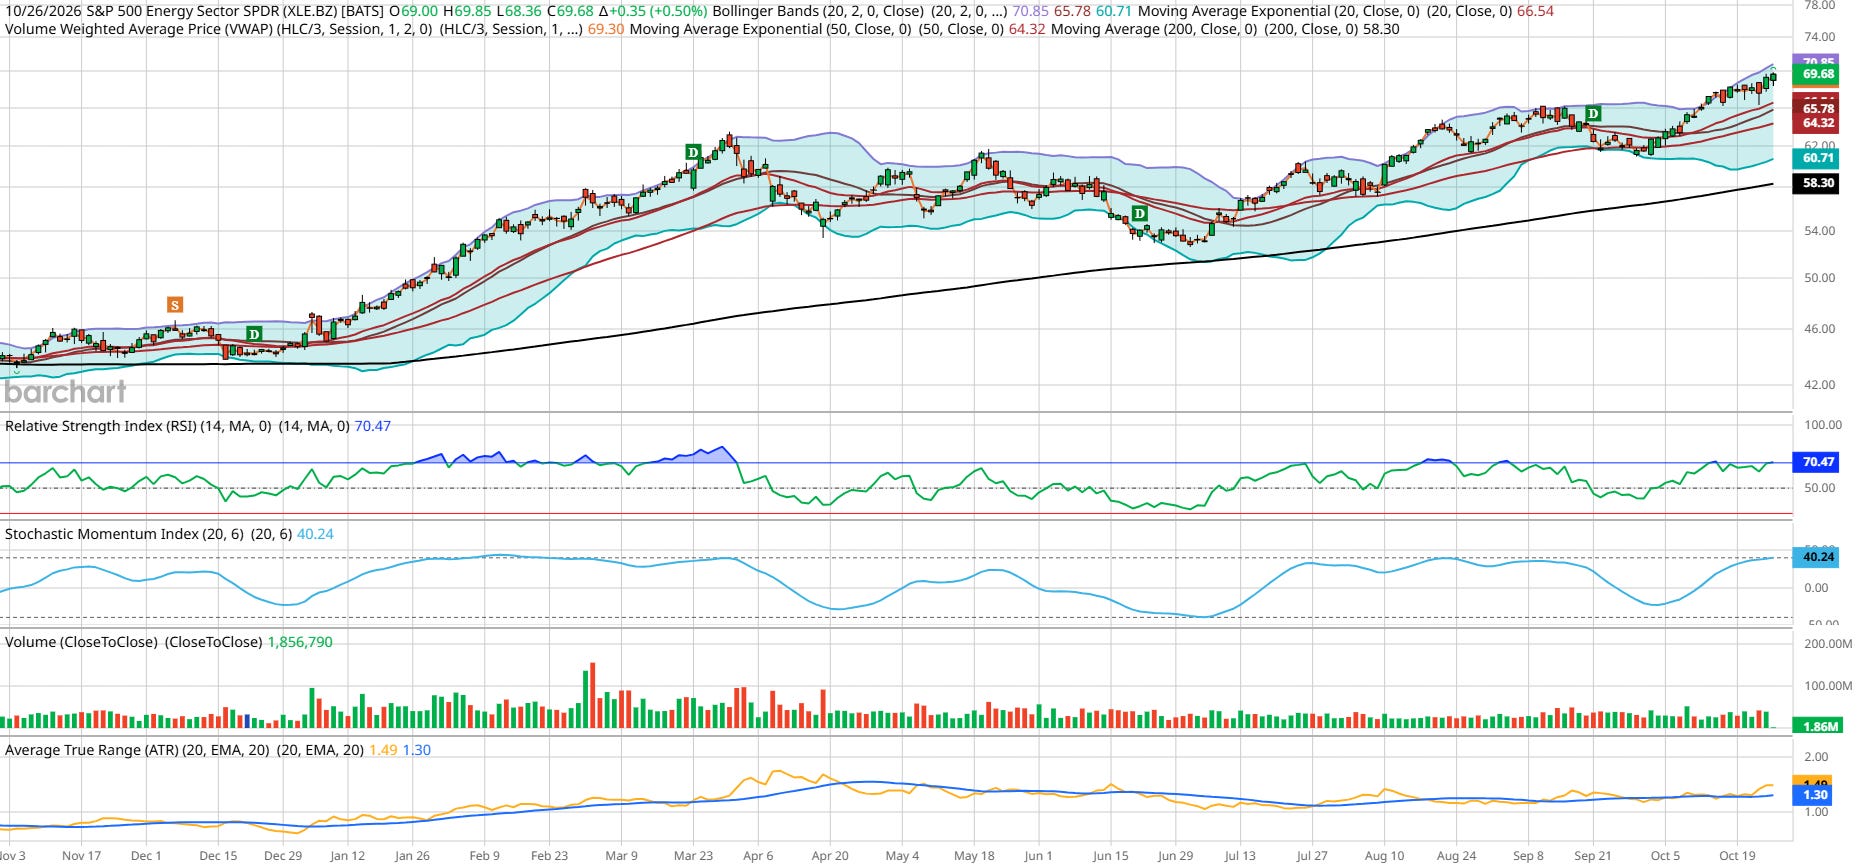
XLE (Energy Select Sector SPDR), BUG (GX Cybersecurity ETF)
New All-Time Low: UNG (United States Natural Gas Fund)
New 52-Week Low: XLC (S&P 500 Communication Sector SPDR), ICLN (iShares Global Clean Energy), TAN (Invesco Solar ETF)
Top Daily Sigma Gainer: XLI (+1.4%)
Top Daily Sigma Losers: EWZ (-20.9%), ETHA (-2.7%), XLC (-1.2%)
Active Tactical Positions: SHORT EWZ | LONG BUG | SHORT UNG
Daily Sigma Movers; Extremes at the Margins
Top Standard Deviation Moves of the Session; Sorted by Sigma Magnitude
Gainers:
ETF Name Daily Move
XLI S&P 500 Industrials Sector SPDR +1.4%
Losers:
ETF Name Daily Move Note
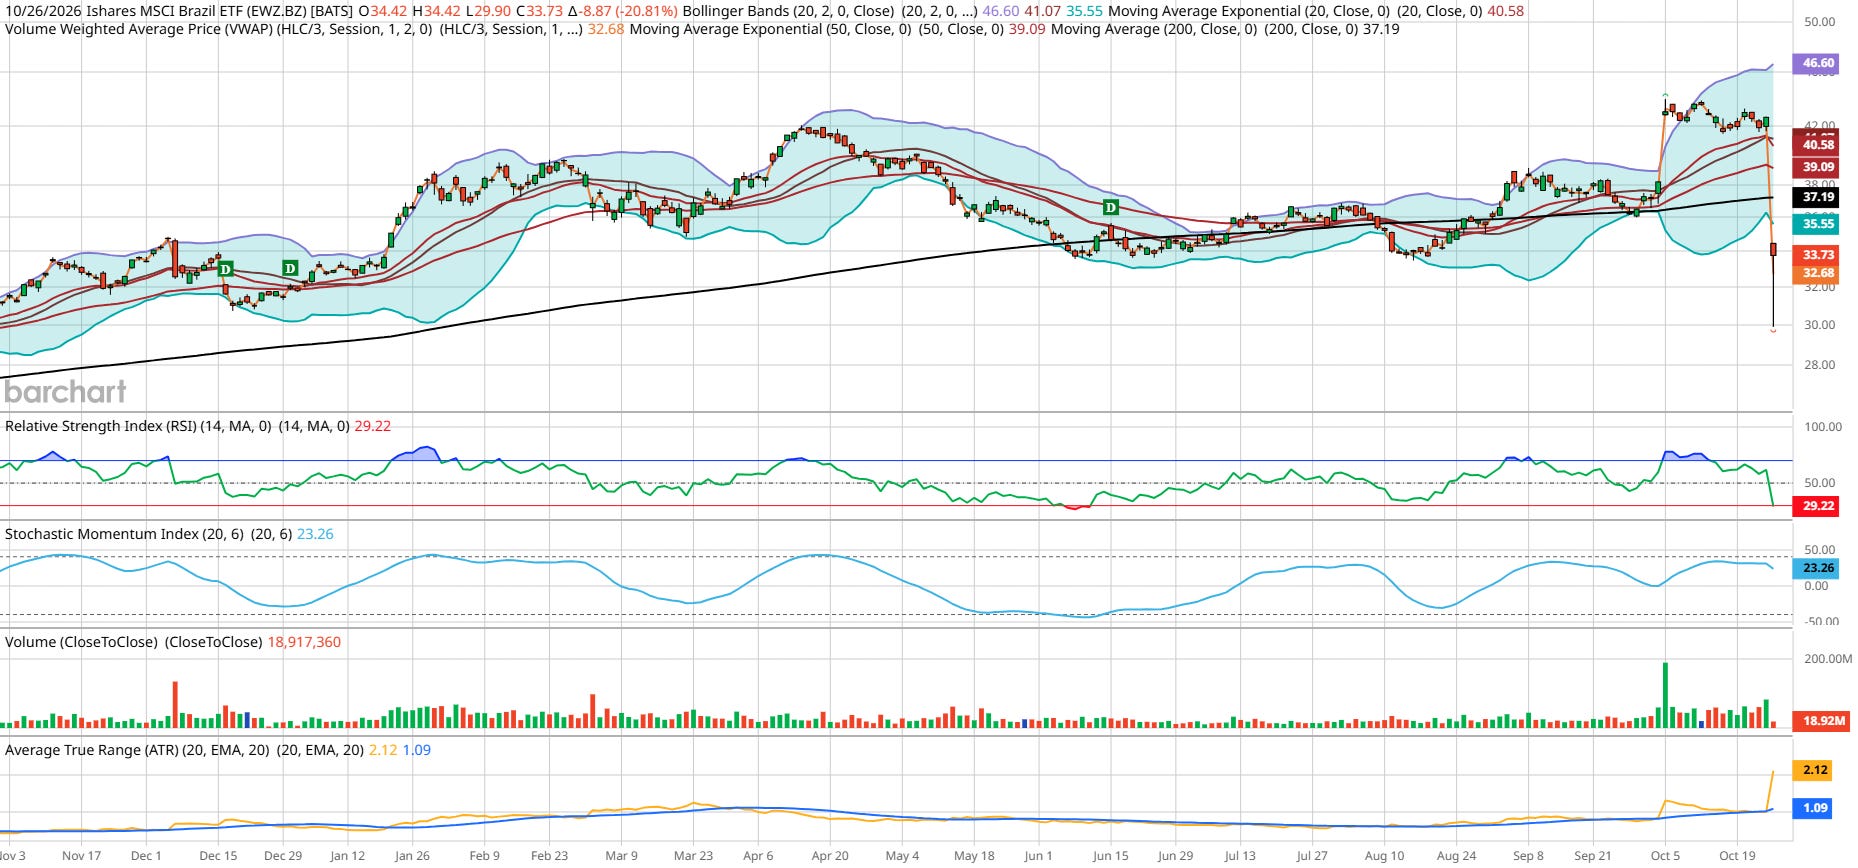
EWZ iShares MSCI Brazil ETF -20.9%
ETHA iShares Ethereum Trust ETF -2.7%
XLC S&P 500 Communication Sector SPDR -1.2% - NEW 52-WEEK LOW
XLC hitting a fresh 52-week low alongside ICLN and TAN confirms the communication/tech growth complex and clean energy remain in sustained distribution. These aren’t bounces waiting to happen, they’re sectors where institutional capital has structurally rotated out.
Industrials (XLI +1.4%) quietly posting the session’s top sigma gain tells a different story: domestic capex, manufacturing, and infrastructure spending remain bid. In a session dominated by EM chaos and crypto softness, XLI grinding to new highs is a quality signal.
5-Day Rolling Window; Three Clean Trades
The rolling window shows where positioning is working and where the structural pressure lies.
Top 5-Day Gainers:
ETF Name 5-Day Return Note
BUG GX Cybersecurity ETF +14% - NEW ATH
ITB iShares US Home Construction ETF +6%
KRE SPDR S&P Regional Banking ETF +5%
Top 5-Day Decliners:
ETF Name 5-Day Return Note
EWZ iShares MSCI Brazil ETF -21%
UNG United States Natural Gas Fund -8% - NEW ALL-TIME LOW
GDX VanEck Gold Miners ETF -6%
Active Tactical Positions:
SHORT EWZ When a major EM ETF loses over 20% in a week without U.S. contagion, the domestic bid for that risk has evaporated. Short positioning via bear put spreads remains active.
LONG BUG Cybersecurity breaking out to an all-time high with +14% over five days is not a crowded trade, it’s a regime shift. AI-driven threat surface expansion is creating structural, durable demand for cybersecurity infrastructure. This is not a momentum chase; it’s a thematic long with fundamental backing. BUG’s ATH is a breakout, not a top.
SHORT UNG Natural gas printing an all-time low is the continuation of a supply-driven structural collapse. There is no floor established. Bear put spread positioning stays active until price action signals distribution exhaustion.
The three-trade framework (one EM short, one domestic thematic long, one commodity short) provides clean relative-value diversification. All three are working.
SPY Vol Surface; November Expiration (25 DTE)
The options market heading into the final week of October.
SPY Options Chain November 20, 2026 Expiration
Metric Reading
SPY Price 766
Expiration November 20, 2026 (25 DTE)
ATM Implied Volatility 14.8%
10-Day Historical Volatility 10.3%
IV Rank 24.8%
Key OI Walls:
Put wall: 760 (33k OI) | 765 (21k OI) | 770 (24k OI)
Call wall: 770 (15k OI) | 775 (12k OI)
The vol surface read:
IV Rank at 24.8% is meaningfully higher than last Monday’s 18.0%, the market is repricing tail risk into month-end. ATM IV of 14.8% against 10-day realized vol of 10.3% gives us basis points of premium which is a structural edge for premium sellers.
The OI structure is notable this week: the 770 strike has significant open interest on both sides, 15k call OI and 24k put OI. That level is acting as a gravitational magnet. With SPY at 766 and the 770 strike as the dominant OI anchor, market maker hedging flow will keep 770 in play as a ceiling into expiration unless a catalyst forces a decisive break. Above 775 (12k call OI) with volume and the structure changes, that’s the level to watch for the next leg.
Week-ahead positioning: SPY flat on the 5-day window (+0.8% today recovering from prior weakness) while IV Rank rises is a warning signal. The market is buying insurance even as price grinds higher. That’s not complacency, it’s institutional hedging. Respect it.
Macro Positioning; Connecting the Dots
Today’s session delivers a coherent macro message if you read it as a whole rather than in pieces.
Domestic quality is bid. XLI hitting a session high, BUG breaking to ATH, ITB and KRE posting five-day leadership; this is capital flowing into domestic cyclicals, infrastructure, and financials. The rate-sensitive complex is being bought, not sold. That’s a macro call on U.S. economic resilience.
EM risk is being actively repriced. EWZ -21% in isolation is a Brazil-specific event. But combine it with EWY’s -7% from last week and a pattern emerges: institutional capital is reducing EM exposure systematically. When Brazil and South Korea both print multi-sigma declines in the same rolling window, the common factor isn’t country-specific, it’s global EM risk appetite.
Clean energy is breaking down structurally. ICLN and TAN both hitting 52-week lows alongside XLC is a policy and rates story. The green energy thematic trade that dominated 2023-2024 is in full distribution. No evidence of a floor.
Natural gas has no bid. UNG at an all-time low means supply has overwhelmed any seasonal demand dynamic. Until storage data shifts meaningfully, this is a one-way tape.
The week ahead: watch 770 as the SPY pivot level, BUG for continuation above ATH, and EWZ for any stabilization signal before covering the short. The positioning framework (long domestic quality, short EM and commodities in structural decline) remains fully intact.
Physical Over Digital Alpha delivers institutional-grade ETF strategy and volatility intelligence to 500+ professional subscribers. Upgrade your market edge at barchart.com/get-barchart-premier?fpr=h1fuww
John Salama, CMT is a systematic trader and the founder of Physical Over Digital Alpha. Views expressed are his own and do not constitute investment advice.