
EQT Stock Puts Appalachian Gas Producers Back On Retail Investors' Radar
The EQT deal for Range Resources is a reminder that quiet corners of the market can suddenly move to center stage when big money starts rearranging the map. When a US$50b all stock merger reshapes Appalachian gas, it can ripple far beyond EQT itself and influence how investors think about scale, costs and future deals. This article examines three stocks exposed to that same news shock and outlines why their stories now warrant a closer look.
The stocks highlighted below are just a first pass on the EQT and Range Resources theme. The full screen surfaced 7 more U.S. Appalachian natural gas producers with equally compelling narratives that are not covered here. To identify which operators best fit your own risk and return preferences, head straight into the U.S. Appalachian Natural Gas Producers screener to filter, analyze, and focus on your highest conviction ideas.
Expand Energy (EXE)
Overview: Expand Energy is a U.S. exploration and production company focused on natural gas from the Marcellus and Utica shales in the Appalachian Basin, with additional Haynesville exposure.
Operations: Expand Energy generates all of its US$12.7b in revenue from exploration and production activities in the United States.
Market Cap: US$21.6b
For investors zeroing in on pure-play U.S. gas, Expand Energy links the screener theme directly to large scale Marcellus and Utica capacity while adding a meaningful Haynesville lever that could reshape future cash flows.
"Meaningful breakeven reductions in the Haynesville, supported by self-sourced sand, completion design upgrades and drilling efficiency gains, position the company to prioritize its lowest cost inventory and potentially support stronger net margins and earnings through commodity cycles."
The real swing factor is how one evolving source of end demand ultimately feeds through to realized prices, contract quality and long term profitability.
That pricing chain is exactly what the full narrative for Expand Energy unpacks in detail, including how cost wins, contract shapes and capital choices could be accelerating or masking Expand Energy’s story.

Range Resources (RRC)
Overview: Range Resources is an independent U.S. producer focused on Marcellus based natural gas and NGLs in the Appalachian Basin.
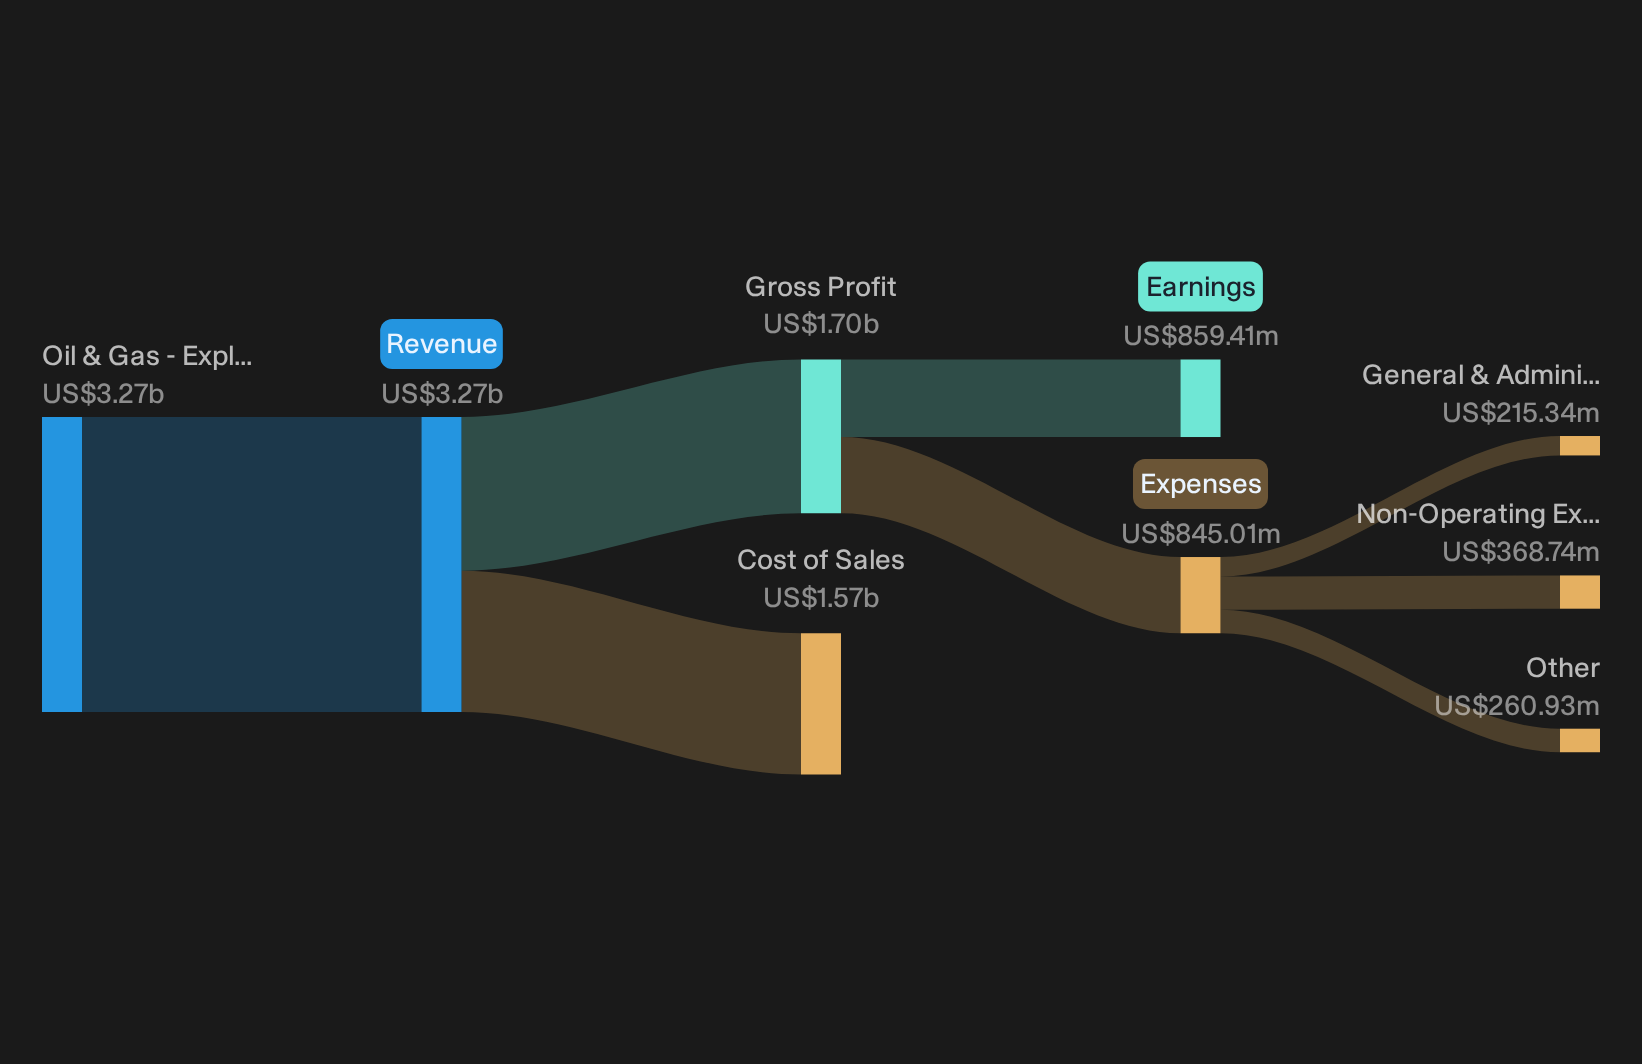
Operations: Range Resources generates about US$3.3b in revenue from U.S. oil and gas exploration and production operations.
Market Cap: US$10.6b
Range Resources is the pure Appalachian gas story in this list, with Marcellus scale that directly ties into the consolidation theme driving the EQT deal.
"Although Range Resources has laid out a multi year plan for capital efficient production growth supported by long life Marcellus inventory, lower natural gas price forecasts and oversupply concerns mean that any misstep in well costs or drilling and completion spending could turn that growth target into thinner margins and weaker earnings rather than higher value."
What happens to Range Resources’ valuation hinges on how one pressure point between growth spending and cash generation ultimately resolves.
That trade off is exactly what the full narrative for Range Resources lays out, showing where growth spending could be accelerating value creation rather than simply masking pressure on Range Resources.
EQT (EQT)
Overview: EQT Corporation is a major U.S. natural gas producer focused on Marcellus and Utica output in Appalachia, selling gas and related products to regional utilities, marketers, and industrial customers while also managing gathering, transmission, and storage infrastructure.
Operations: EQT generates about US$8.8b from upstream activity, roughly US$1.3b from gathering, and around US$600m from transmission, with almost all US$9.3b of revenue coming from the United States.
Market Cap: US$34.8b
EQT matters most for this screener because it is the pure Appalachian gas heavyweight; it is reshaping Marcellus and Utica through consolidation and integration rather than simply reacting to it.
"The ramp-up of large-scale, long-term natural gas supply contracts to new AI data centers and power generation facilities in Appalachia beginning in 2027 and 2028 remains central to EQT capturing growing in-basin demand for its production."
What ultimately happens to EQT’s cash generation will hinge on how one quiet cost advantage interacts with those long dated demand commitments.
That quiet edge is exactly what the full narrative for EQT unpacks. It shows where cost advantages and long term demand could be accelerating EQT’s value story beyond headline contracts.

Seeking Alternatives Before Momentum Flies
Fresh themes can move from quiet to breakout quickly, and the best entry points are often identified first by fast movers. Scan these ideas before the crowd and consider them early.
- Spot resilient businesses before momentum headlines hit by filtering for companies on the 30 resilient stocks with low risk scores, while risk scores still reflect under-the-radar fundamentals.
- Hunt for quality on sale by tracking the 28 high quality undervalued stocks and focus on businesses where cash flows, balance sheets, and valuations have not yet fully aligned.
- Explore the infrastructure backbone of the AI buildout by focusing on the 55 AI infrastructure stocks, while capital is still rotating into the underlying enablers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com