
Lundin Mining (TSX:LUN) Moved Higher, What Is Behind The Attention?
Lundin Mining (TSX:LUN) put fresh guidance on the table for its 2026 quarter, flagging an expected revenue lift from about $51 million in unaudited provisional pricing adjustments on earlier concentrate sales.
Lundin Mining’s guidance lands after a choppy stretch for the stock, with a 1-day share price return of 3.08% lifting it to CA$30.41 even though the 30-day share price return is down 13.06%. Despite that pullback, total shareholder return over the past year is 42.38% and more than doubles again over five years. This points to strong longer term momentum even as shorter term moves react to shifting expectations around copper pricing and updated revenue guidance.
Scan beyond Lundin Mining and see how other copper producers are positioned for the next price reset with our curated list of 16 top copper producer stocks.
Lundin Mining looks like a solid copper producer on paper, with large operations across Chile and Brazil and fresh revenue support from provisional pricing gains. The real test now is whether that strength is already baked into a CA$30.41 share price.
Most Popular Narrative: 30% Undervalued
The most followed narrative currently pegs Lundin Mining’s fair value at CA$43.70, well above the CA$30.41 last close. This puts a lot of focus on how the business executes its long list of copper projects in Chile and Brazil.
Lundin Mining is advancing multiple organic growth initiatives such as the Vicuña project and brownfield expansions at existing operations that are expected to significantly increase copper and gold production volumes over the coming years, positioning the company to benefit from rising global demand for electrification metals. These developments are set to drive higher future revenue and EBITDA.
See why 33 investors see Lundin Mining as 30% undervalued.
That storyline prices Lundin Mining using a 7.89% discount rate and implies investors are paying CA$30.41 for a stream of cash flows the narrative values at CA$43.70. The gap reflects a view that current earnings and margins, including the 29.2% profit margin and high 22.3% return on equity, can support that higher figure even though analysts collectively forecast earnings to decline by an average of 7.3% per year over the next three years.
Putting it together, the prevailing thesis is that concentrated exposure to South American copper and capital heavy growth plans introduces real risk. At the same time, the long project pipeline and current profitability are viewed as supporting a fair value that sits meaningfully above the present share price.
Result: Fair Value of CA$43.70 (UNDERVALUED)
Still, concentrated exposure to South American copper assets and the capital heavy build out at projects like Vicuña mean setbacks or regulatory shifts could quickly challenge the current Lundin Mining narrative.
Find out about the key risks to this Lundin Mining narrative.
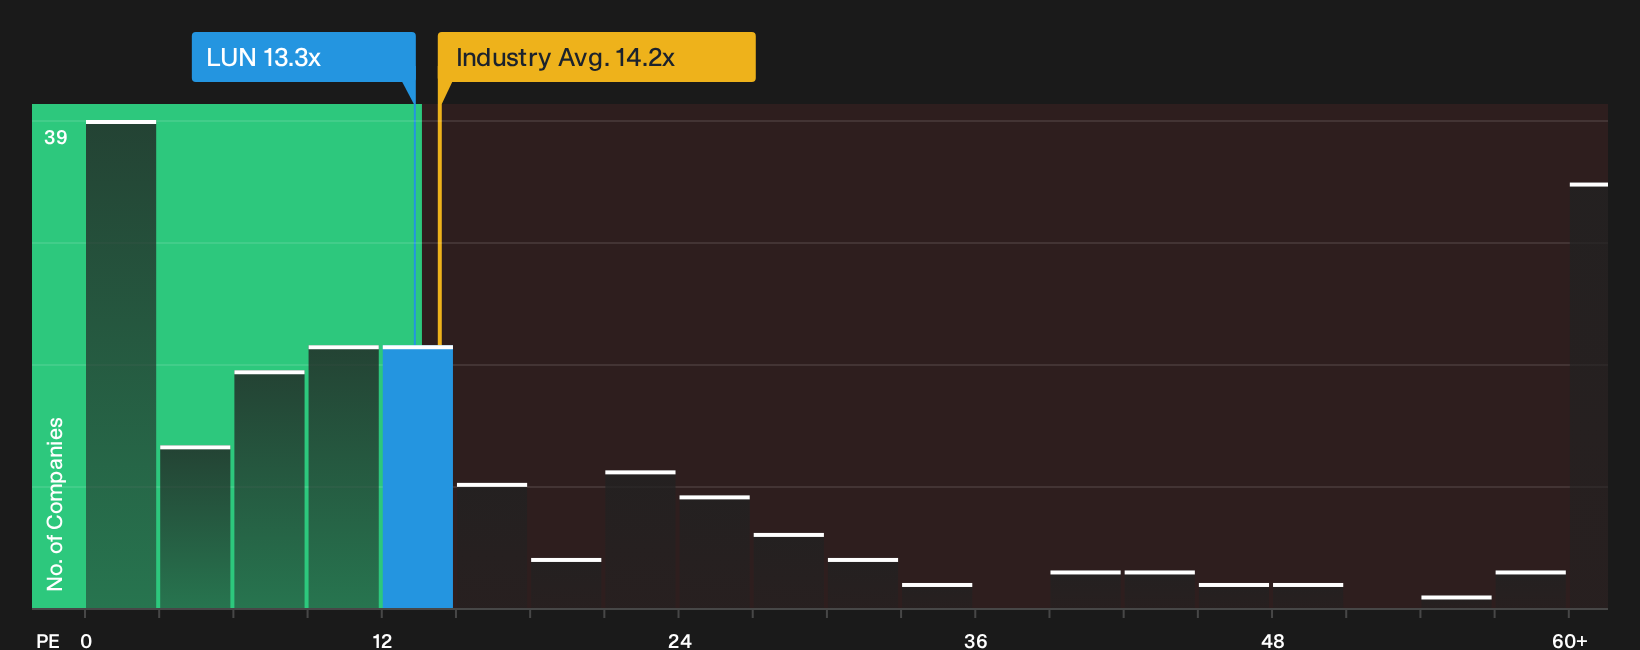
Another View: What Lundin Mining’s P/E Ratio Implies
There is a very different story when you look at Lundin Mining through its P/E ratio. The shares trade on 13.7x earnings, slightly below the Canadian Metals and Mining industry at 14.2x, yet above a fair ratio estimate of 12.9x that the market could gravitate toward over time.
This mix of being cheaper than the industry but richer than the fair ratio suggests both room for optimism and valuation risk if expectations cool or earnings slip. The question for you is whether Lundin Mining has delivered enough to justify staying above that fair ratio, or if the multiple eventually settles closer to it.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Lundin Mining’s valuation and risk profile are clear, so move quickly, review the underlying data, and weigh the trade off for yourself with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Lundin Mining?
If you stop at Lundin Mining, you may miss a wider field of potential opportunities. Consider spending a few minutes exploring additional ideas that might better match your goals.
- Focus on balance sheets and fundamentals by scanning companies in the list of solid balance sheet and fundamentals (7 results).
- Search for potentially mispriced quality by using the 3 high quality undervalued stocks that screens for both strength and value.
- Explore income options by reviewing the 3 dividend fortresses that focuses on higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com