
OceanFirst Financial (OCFC) Nears Earnings, Is Its 24% Undervaluation Convincing?
Why OceanFirst Financial’s Upcoming Earnings Matter
OceanFirst Financial (OCFC) reports earnings after the closing bell on Tuesday, a key moment following its prior quarter revenue miss and expectations for significantly higher year-on-year sales this time.
Recent trading has been choppy for OceanFirst Financial. The 7 day share price return of 5.45% follows a 90 day share price decline of 17.8%. The 3 year total shareholder return of 50.4% contrasts with a weaker 5 year total shareholder return, which has declined 10.92%.
Scan other regional banks moving around upcoming earnings with our hand-picked list of solid balance sheet and fundamentals (24 results) to compare OceanFirst Financial’s setup against peers with stronger fundamentals.
Bulls point to OceanFirst Financial’s strong recent revenue and net income growth. Bears focus on the share price slide and last quarter’s miss. Which side does the current valuation actually support next?
Most Popular Narrative: 24% Undervalued
The most followed narrative on OceanFirst Financial pegs fair value at $21.58, well above the recent $16.47 close. As a result, earnings now slot into a bigger story about integration, cost control and where returns might settle.
The main requirement is that management successfully executes on balance sheet optimization and cost control, including realizing Flushing merger cost savings, keeping expenses near guided levels, and preserving the current low levels of nonperforming loans and charge-offs while shifting the loan mix away from higher-risk CRE exposures.
The current valuation suggests the market is cautious about whether OceanFirst Financial will convert its larger scale, guided net interest margin levels, and long dividend track record into the mid-teens ROTCE and approximately 1% ROA targets that management has set for 2027.
See why 7 investors see OceanFirst Financial as 24% undervalued.
Result: Fair Value of $21.58 (UNDERVALUED)
Still, if net interest income or margin trends disappoint, or Flushing integration costs run higher than planned, the bullish OceanFirst Financial narrative could unravel quickly.
Find out about the key risks to this OceanFirst Financial narrative.
Another View: OceanFirst Financial Looks Pricey On Earnings
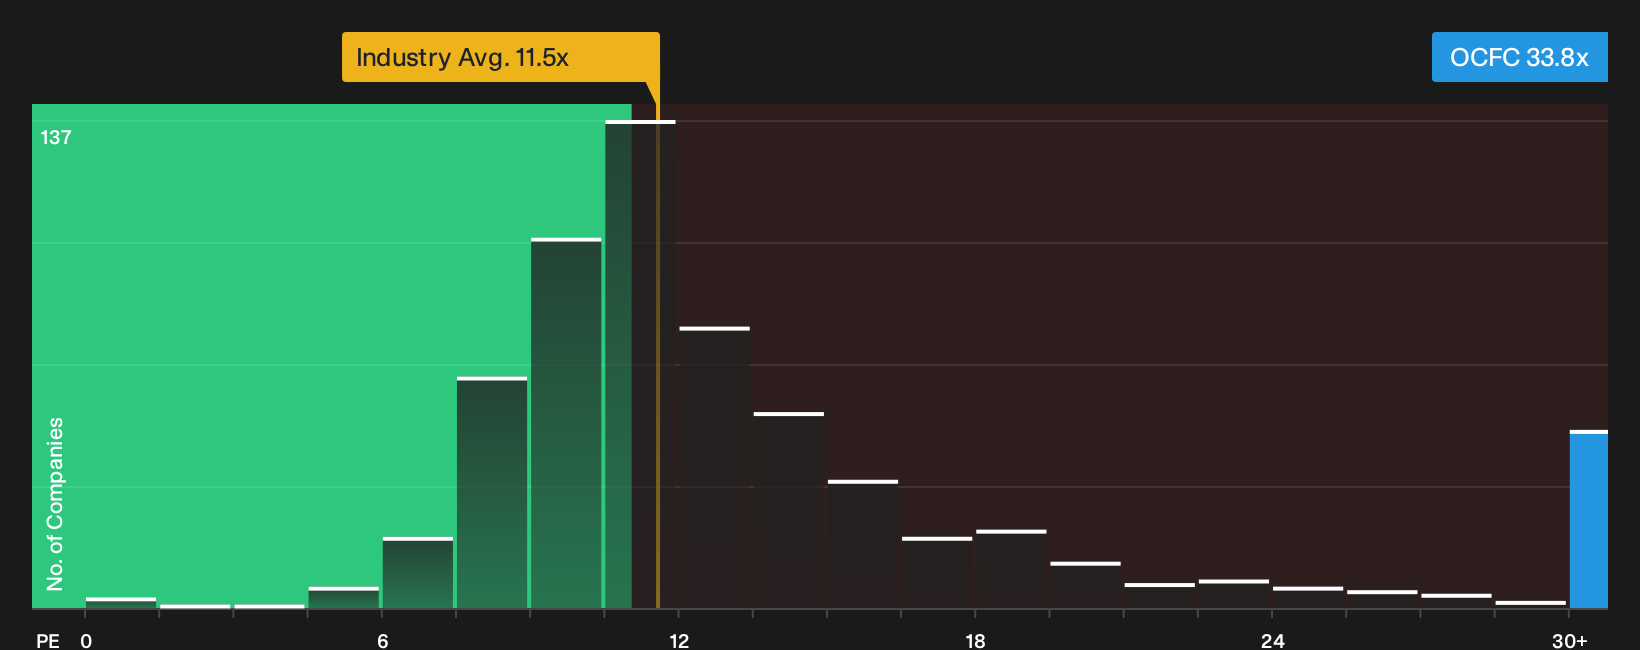
On the flip side, OceanFirst Financial screens expensive on a simple earnings lens. The stock trades on a P/E of 33.8x, compared with 14.5x for peers and 11.5x for the wider US Banks group, and above its own 27.6x fair ratio. That gap points to less margin for error if the upbeat narrative on growth or integration stumbles.
For a closer look at how this earnings multiple stacks up against what the numbers suggest the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
There are mixed messages in the OceanFirst Financial story so far. Consider the divided sentiment and weigh the potential benefits against the red flags by reviewing the 3 key rewards and 5 important warning signs.
Looking For More Investment Ideas Beyond OceanFirst Financial?
If the OceanFirst Financial setup has you thinking more broadly about your portfolio, do not stop with a single ticker. Cast the net wider and pressure test your ideas against fresh opportunities using the Simply Wall St screener before the next round of earnings reshapes expectations again.
- Target resilient balance sheets and steady fundamentals by checking stocks in the list of solid balance sheet and fundamentals (24 results) that can help anchor portfolio risk.
- Hunt for quality at a discount by scanning the 29 high quality undervalued stocks that highlights companies with strong fundamentals trading below estimated fair value.
- Strengthen your income stream by reviewing the 5 dividend fortresses that focuses on higher yielding businesses built around more durable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com