
ASML Holding (ENXTAM:ASML) Could Be 24% Undervalued After Raised Guidance And Q3 Beat
ASML Holding (ENXTAM:ASML) is back in focus after third quarter 2026 results showed higher revenue and net income year over year, alongside raised guidance, a fresh buyback update, and an affirmed interim dividend.
ASML Holding’s share price has eased over the past week and month, with a 7 day share price return of 4.41% and a 30 day share price return of 6.08%. However, the year to date share price return of 44.99% and 1 year total shareholder return of 58.71% still point to strong momentum. This has been reinforced by the Q3 earnings beat, raised full year guidance, ongoing buybacks and the affirmed dividend, as investors reassess both growth potential and export related risks around the €1,430 level.
Spot emerging beneficiaries of the same AI infrastructure build out driving ASML Holding by scanning our hand picked 55 AI infrastructure stocks.ASML Holding now trades well below the average analyst target, even after the recent jump. This raises a simple tension: Is the market being disciplined about export and AI cycle risks, or leaving too much on the table?
Most Popular Narrative: 20% Undervalued
The most followed narrative on ASML Holding pegs fair value at €1,780 per share, which sits above the latest close of €1,430. That gap has become the anchor for investors weighing rich headline multiples against strong profitability and a premium technology position.
The more important issue is therefore not whether China immediately replaces ASML. It is whether the probability of long-term substitution is now high enough to raise ASML’s required return and lower the terminal multiple investors are willing to pay. A DCF is particularly sensitive to that question because most of ASML’s value comes from cash flows expected after the explicit forecast period. In my base model, the terminal value represents about 85% of enterprise value. Small changes to the discount rate or terminal growth assumption therefore have a large effect on fair value.
See why 45 investors see ASML Holding as 20% undervalued.
Result: Fair Value of €1,780 (UNDERVALUED)
Still, the ASML Holding story can fray quickly if export controls tighten further or if domestic Chinese lithography tools gain traction faster than investors expect.
Find out about the key risks to this ASML Holding narrative.
Another View: What ASML Holding’s P/E Is Really Saying
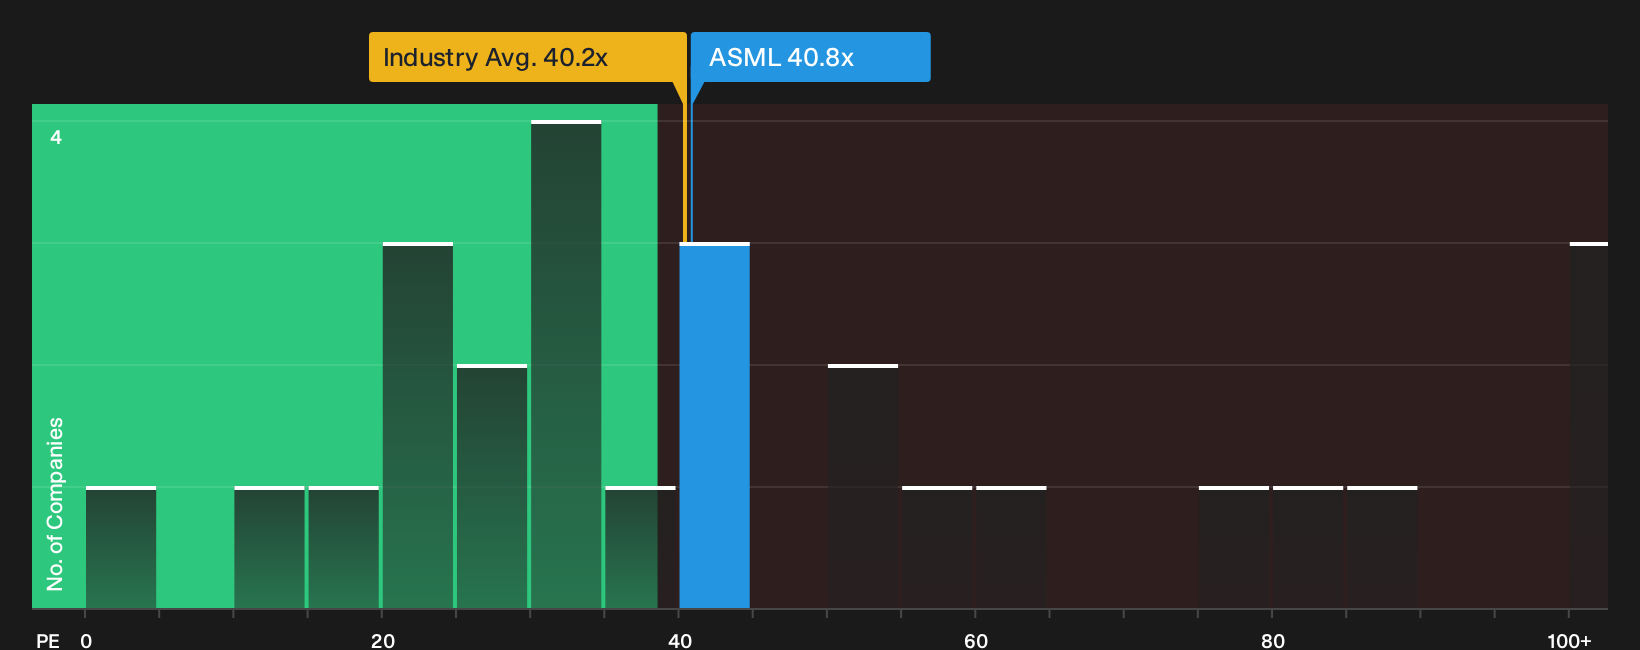
A different lens on ASML Holding uses its P/E. The stock trades at 40.8x earnings, above both the peer average of 35.3x and the European semiconductor level of 40.2x. Yet the fair ratio of 64.2x points to a market that could still re-rate the shares upward or compress the premium sharply if sentiment changes.
That gap leaves investors weighing whether current pricing reflects early caution or only a partial adjustment to growth and China related risks, and whether the fair ratio is a destination or just a ceiling the market may never test, given the volatility already seen.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ASML Holding so far. If you want to move fast and decide where you stand, start by weighing its 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ASML Holding?
If ASML Holding has sharpened your focus, do not stop here. Fresh ideas now can shape the portfolio you want a few years from today.
- Target resilience first and scan a 223 resilient stocks with low risk scores that filters for businesses with lower risk scores before you commit fresh capital.
- Hunt for value and check a 610 high quality undiscovered gems where strong fundamentals meet limited market attention.
- Raise the quality bar and build a watchlist from the list of solid balance sheet and fundamentals (207 results) to keep potential weak financials off your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com