
ABB (SWX:ABBN) Moved, What Is Behind The Attention Today?
ABB stock reacts to earnings, partnerships and buybacks
ABB (SWX:ABBN) is in focus after third quarter results on 20 October showed higher year on year revenue, alongside fresh partnerships in power distribution and data centers and progress on its ongoing share repurchase program.
ABB's latest updates land after a choppy few months, with the share price down 13.1% over 30 days and 10% over 90 days, even as the year to date share price return of 13.78% and 1 year total shareholder return of 18.88% reflect stronger longer term momentum.
Scan ABB's latest moves in data centers and power grids against a curated peer set by jumping straight to the 42 power grid technology and infrastructure stocks in the same theme.
ABB now trades about 10% below one intrinsic estimate and roughly 16% under the average analyst target after a sharp pullback. Is that simply mispricing recent progress, or fair caution on execution and capital returns risk?
Most Popular Narrative: 40.3% Overvalued
ABB closed at CHF69.68, while the most followed narrative on the stock pegs fair value at CHF49.68, implying a wide valuation gap that hinges on how its industrial platform story plays out over the next decade.
Across these decades, ABB’s recurring strategic question has been: Which businesses strengthen its ability to make customers’ industrial assets operate better together?
The answer has changed with technology, markets and management. Some acquisitions expanded that capability; some disposals released capital or reduced complexity; others corrected earlier mistakes. The durable connection is electricity, movement, measurement and control, progressively linked by software into an increasingly intelligent operating architecture for industry.
See why 1 investors see ABB as 40% overvalued.
According to Tokyo, who authored the narrative, this long industrial track record and ongoing portfolio reshaping are central to the view that ABB is a high quality operator, yet the current pricing looks stretched relative to the assumed fair value of CHF49.68 that is based on a 5.96% discount rate, 7% revenue growth and a 13% margin over time.
The same work assumes a future P/E of 22x versus a higher recent level and arrives at an implied internal rate of return that relies heavily on ABB's dividend to push total returns into positive territory, which is a much more cautious stance than the DCF output that currently points to ABB trading about 10% below an intrinsic estimate and below the average analyst target of CHF82.70.
Both views can sit side by side for investors, with the narrative highlighting long term execution risks and re rating potential, while the SWS DCF model and analyst targets instead emphasize ABB's forecast earnings growth of 8.7% per year and revenue growth of 9.1% per year relative to the wider Swiss market.
Result: Fair Value of CHF49.68 (OVERVALUED)
Still, ABB’s story could be challenged if electrification and data center demand cool unexpectedly or if portfolio reshaping fails to translate into sustained profitability.
Find out about the key risks to this ABB narrative.
Another View on ABB: DCF Signals Underpricing
The narrative fair value of CHF49.68 paints ABB as expensive. A different lens tells a very different story. The SWS DCF model indicates ABB at CHF69.68 is trading below an estimated future cash flow value of CHF77.47, which points to a discount rather than a premium.
This gap between a narrative framing ABB as 40.3% overvalued and a cash flow model that sees the stock as 10.1% below an internal estimate raises a practical question for investors. Which set of assumptions feels closer to how you think ABB will convert its electrification and automation footprint into cash over time, and which risk are you more willing to run: overpaying for quality or underestimating execution challenges?
Look into how the SWS DCF model arrives at its fair value.
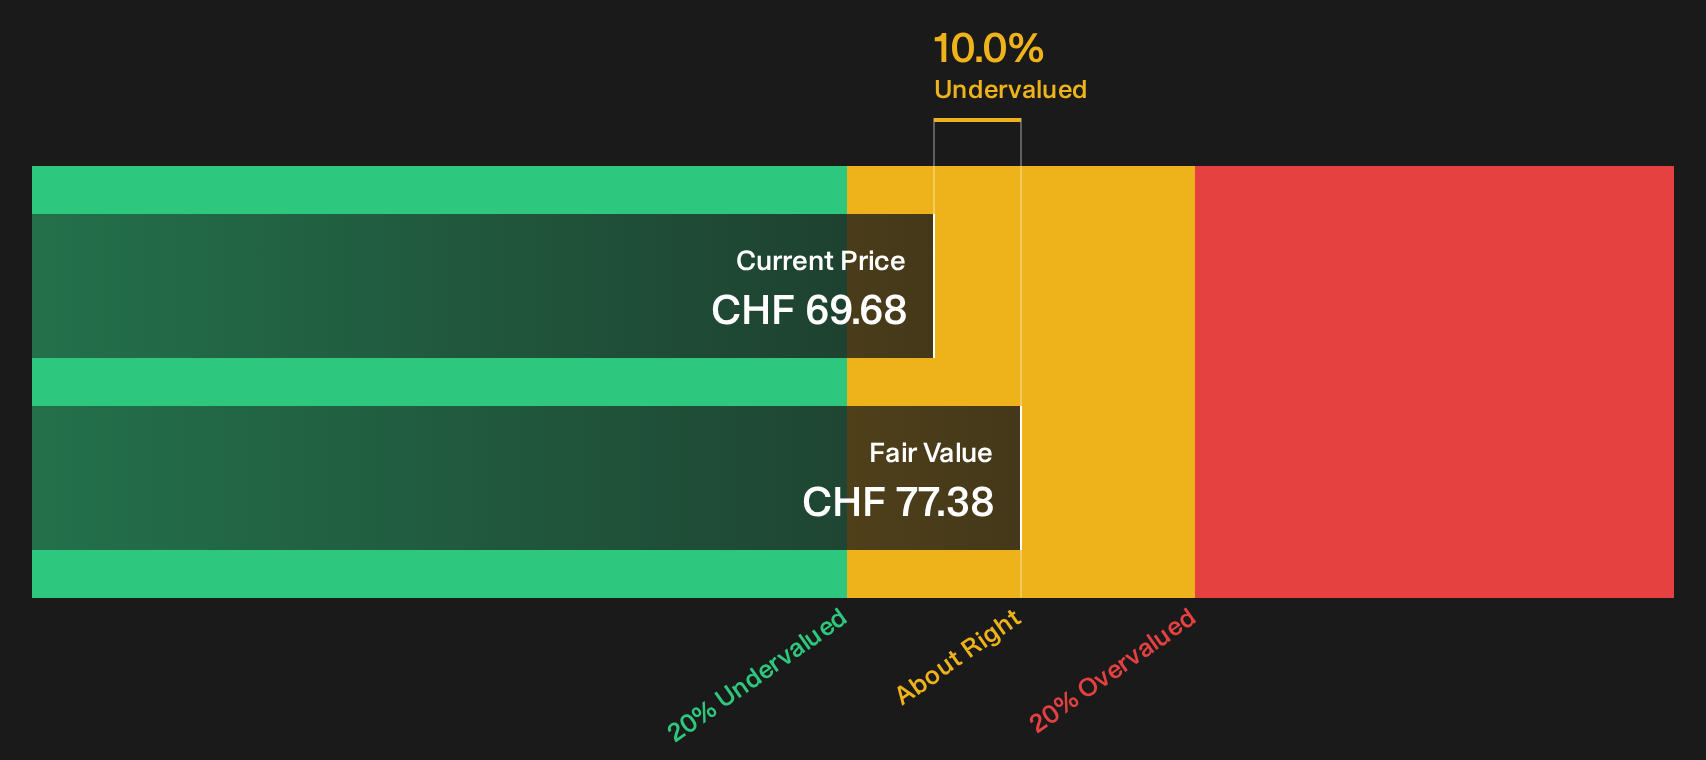
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ABB for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on ABB so far. If you want to move past headlines and sentiment, examine the underlying data, consider both the potential advantages and drawbacks, then review the 3 key rewards and 1 important warning sign.
Looking for more ABB investment ideas beyond this story?
If ABB has sharpened your focus on quality and risk, do not stop here. The next opportunities often sit just outside the obvious watchlist.
- Target steadier compounding by scanning firms that combine earnings power with strong balance sheets through the list of solid balance sheet and fundamentals (207 results).
- Hunt for price dislocations where fundamentals look stronger than sentiment by running the 195 high quality undervalued stocks.
- Build your own shortlist of overlooked potential by checking the 610 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com