
Interparfums (ENXTPA:ITP) Rebounds In The Third Quarter, Is The Stock Above Fair Value?
Interparfums (ENXTPA:ITP) just reported third quarter 2026 sales of €265.5 million, up 4.8%, with momentum driven by Coach and Montblanc, even as certain regions remain difficult.
The rebound in Interparfums' third quarter sales lands alongside strong recent trading in the stock, with a 1-month share price return of 15.14% and a 90-day gain of 44.78% helping push the year-to-date share price return to 46.45%. However, the 5-year total shareholder return is still down 11.56%, which suggests short term momentum has picked up after a tougher multi year stretch.
Scan beyond Interparfums and see how other fragrance and consumer brands with fresh momentum stack up in our hand picked 610 high quality undiscovered gems.
After a 46% year to date share price jump, Interparfums now trades above both analyst targets and some fair value estimates. Is the market overreacting to the third quarter rebound, or is it finally catching up?
Price-to-Earnings of 25.8x: Is it justified for Interparfums?
On the latest numbers, Interparfums trades on a P/E of 25.8x, which puts the share price at a premium that current earnings need to work hard to support.
The P/E ratio compares what you pay today for each euro of profit that Interparfums generates. For a fragrance and cosmetics producer with €118.9 million of net income on €866.7 million of revenue, this gauge reflects how much confidence the market currently places in the company’s profitability relative to its existing earnings.
Against that backdrop, the stock appears expensive on several fronts. The current P/E of 25.8x is higher than the estimated fair P/E of 20.5x that the fair ratio suggests the market could move toward. It also sits above the peer average multiple of 21.3x and the wider European Personal Products industry on 18.5x, which indicates investors are paying a materially higher price for each euro of earnings than for comparable companies.
Explore the SWS fair ratio for Interparfums.
Result: Price-to-Earnings of 25.8x (OVERVALUED)
Still, the Interparfums story can change quickly if growth in key regions like North America cools or if major licensing partners rethink contract terms.
Find out about the key risks to this Interparfums narrative.
Another View on Interparfums’ Valuation
The P/E screen paints Interparfums as expensive, yet the SWS DCF model tells a slightly different story. On that framework, the estimated future cash flow value is €31.92 per share versus a market price of €34.98. This points to an overvaluation, although with a narrower gap. Which signal carries more weight for you?
Look into how the SWS DCF model arrives at its fair value.
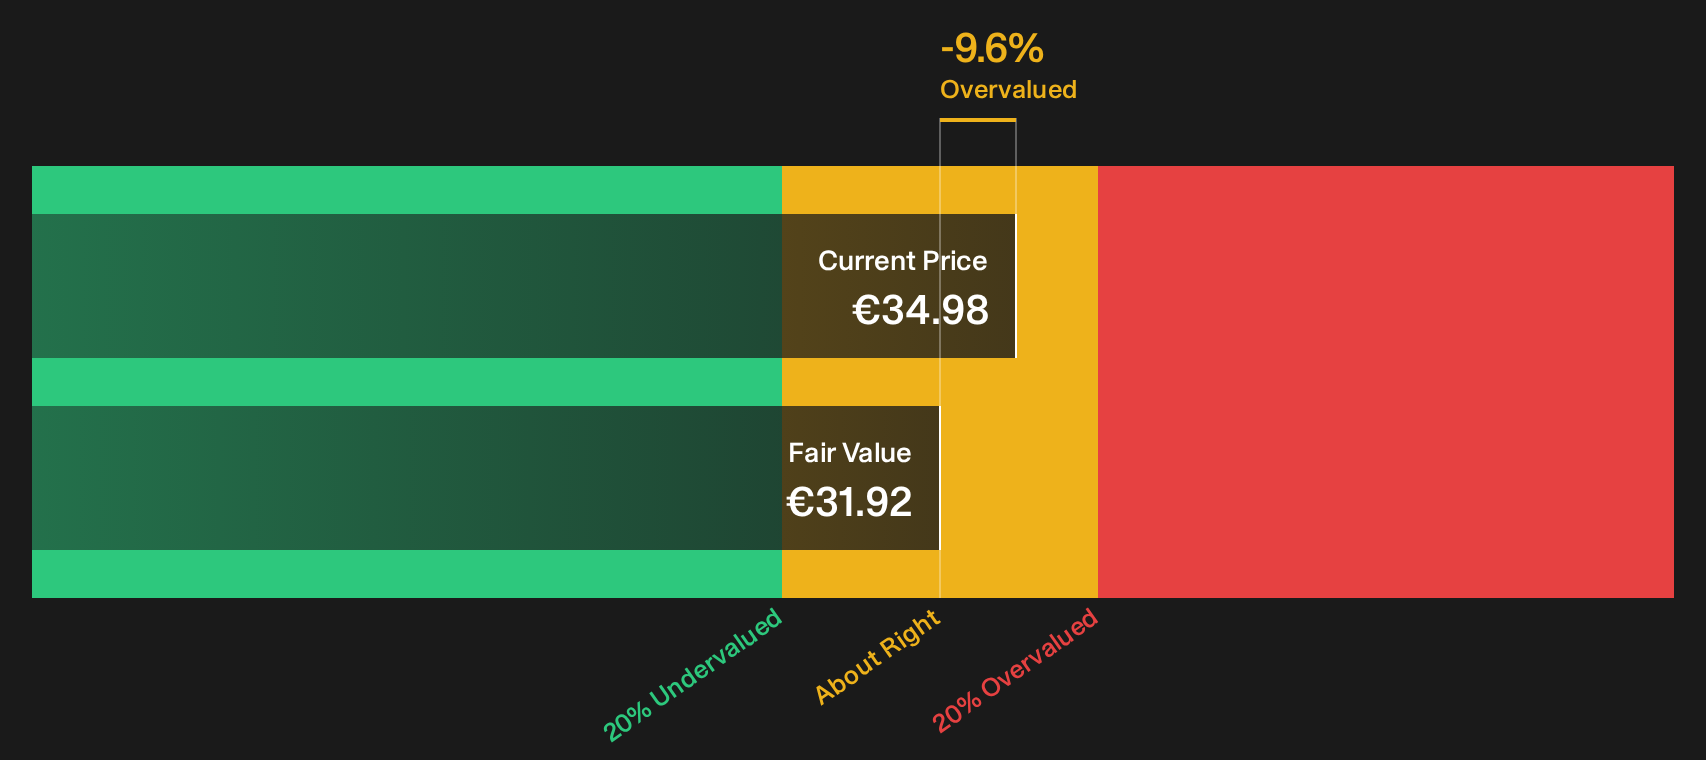
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Interparfums for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this Interparfums story pulls in opposite directions, with fresh share price momentum sitting alongside both flagged risks and identified rewards. Act quickly to get across both sides of the data and shape your own view by checking the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Interparfums?
If Interparfums has sharpened your focus on valuation and momentum, do not stop here. Broaden your watchlist with other candidates filtered by cash strength, income potential, and share price quality.
- Spot potential bargains early by scanning companies that show up in the 195 high quality undervalued stocks before they land on everyone else’s radar.
- Build a steadier income stream by focusing on businesses highlighted in the 224 dividend fortresses that may offer higher yields with supportive fundamentals.
- Prioritise resilience by filtering for robust balance sheets through the list of solid balance sheet and fundamentals (207 results), so short term shocks are less likely to knock your portfolio off course.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com