
Man Group Stock In Focus As Insurer Expands Private Credit Commitment
- Man Group announced that Meiji Yasuda Life Insurance Company intends to lift its capital commitment to Man Group strategies to JPY 200 billion over three years, with a strong emphasis on private credit and new product development for Japanese investors.
- The tie up deepens Man Group’s role as a partner to a large insurer client, broadening fee potential while adding technology and research collaboration through the Oxford Man Institute for Meiji Yasuda’s internal teams.
- We will look at how Man Group's investment narrative is shaped by Meiji Yasuda's expanded JPY 200 billion private credit commitment.
Scan how Man Group’s insurer partnership fits into the broader hunt for fee-based cash flows by comparing it with our handpicked 5 dividend fortresses that rely on recurring income streams.
What Is Man Group's Investment Narrative?
To own Man Group, you need to believe in a fee led asset manager that can keep attracting and retaining third party capital across cycles. The expanded Meiji Yasuda partnership sits squarely in that story. A planned JPY 200 billion private credit tilt over three years reflects demand for less liquid income strategies and gives Man Group more visibility on near term flows, without requiring heavy capital from its own balance sheet.
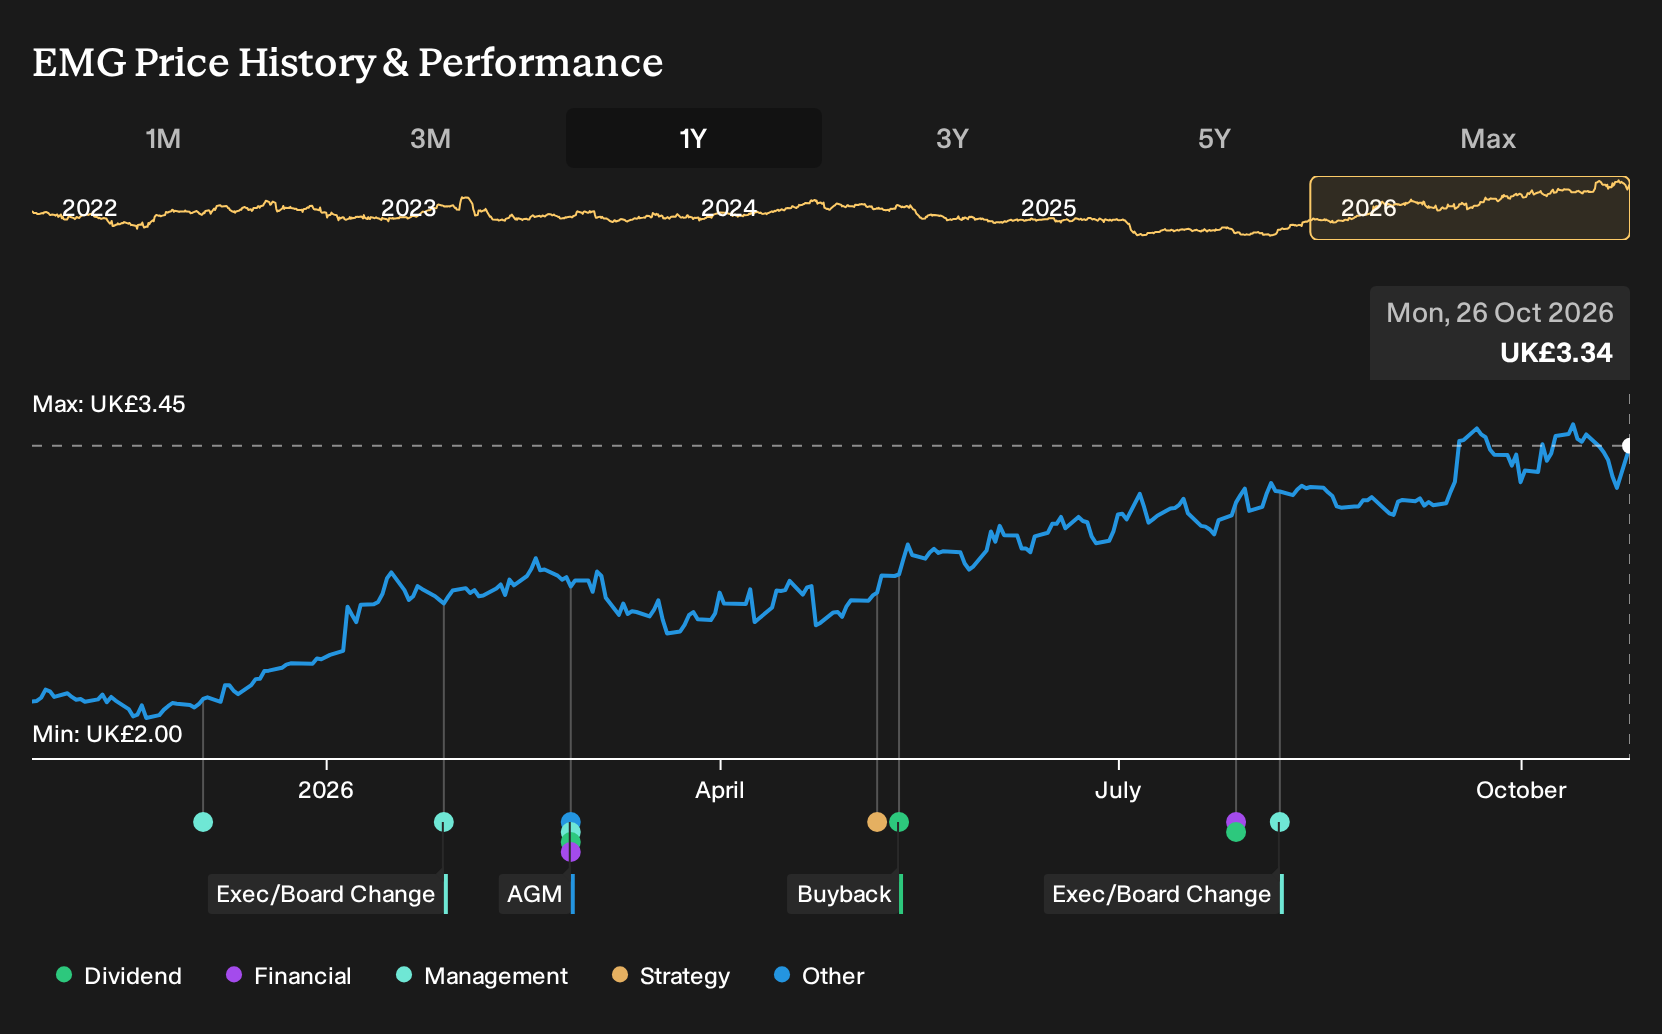
In the short term, the key levers remain investment performance, fund distribution and cost discipline. Recent earnings growth, higher net profit margins at 19.2% and strong 1 year share returns indicate that the business can convert flows into profits when execution aligns. Risks around an unstable dividend record and significant recent insider selling remain, yet this new insurer mandate slightly improves the backdrop for fee resilience and platform scale.
Even so, there is a pressure point in the Man Group story that could matter far more if ...
There's only one way to know the right time to buy, sell or hold Man Group. Head to Simply Wall St's company report for the latest analysis of Man Group's Fair Value.
Exploring Other Perspectives
Some of the most optimistic analysts saw this Meiji Yasuda style expansion as fuel for Man Group’s private credit story. Before this news, they were pencilling in revenue of about $2.3b and earnings of $703.6m by 2029. That is a far brighter path than consensus, so treat it as one of several views to evaluate independently.
Explore 4 other Man Group fair value estimates, including one that suggests there could be as much as 174% upside from the current price!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Man Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Man Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Man Group's overall financial health at a glance.
Looking For More Ideas Beyond Man Group?
If this Meiji Yasuda partnership has sharpened your view on Man Group, it can be helpful to line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about protection on the downside, scan a curated set of 4 resilient stocks with low risk scores that score well on resilience.
- If you want potential mispricing combined with quality fundamentals, compare Man Group against 5 high quality undiscovered gems that the broader market may not be watching closely.
- When balance sheet strength matters more than excitement, build a shortlist from a list of solid balance sheet and fundamentals (10 results) that can better withstand tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com