
Airbus Stock And Trade Rules Put Aerospace Suppliers In Focus
Fresh scrutiny of a €3.4b European Investment Bank loan to Airbus has dragged an old trade dispute back into the spotlight, and that ripple can matter for your portfolio as much as for aircraft makers. Trade rules shape costs, pricing power and order books, which means potential winners and losers on both sides of the Atlantic. This piece walks through three stocks tied to this news and how that exposure might affect their risk and return profile.
The stocks covered below are just a small sample of what this trade story touches, and the full screen surfaced 38 more aerospace and defense companies with equally compelling narratives that are not unpacked here. If you want to move faster, head straight into the Aerospace and Defense Stocks screener to identify, analyze and focus on the highest conviction ideas that match your own risk profile.
Lisi (ENXTPA:FII)
Lisi is a French fastener and components specialist for aircraft makers, which ties it directly to the Aerospace and Defense Stocks screener focus on major civil aviation suppliers. The LISI Aerospace unit generated about €1.25b of the roughly €1.80b total, with LISI Automotive adding about €546 million. The group’s market value is about €2.84b.
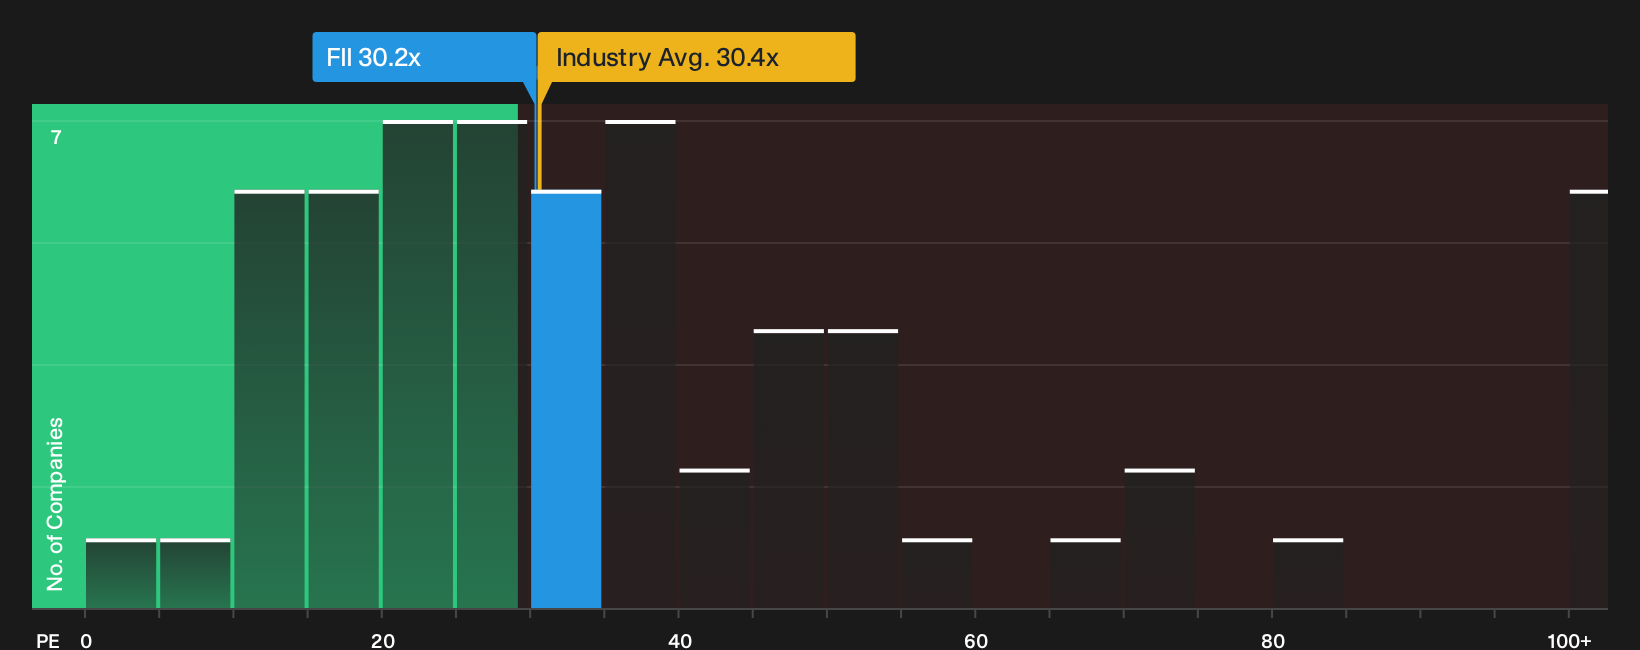
Lisi gives you pure supplier exposure to large civil aircraft build rates. Earnings growth has been strong, profitability is improving and the stock trades on a P/E that is in line with European aerospace peers while screening below some fair value estimates. The appeal hinges on how one unseen pressure shapes future demand and pricing power.
That pressure point is exactly what the 4 key rewards and 1 important warning sign explains, so you can see what might accelerate or stall Lisi’s next chapter.
Airbus (ENXTPA:AIR)
Airbus is the flagship manufacturer in this Aerospace and Defense Stocks screener, linking your portfolio directly to global jet production, military programs and satellite infrastructure, so it is worth understanding how its scale and political role shape both upside and risk.
"Supply chain bottlenecks Political orders are neither pure blessing nor curse; they are intrinsic to Airbus’ role as a strategic European asset."
What happens to Airbus margins if a single assumption about future aircraft financing and cross border trade quietly shifts in the background.
If that assumption about financing starts to shift, the full narrative for Airbus maps how Airbus’ political role, supply chain pressures and order momentum could be decoupling in plain sight.

ESCO Technologies (ESE)
ESCO Technologies plugs into the screener as a US headquartered supplier to aviation and defense programs, but its reach extends across utility diagnostics and RF test equipment, with the Aerospace & Defense segment generating about $632 million of revenue, Utility Solutions Group about $391 million, Test around $267 million, and the stock valued at roughly $6.0b.
ESCO Technologies gives you a different angle on the Airbus Boeing trade story, since a big slice of its business leans on aircraft and defense program volumes yet the thesis increasingly hinges on a quieter power and grid investment cycle.
"Continued long-term growth in global electricity demand driven by trends such as electrification of transportation, grid expansion for data centers and AI, and increased renewable integration is described as positioning ESCO Technologies' Utility Solutions Group and Doble for sustained order momentum and rising recurring revenues in utility infrastructure, supporting future top-line growth and improved earnings visibility."
What happens to ESCO Technologies’ earnings power if a single assumption about how quickly that order book converts into higher margins starts to shift?
If that shift is beginning, the full narrative for ESCO Technologies shows how ESCO Technologies’ grid exposure, aerospace ties and valuation could be quietly setting up an underappreciated earnings mix shift.

Seeking Alternatives Before The Crowd?
Fresh ideas move first, not last. While attention lingers on Airbus and its peers, other themes are building quiet breakout momentum under the radar for now. Consider moving sooner rather than later.
- Spot sturdier balance sheets before money chases them by running the list of solid balance sheet and fundamentals (207 results) and pinpointing financially resilient businesses while it still matters.
- Identify income ideas with yield potential by scanning the 224 dividend fortresses and filtering for payouts that might hold up when sentiment drops.
- Track the build out behind AI demand by checking the 55 AI infrastructure stocks and monitoring which enablers could see capital flow next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com